
What Concrete Pumping Doubters Got Wrong
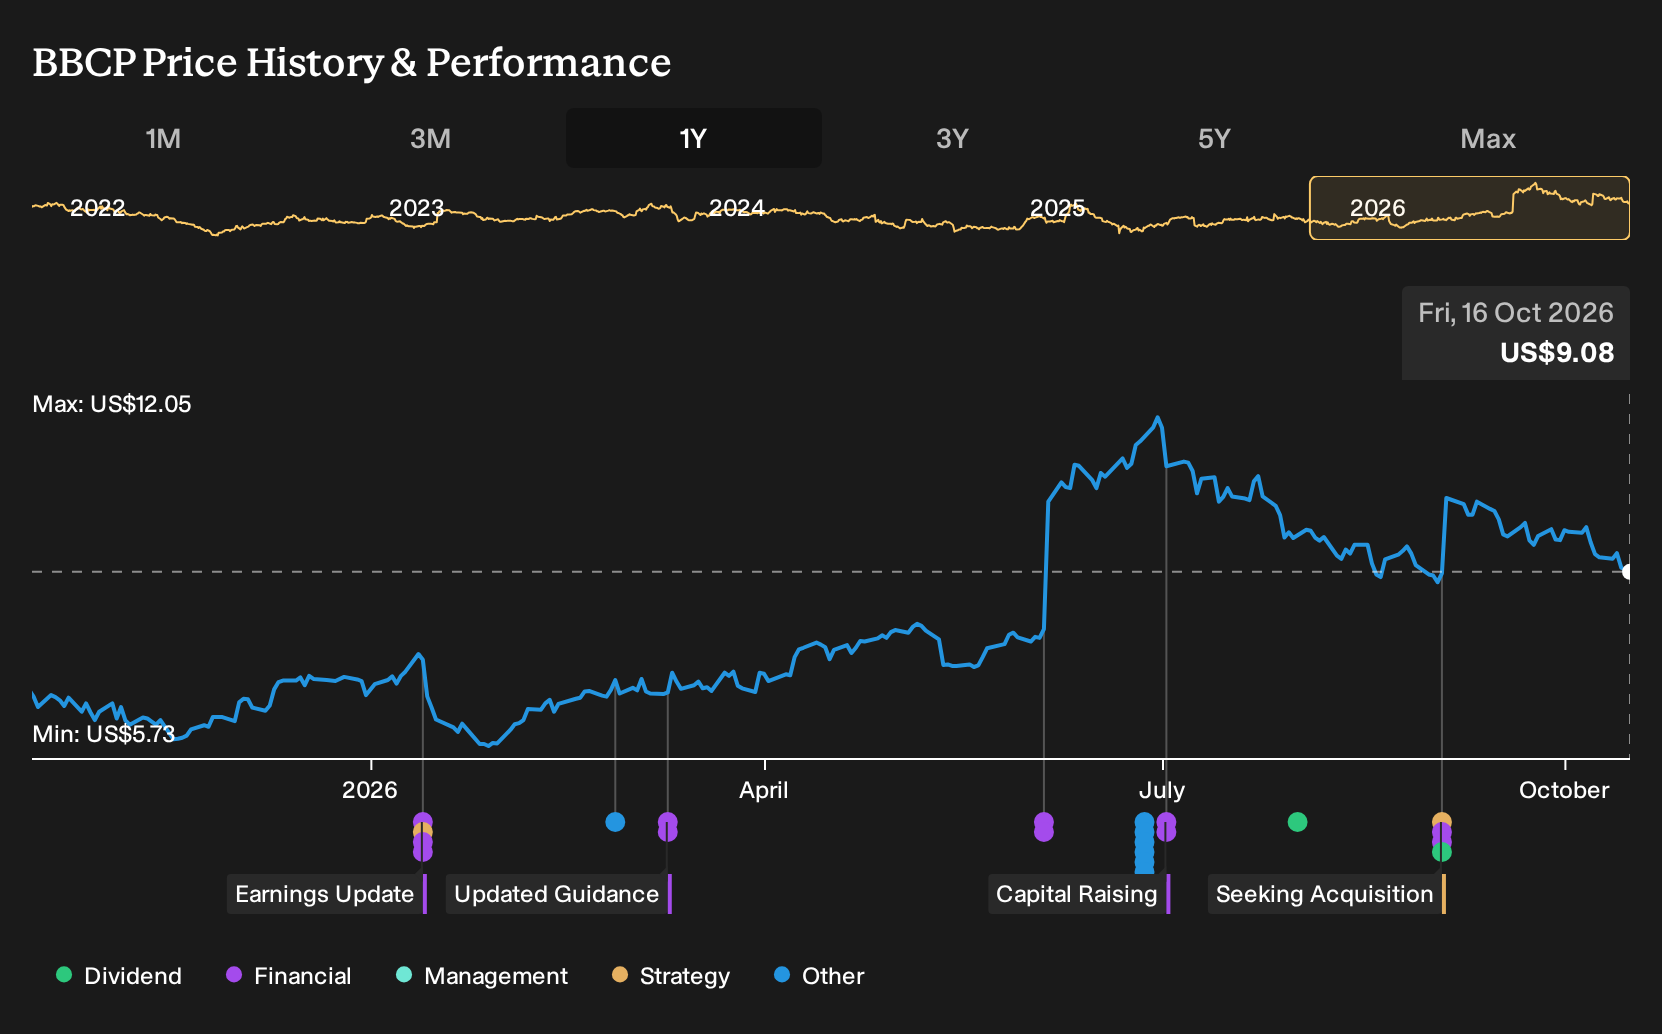
Concrete Pumping did not just tread water over the last year. For Concrete Pumping shareholders, the return over the past year was 42.0%, including dividends. If you had been weighing an entry back on 16 October 2025, you were staring at clashing stories about infrastructure tailwinds, environmental headwinds, heavy debt and capital needs. With fresh results now showing higher quarterly revenue and a wider net margin, what exactly were early buyers betting would matter most?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Concrete Pumping harder to judge, start where the gap is still open and scan 33 high quality undervalued stocks.
The Two Concrete Pumping Stories Investors Were Weighing
The shares cost US$6.68 at the start of the period, and Concrete Pumping investors were effectively choosing between two sharply different stories about where value might sit.
On the optimistic side, the bull Narrative put Fair Value at US$7.75, or 16% above the start price, assuming 2.2% annual revenue growth and profit margins reaching 2.9% within three years.
The bear Narrative pointed to a Fair Value of US$6, or 10% below the start price, highlighting long term decarbonization and modular building trends as potential threats to concrete demand and to Concrete Pumping’s future equipment utilization.
What The Results Changed For Concrete Pumping
Concrete Pumping reported Q3 2026 revenue of US$116.766m and net income of US$4.49m, with net margin at 3.8% versus 3.1% a year earlier. That margin outcome sat above the bull case’s 2.9% target, but the period was only one quarter of a three year story, so the evidence cut both ways.
The key assumption here was margin resilience. When you assess another contractor, track whether profit per dollar of sales moves toward or away from the margin level used in the original thesis.
What Concrete Pumping's 42% Run Leaves You Paying For
Concrete Pumping now trades at US$9.08 after a 42.0% gain over the past year. The selected Narrative’s Fair Value sits above the current price, framing that gap as a view, not a fact.
The argument leans on large project work and Eco-Pan cash generation, with fleet capex and leverage as the main swing factors. A buyer today would need confidence that large data center and infrastructure projects keep offsetting softer light commercial and residential work.
"The main factor that has to go right is that large-scale data center, chip plant, infrastructure, and Eco-Pan waste management projects continue to support revenue and EBITDA while the company manages higher near-term capex and progresses toward its leverage targets."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond Concrete Pumping
Concrete Pumping ties into physical projects. Your next step could sit in the power behind them.
Every data center and heavy industrial site needs dependable electricity, not just poured concrete.
One large energy equipment specialist focuses on turbines, transformers, and grid hardware that keep power flowing.
Its installed machines often lead to long service relationships, with maintenance, upgrades, and software layered on.
As electricity demand shifts with data centers and grid upgrades, that service-heavy model could face meaningful change.
That argument has a Narrative and a number behind it. → See the company one Narrative values 38% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com