
What Urban Outfitters Holders Bought Into
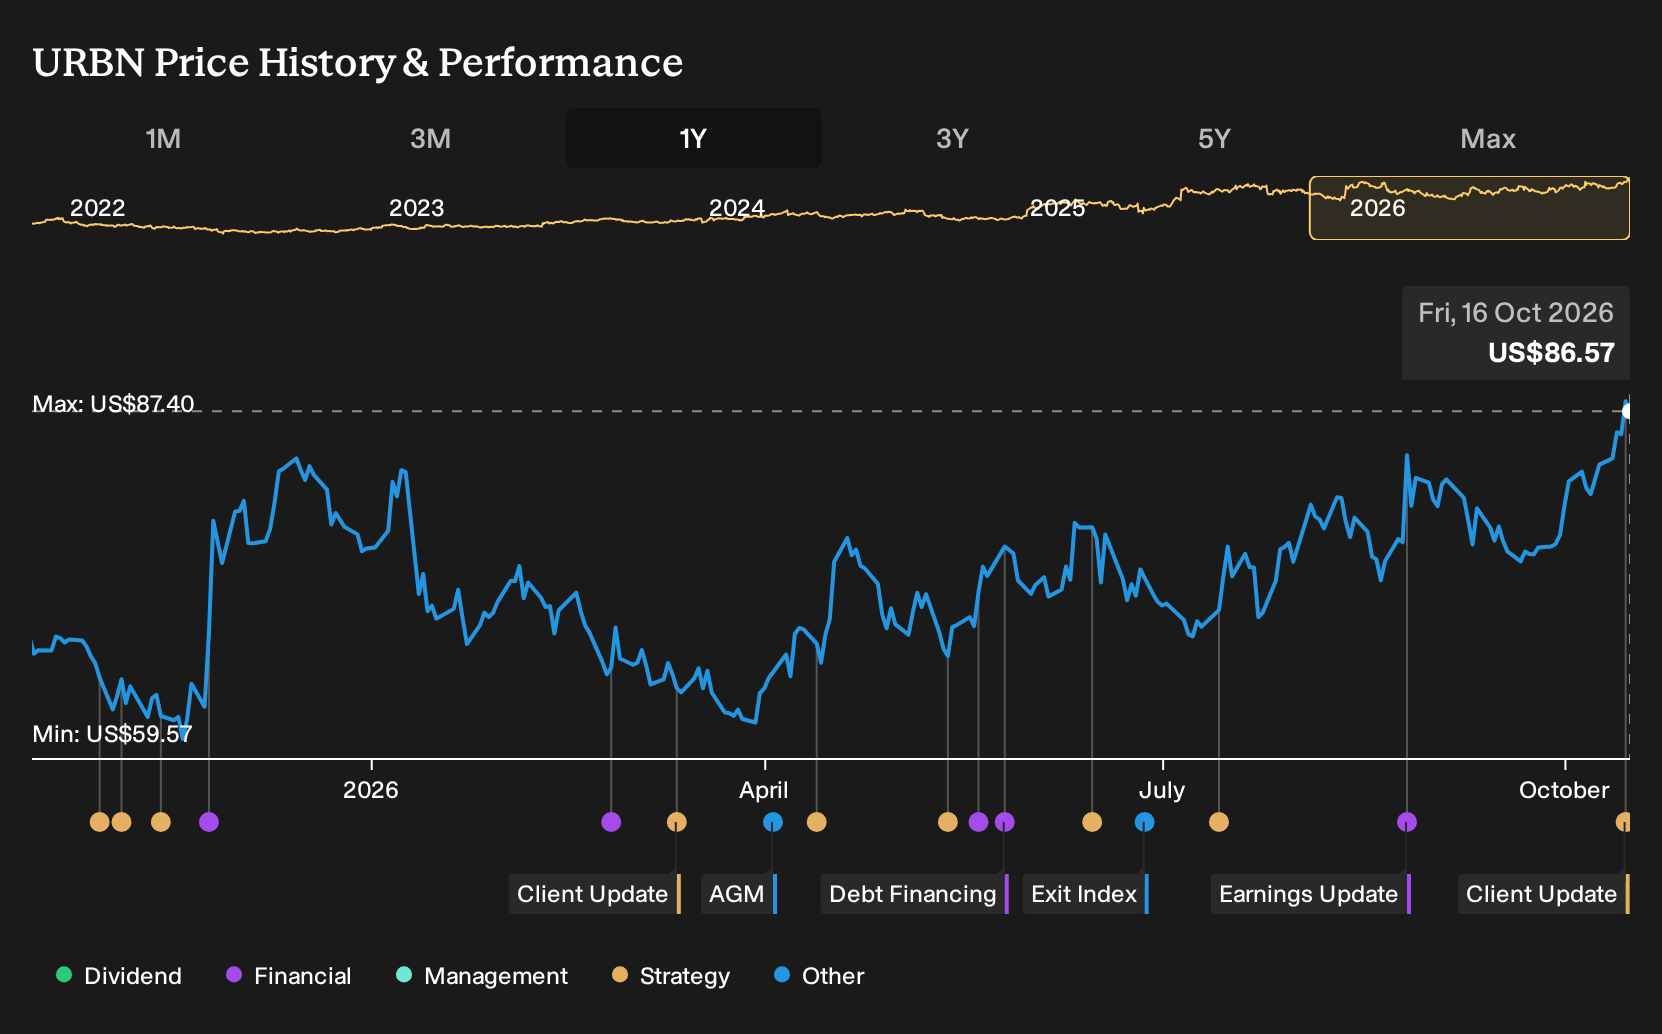
If you only glanced at headlines about Urban Outfitters wrestling with tariffs, higher fuel costs and questions about overvaluation, you might not expect shareholders to have much to show for the ride. For Urban Outfitters shareholders, the return over the past year was 29.4%, including dividends. If you had bought in back in October 2025, with bulls touting omnichannel momentum and bears warning on margin pressure, what exactly in the early evidence justified taking that risk?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Urban Outfitters. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Two Urban Outfitters Stories Investors Had To Weigh
The shares cost US$66.6 at the start, and anyone looking at Urban Outfitters had to decide which story felt more realistic.
The bullish Narrative put Fair Value at US$79.67. It leaned on 7.1% annual revenue growth and a 7.1% profit margin assumption, supported by stronger Millennial and Gen Z spending plus heavier e-commerce integration.
The bearish view set Fair Value at US$47.28. It assumed only 2.2% yearly revenue growth and a 6.8% margin, with pressure from inventory issues and higher costs tied to store expansion and online rivalry.
What The Urban Outfitters Results Actually Tested
Urban Outfitters posted Q2 2027 revenue of US$1.66b and net income of US$240.7m, with net margin rising from 9.6% in Q2 2026 to 14.5%. That margin outcome leaned toward the bullish case that talked about healthier profitability. Episodes of share-price weakness around rate worries and cost shocks gave the cautious story something to hold onto, so the evidence cut both ways.
The key assumption here was profitability, not just growth. When you see a forecast built on better margins, it can be useful to check how net margin and absolute profit move over several reports rather than focusing only on sales headlines or the share chart.
What Urban Outfitters’ Current Price Already Assumes
Urban Outfitters now trades at US$86.57, with this Narrative’s Fair Value set below that level. The selected Narrative treats recent record performance as already reflected in the quote, and then focuses on capex, margin pressure and profit mix as the main swing factors.
A buyer today is effectively assuming multi brand growth, Nuuly scale and AI projects protect earnings. The open question is how those plans cope with fuel surcharges, markdown risk and heavier depreciation.
"The current numbers and narrative imply that Urban Outfitters’ share price already reflects a fairly valued, bullish setup in which multi brand growth and gross margin support are largely priced in. Although Nuuly is currently growing revenue with several hundred thousand subscribers and new automated facilities planned to support up to about 1.2 million subscribers, the roughly 70 basis point quarterly gross margin headwind from fuel surcharges risks absorbing much of the expected operating leverage from lower logistics cost per order."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking One Step Beyond Urban
Urban Outfitters highlights one flavor of consumer risk and reward. Retail dynamics, margin shifts, and fashion cycles all sit in plain view.
Step sideways and a different puzzle appears. E-commerce and digital payments in emerging markets connect shopping, lending, and money transfers.
One company in that space channels cash into expanding its loan book. Reported free cash flow falls even as earning assets climb.
If you care about Urban Outfitters style trade offs, this contrast helps. The same accounting line can look like strain or reinvestment, depending on how the story ends.
One Narrative has already put a figure on it. → Uncover the company trading 43% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com