
Berkshire Hathaway Raised Its Stake in Bending Spoons to 4%. That’s a Big Vote of Confidence Retail Investors Should Follow.
Berkshire Hathaway (BRK.A) came back to Bending Spoons (BSP) roughly three months after supporting its Nasdaq debut. On Oct. 14, the company said that it had agreed to buy 10 million newly issued ordinary shares at $33 each in a private placement.
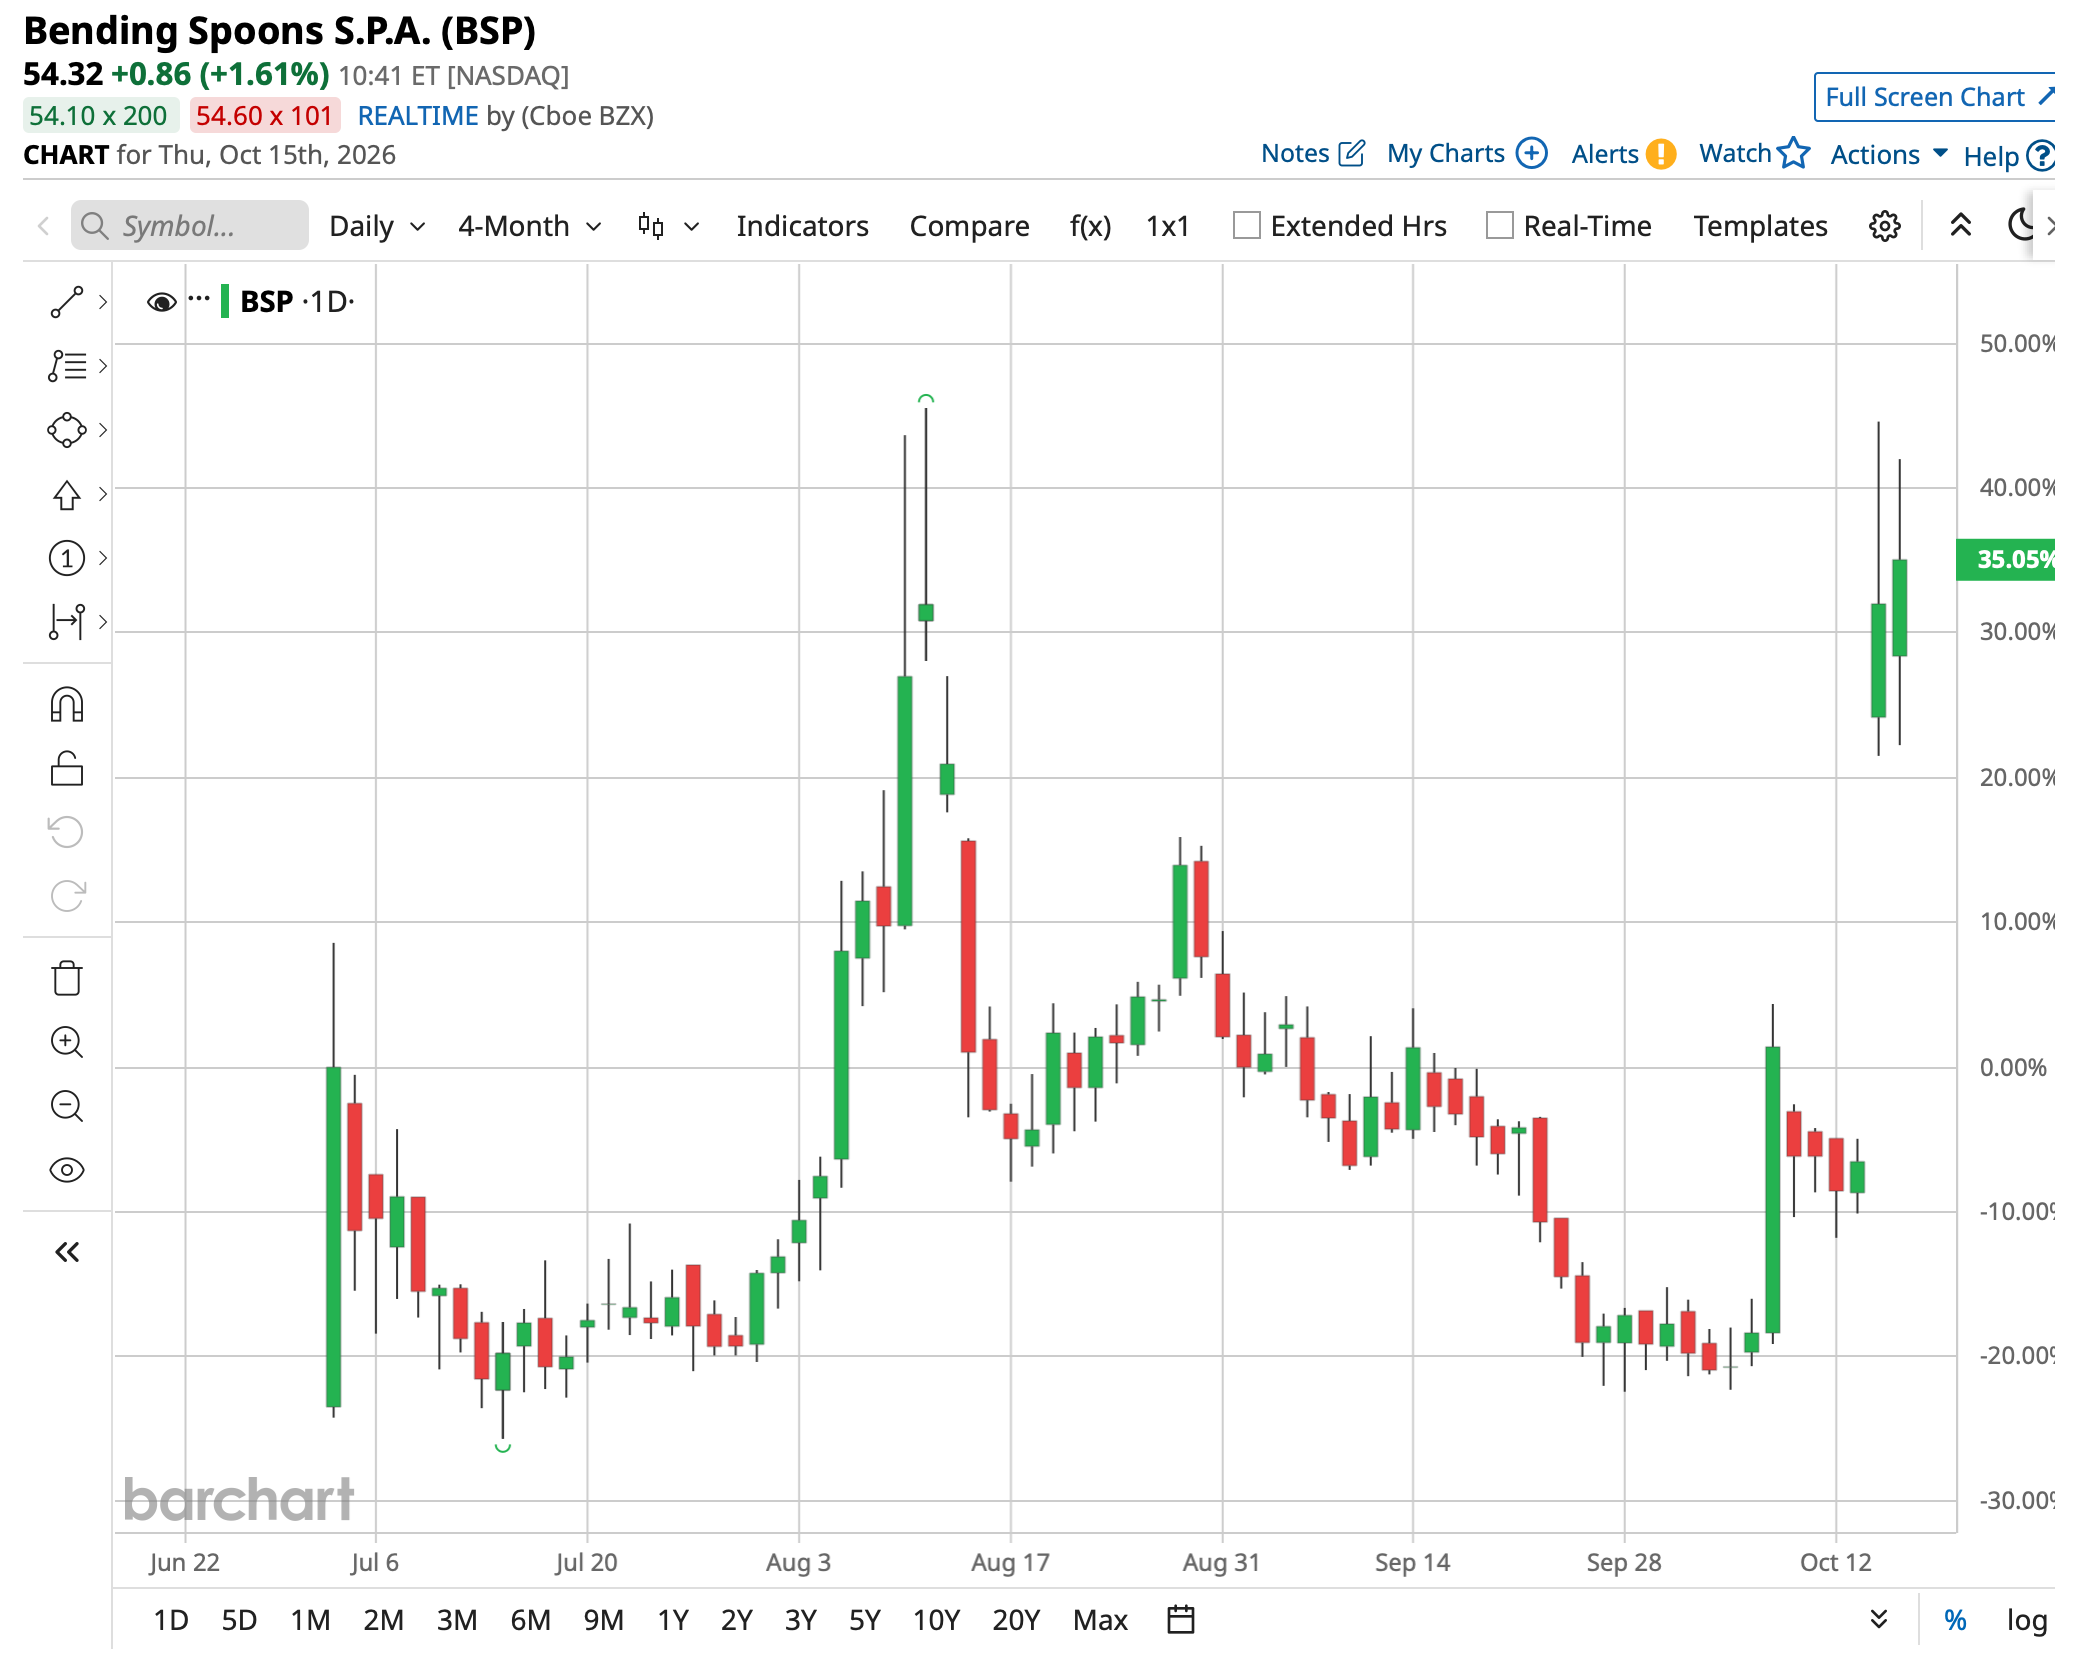
The market saw this news as more than just another raise. Bending Spoons shares jumped 41% to $53.46 that day. BSP stock is also up 47% over the past three months.
For a newly public Italian technology company that grows by buying digital-subscription and software businesses, the extra capital from Berkshire gives it more firepower for future deals. So, how should investors look at this move and the opportunity in BSP stock? Let’s take a closer look.
Why Berkshire Returned So Quickly
Berkshire Hathaway has moved fast to increase its stake in Bending Spoons. The firm put in another $330 million, taking its ownership to 4%. That comes on top of the $600 million that it already invested at the initial public offering (IPO). In total, Berkshire has now put roughly $930 million into the company.
This looks like a deliberate follow-on. Berkshire already reviewed the IPO documents, the operating setup, and the acquisition-focused model, then decided to add more capital within three months of the Nasdaq listing.
The timing is notable because Bending Spoons is still early as a public company. Its IPO closed on July 2 at $29 per share and raised about $953.9 million in gross proceeds. The new private placement gives management fresh cash for deals without having to lean only on the public markets.
At face value, the move shows Berkshire still likes Bending Spoons’ approach of buying digital businesses, improving their operations and products, and then using the gains to fund more acquisitions. Adding capital this soon after the IPO suggests the firm thinks the strategy is working better or faster than it first expected.
What Powers Bending Spoons’ Growth?
Bending Spoons put up strong numbers in the second quarter of 2026. Revenue hit $704 million, up 126% year-over-year (YOY). Operating income rose 139% YOY to $240 million, while adjusted operating income jumped 150% YOY to $381 million.
Diluted EPS came in at $0.28, a 163% YOY increase, while adjusted EPS reached $0.46, up 167% YOY. In May 2026, the company closed the Tractive deal for an enterprise value of $759 million, adding a subscription pet-tracking and health platform. At the end of the quarter, the leverage ratio was 2.4 times. Cash and cash equivalents stood at $793 million, plus the company had $1.28 billion available under its revolving credit lines.
That growth has shown up in BSP stock. Bending Spoons is up 47% over the past three months and has risen 24% in the last five trading sessions.
The company has kept buying. Bending Spoons recently finished its all-cash purchase of Airtable, its first big deal since the Nasdaq listing, bringing on a workflow tool used by more than 500,000 organizations. The firm has also agreed to buy Miro for an enterprise value of $1.36 billion (about $1.79 billion equity value including net cash), with some Miro shareholders putting $295 million of their proceeds back into new Bending Spoons shares.
Wall Street’s Divided View on BSP Stock
Bending Spoons is due to report Q3 results on Nov. 12. Analysts currently expect $0.26 in EPS for the September quarter. For full-year fiscal 2026, the average estimate is $1.36, which would be a 127% YOY rise from the $0.60 the company made last year.
Goldman Sachs analyst Eric Sheridan was an early voice for BSP stock. Sheridan has a “Buy” rating and a $50 price target, pointing to the company's ability to keep growing through acquisitions. The analyst also thinks artificial intelligence (AI) could open up more targets and make the platform more valuable.
Not everyone is as bullish. Bank of America is more careful, offering an “Underperform” rating and a price target of $36. Analyst Omar Dessouky cited worries about the company not having enough extra debt capacity to keep buying at the pace some valuations seem to bake in.
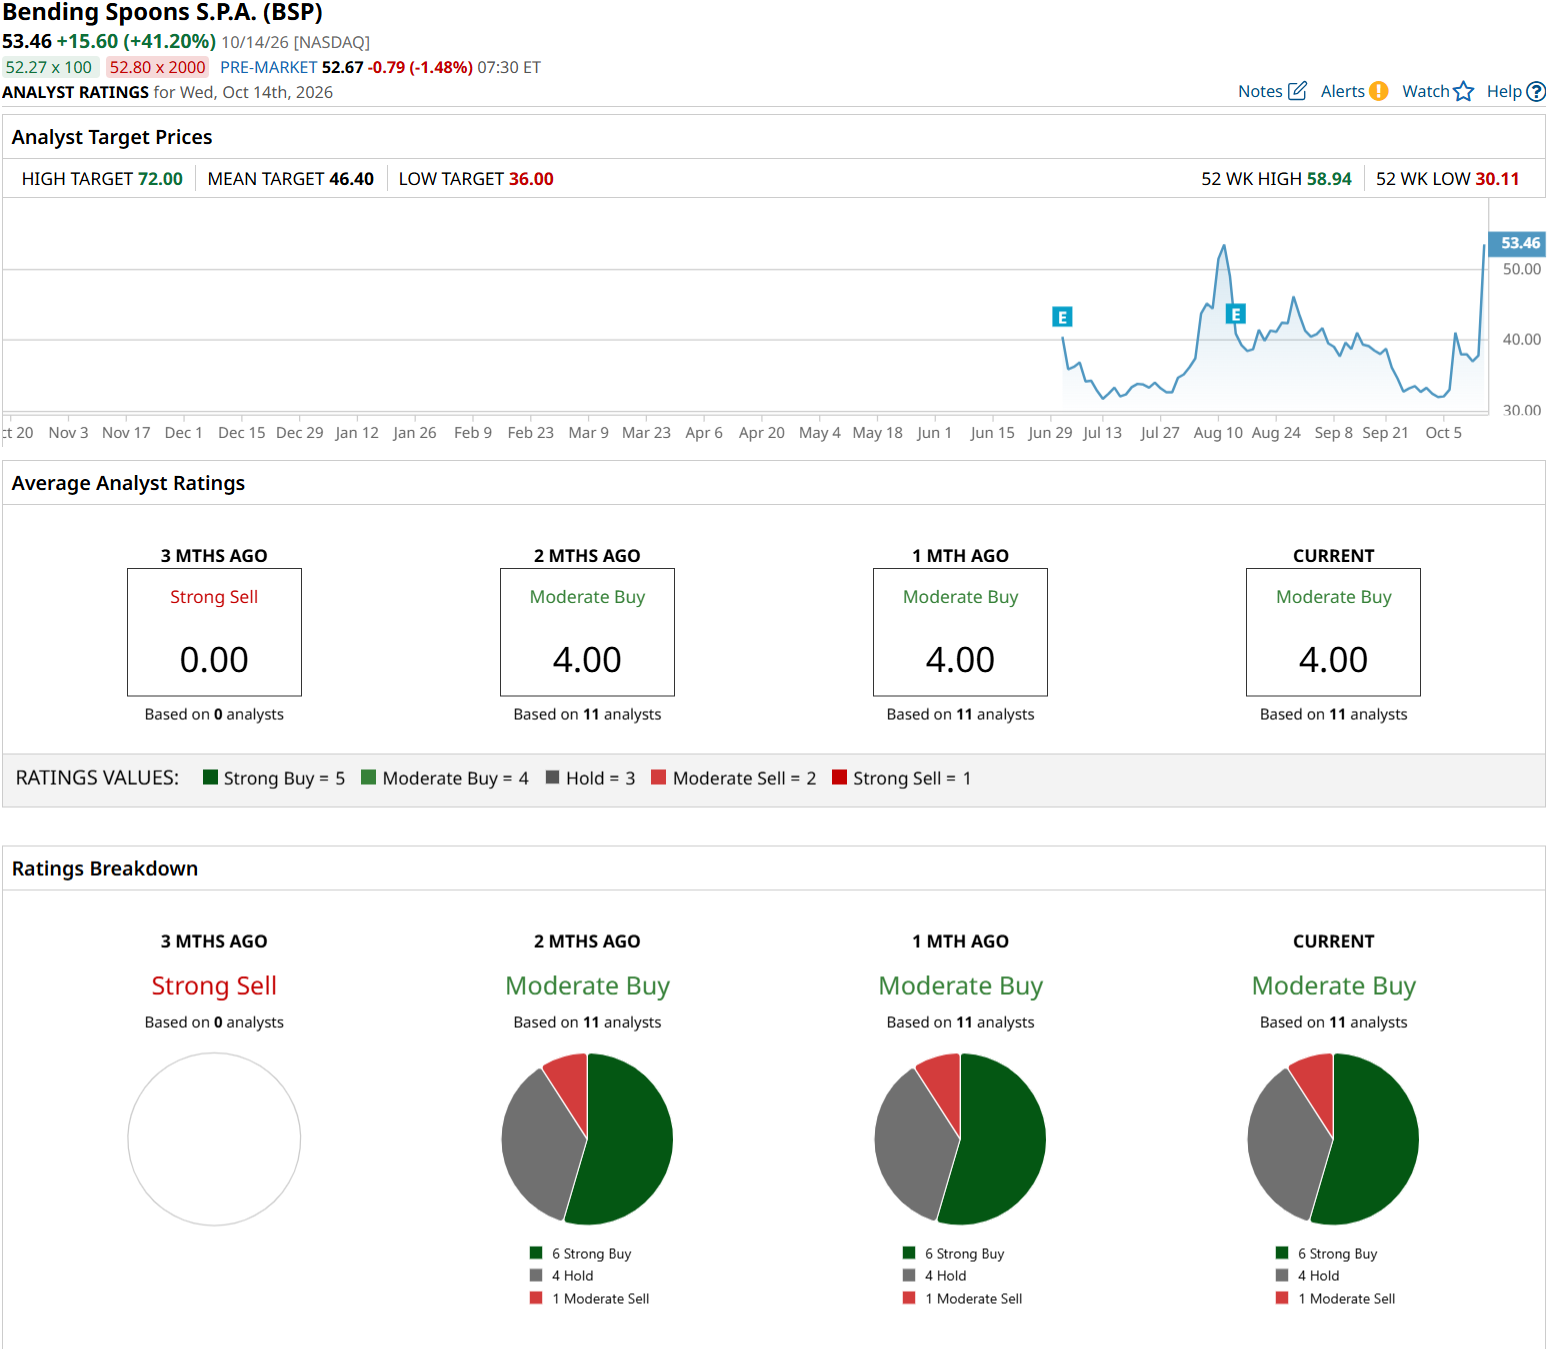
Based on 11 analysts covering the stock, Bending Spoons has a consensus “Moderate Buy” rating. The average price target of $46.40 sits just below current price levels near $47 per share, while the high price target of $72 suggests potential upside of 53% from here.
Conclusion
Berkshire’s decision to lift its stake to 4% so soon after the IPO is a clear vote of confidence in Bending Spoons’ acquisition-driven model. The fresh capital strengthens the balance sheet just as the company integrates Airtable and prepares for Miro, while the sharp stock reaction shows investors are paying attention. Still, Wall Street remains split on valuation and debt capacity. Given the strong Q2 numbers, continued deal activity, and Berkshire’s willingness to add capital at $33 per share, BSP stock looks more likely to grind higher over the next several quarters than to reverse the recent gains, provided execution stays on track.
On the date of publication, Ebube Jones did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.