
Williams Companies (WMB) Tests Its Valuation On Pipeline Spending And LNG Growth Plans
Recent commentary on Williams Companies (WMB) has focused on its capital spending plans and its stated aim for more than 11% EBITDA growth through 2030, tied to new pipelines and expected LNG demand.
At a share price of $71.28, Williams Companies has seen short term momentum fade a little with the share price return down over the past month and quarter, even as the year to date share price return of 17.14% and a 1 year total shareholder return of 17.60% keep the longer trend positive. That sits alongside a very large 3 year total shareholder return of about 13x and a 5 year total shareholder return of more than 20x, which helps explain why fresh capital spending plans and LNG linked growth commentary can move the price on any given day as investors reassess both upside potential and risk.
Compare Williams Companies' growth push and capital spend with a curated set of peers by scanning the 42 power grid technology and infrastructure stocks that is positioned to benefit from large scale energy infrastructure build outs.
Williams Companies now trades well below the average analyst target and even further below some intrinsic value estimates, after a long run in the share price. Where does fair value really sit inside that spread?
Most Popular Narrative: 17% Undervalued
On the most followed view, Williams Companies screens below an $85.61 fair value estimate at a $71.28 last close, which puts the spotlight firmly on how long term contracted projects might support that gap.
The Power Innovation platform, backed by a US$5.34b equity funding commitment from partners, is supporting a series of behind the meter projects such as Socrates and Neo that carry multi year contracts, which can add incremental contracted earnings and improve overall returns on invested capital.
The commercialization of Neo, a 682 MW behind the meter power project with a 12.5 year contract and an expected build multiple of about 5x, together with continued phases of Socrates, provides Williams Companies with a growing base of long duration power cash flows that can support EBITDA growth beyond the traditional pipeline business.
See why 29 investors see Williams Companies as 17% undervalued.
Result: Fair Value of $85.61 (UNDERVALUED)
Still, the Williams Companies story can break if permitting setbacks delay key projects or if expected LNG-driven gas flows fail to materialize at scale.
Find out about the key risks to this Williams Companies narrative.
Another View: Williams Companies Through The P/E Lens
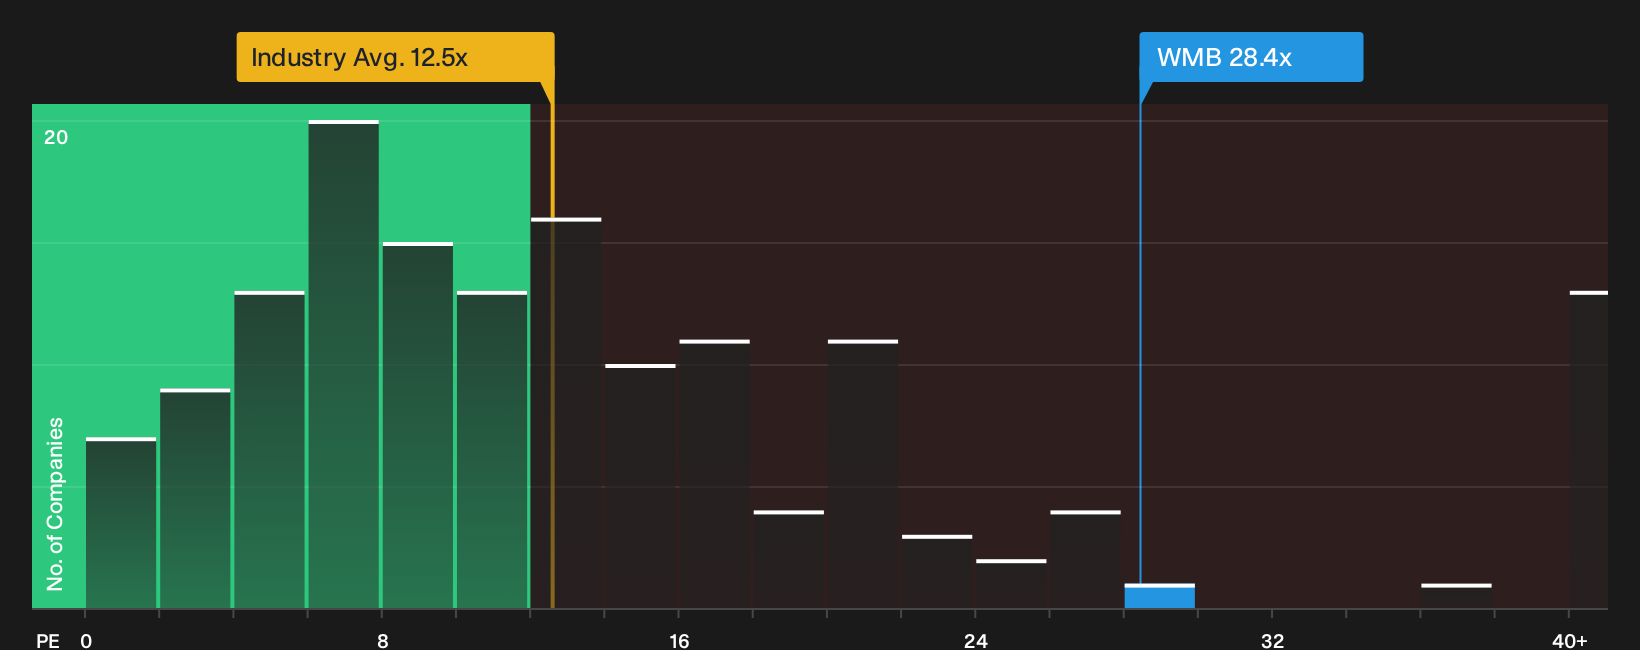
The DCF work suggests Williams Companies looks inexpensive, yet the market is already paying 28.4x earnings. That is well above both the peer average of 15.4x and an estimated fair ratio of 23.5x, which points to valuation risk if expectations cool.
For a closer look at what this richer P/E could imply over time, see See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed feelings about Williams Companies after all that. If you want to move quickly and decide for yourself, start by weighing its 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Williams Companies?
If Williams Companies has sharpened your focus on valuation and risk, broaden your watchlist with a few targeted screens that surface very different types of opportunities.
- Target value potential by reviewing a curated 33 high quality undervalued stocks that combine strong fundamentals with prices that may sit below underlying business quality.
- Strengthen your income stream by scanning a hand picked group of 8 dividend fortresses built around resilient cash generation.
- Dial back portfolio stress by filtering for 32 resilient stocks with low risk scores that score well on stability and downside protection so you are not scrambling after the fact.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com