
Mailing Tech Launch Could Be A Big Test For Pitney Bowes Stock
- Pitney Bowes introduced the SendPro CX Series in October 2026, a new line of mailing and shipping devices built on customer feedback, designed to simplify mail and package processing for offices and mailrooms, and to integrate with the Shipping 360 platform for centralized oversight.
- The CX Series connects Pitney Bowes' long-standing postage accuracy with software-driven control of mailing activity, linking core mailing workflows more closely with its broader shipping and SaaS ecosystem.
- The next question is how Pitney Bowes' investment narrative could be affected by this SendPro CX Series initiative toward simpler, integrated workflows.
Track how Pitney Bowes fits into the wider trend toward smarter shipping workflows by scanning a curated set of logistics and fulfillment specialists in our 91 robotics and automation stocks.
Pitney Bowes Investment Narrative Recap
To own Pitney Bowes, you need to believe the shift from legacy mail toward software led shipping and services can offset pressure from digitization and stiff competition. The near term story still hinges on keeping earnings growing while revenue expectations remain flat to slightly weaker and while management beds in a relatively new leadership team.
Debt is the swing factor. High leverage and upcoming refinancing needs keep financing costs and balance sheet risk in focus. The SendPro CX Series helps operationally but does not change the key near term risk, which is whether cash generation stays strong enough to support interest, reinvestment, and any capital returns.
The SendPro CX Series launch is the announcement that matters most here. It ties Pitney Bowes' postage hardware directly into Shipping 360, which aligns neatly with the broader push toward SaaS shipping, recurring software revenue, and integrated logistics tools that analysts already flag as important drivers.
For catalysts, this product line gives you something concrete to watch. Adoption trends, device placements in small offices and mailrooms, and usage flowing through Shipping 360 can all signal whether the firm is successfully defending its shrinking mail base while feeding higher margin software and services, instead of seeing that legacy side erode unchecked.
Pitney Bowes' current analyst narrative points to forecast revenue of US$1.8b and projected earnings of US$285.9m by 2029, built on the assumption of relatively flat top line performance, profit margins rising from 10.0% today to 15.7%, and an earnings step up of about US$98.6m from current earnings of US$187.3m.
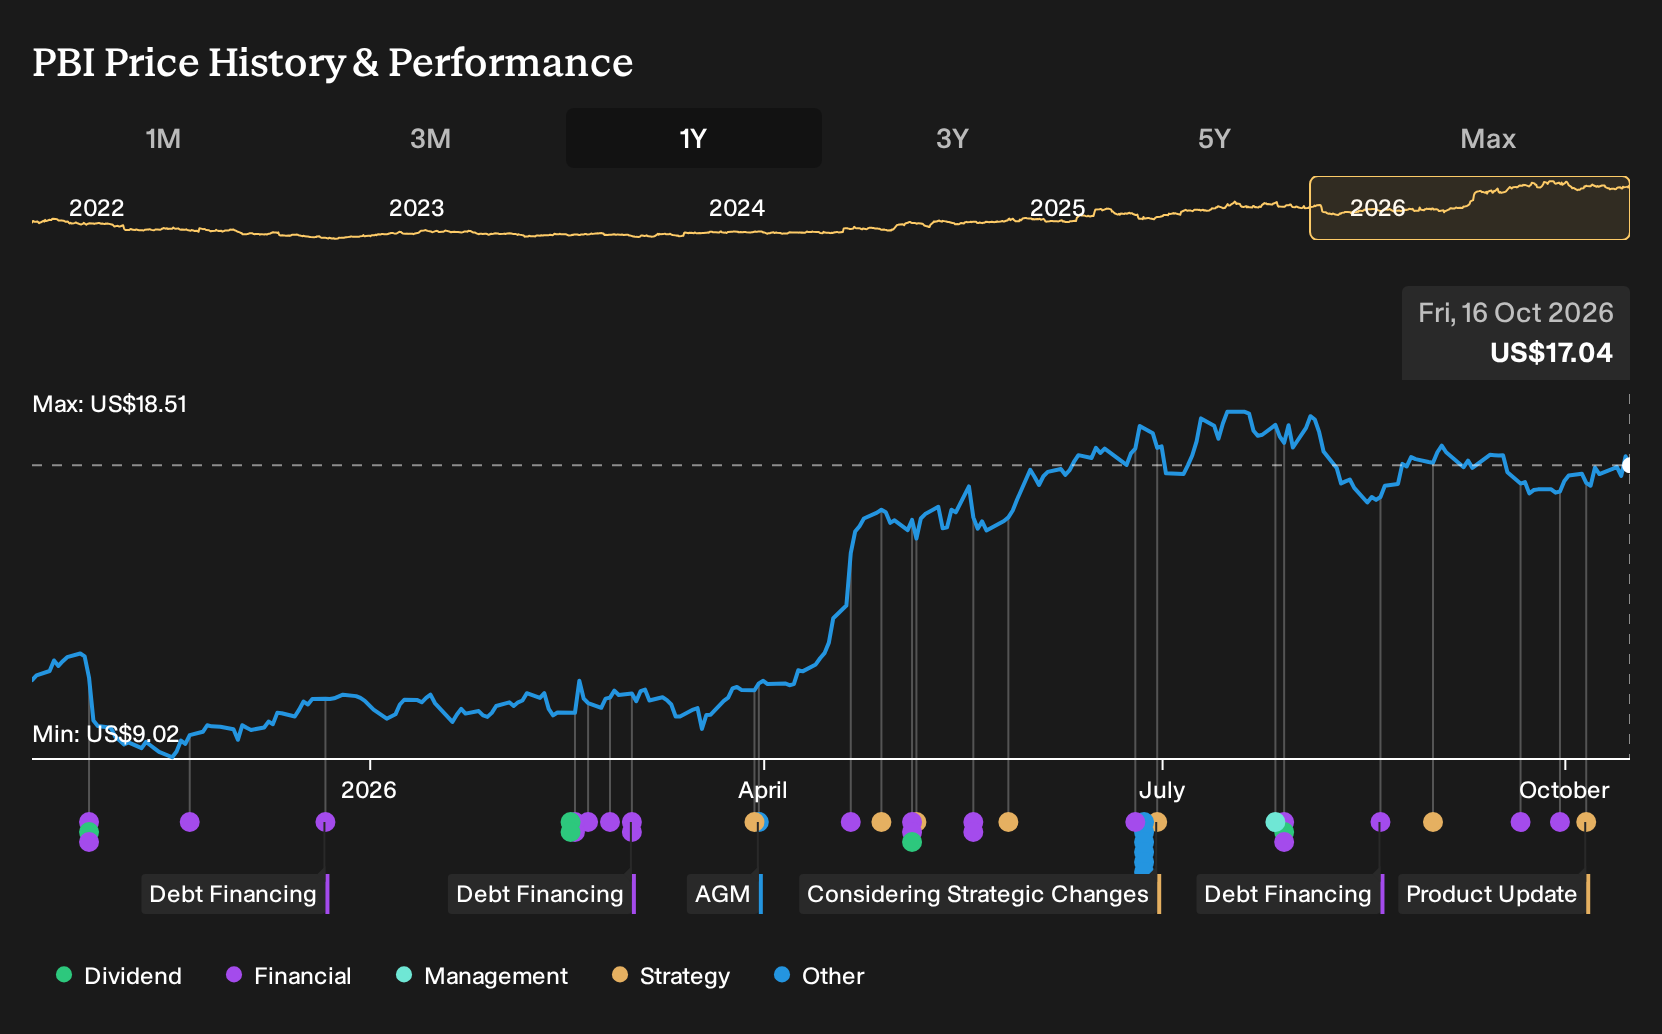
Uncover why Pitney Bowes' fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on revenue pressure. The lowest Pitney Bowes analysts were already penciling in a 2.3% annual decline, with revenue around US$1.7b and earnings of US$277.3m by 2029. That group effectively priced in only US$17.3 per share. The new SendPro CX Series could eventually nudge those expectations, in either direction.
Explore 3 other Pitney Bowes fair value estimates, including one that suggests up to 15% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pitney Bowes research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Pitney Bowes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pitney Bowes' overall financial health at a glance.
Looking For More Investment Ideas Beyond Pitney Bowes?
If Pitney Bowes has you thinking about where to deploy your next dollar, it can help to line it up against a wider field of opportunities that share some of the qualities you care about most.
- For investors who care about quality at a sensible entry point, scan a curated pool of 33 high quality undervalued stocks that already clear basic fundamental checks.
- If resilience and balance sheet strength matter most to you, focus on companies in our 32 resilient stocks with low risk scores that aim to keep risk scores in check.
- When you want to go off the beaten path and look beyond the usual tickers, tap into a focused collection of 20 high quality undiscovered gems with underlying fundamentals to investigate.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com