
Exelixis (EXEL) Could Be 13% Overvalued As Pipeline Optimism Builds
Exelixis (EXEL) has drawn fresh attention after recent trading left the stock at US$62.23. Investors are weighing that current price against the biotech group's cancer drug portfolio and its cash generating commercial therapies.
Recent trading tells a mixed story. Exelixis has eased around 1% on a 1-day share price basis. However, the 7-day and 30-day share price returns of 3.96% and 6.63% point to building momentum on top of a 42.79% year to date share price gain, while the 1-year and 5-year total shareholder returns of 58.55% and 190.79% keep the longer term picture firmly in focus.
Scan Exelixis alongside other oncology-focused businesses showing strong recent momentum with the hand picked 20 high quality undiscovered gems list.
After that kind of run in Exelixis, the real tension now sits in the trade off between potential upside from its oncology pipeline and the risk that investors are already paying full price.
Most Popular Narrative: 13% Overvalued
On Simply Wall St's central narrative, Exelixis carries a fair value estimate of $54.87 against the recent $62.23 close. This leaves the story framed around whether current enthusiasm is running ahead of the numbers or not.
The main execution priority is turning CABOMETYX’s current multi billion dollar run rate and the planned zanzalintinib launches in GI and GU oncology into durable, multi franchise cash generation before the cabozantinib patent cliff early in the next decade. The current view that Exelixis is fairly valued and bullish implies the share price already reflects a strong CABOMETYX cash engine, successful zanzalintinib approvals across key indications, and disciplined R&D and buyback-driven capital returns, without assigning much premium for additional potential beyond these elements.
See why 75 investors see Exelixis as 13% overvalued.
Result: Fair Value of $54.87 (OVERVALUED)
Still, the early 2030 cabozantinib patent window and slower than expected CABOMETYX NET uptake, along with ongoing securities investigations, could quickly challenge that upbeat Exelixis narrative.
Find out about the key risks to this Exelixis narrative.
Another View: Cash Flow Signals A Different Exelixis Story
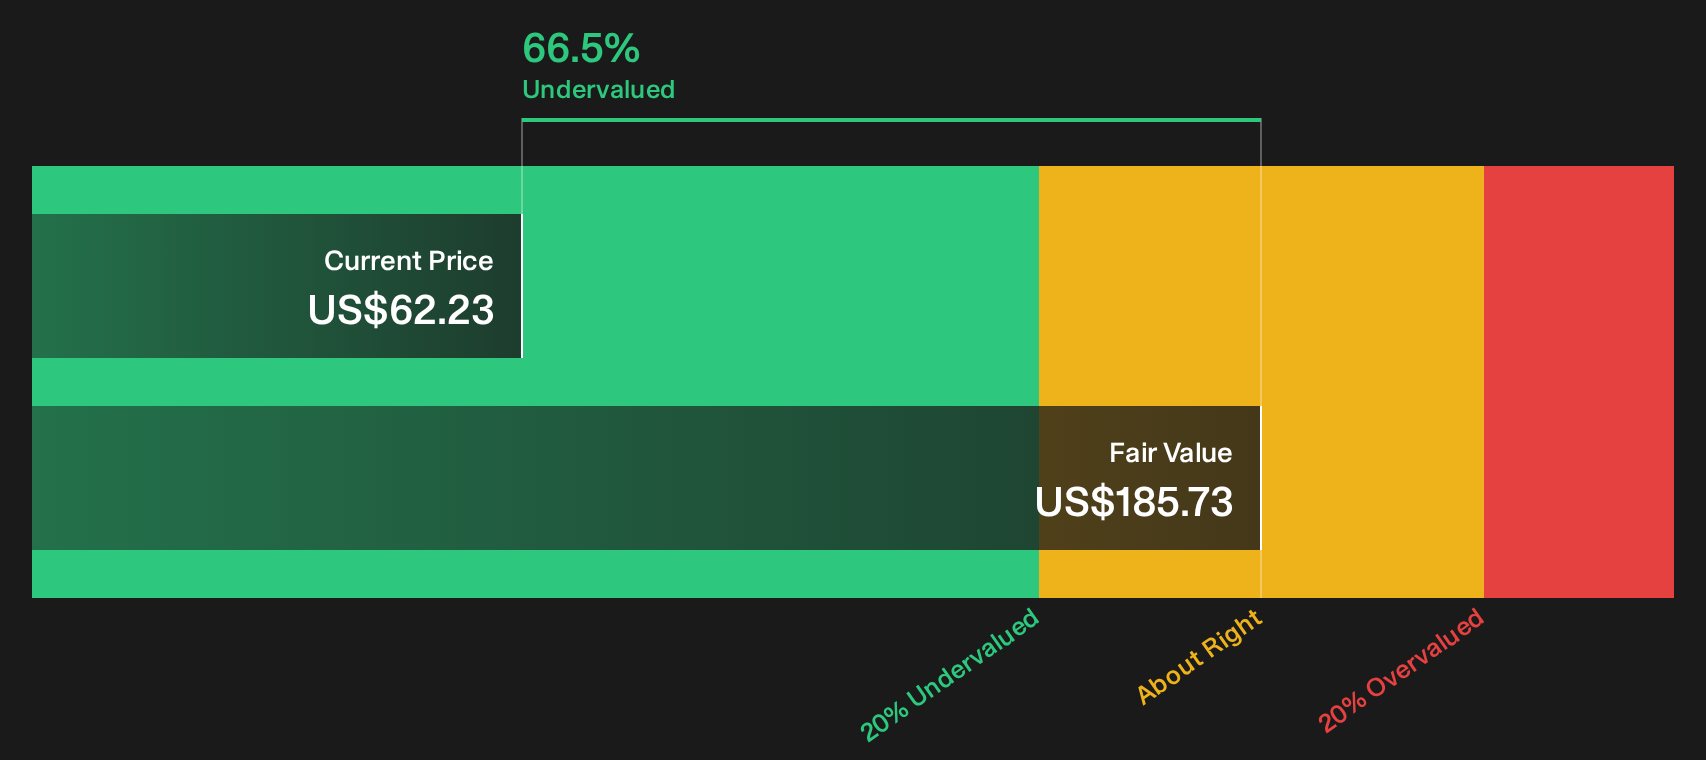
While the analyst fair value for Exelixis sits at $54.87 and frames the stock as 13% overvalued, the SWS DCF model points in the opposite direction. In that framework, EXEL at $62.23 is trading well below an estimated future cash flow value of $185.73, which raises a very different question about upside and risk.
That kind of gap invites a closer look at how sensitive any cash flow model is to assumptions on CABOMETYX, zanzalintinib and the timing of generic pressure, before you lean on it too heavily as a guide for your own decision making. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Exelixis for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed messages on Exelixis leave you torn, treat that as a cue to move quickly and stress test the numbers yourself from every angle. To see which potential upsides analysts are highlighting, review the 3 key rewards
Looking for more investment ideas beyond Exelixis?
If Exelixis has sharpened your focus, do not stop here. Broaden your watchlist with fresh ideas sourced from focused screeners built to surface targeted opportunities.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that filter for financial strength and cleaner risk profiles.
- Hunt for quality at appealing prices by reviewing the 33 high quality undervalued stocks that highlight stocks combining solid cash flows with compressed valuation multiples.
- Lock in potential income ideas by checking the 8 dividend fortresses that point to higher yielding payouts backed by more durable businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com