
Is Technip Energies (ENXTPA:TE) A Bargain After Its HPCL Contract Win?
Technip Energies (ENXTPA:TE) has secured a large Engineering, Procurement and Construction contract from Hindustan Petroleum Corporation for the Lube Modernization and Bottom Upgradation project at HPCL’s Mumbai Refinery in India.
The HPCL win lands at a time when Technip Energies’ share price has gained 6.3% over the past week and 6.5% over the past month, yet is still down 8% over 90 days and 5.1% year to date, while the 1 year total shareholder return has declined 14.1% but remains strongly positive over 3 and 5 years. This suggests that shorter term momentum is rebuilding after a weaker spell and that sentiment is still being shaped by longer running gains.
Scan for other project-driven energy contractors showing similar order momentum to Technip Energies, with the hand-picked 42 power grid technology and infrastructure stocks in focus.
Bulls see Technip Energies’ new HPCL award and long term returns as proof the current discount is a mispricing. Bears point to the recent share price slide. Which side does today’s valuation support?
Most Popular Narrative: 21% Undervalued
Against a last close of €30.98, the most followed narrative puts Technip Energies’ fair value at €39.44. This frames today’s price as a discount that depends on how its backlog, margins and cash are converted into future earnings under a 7.54% discount rate.
Very strong recent order intake of €12.7b in the first half of 2026 and a record €25b backlog, around three times full year revenue, point to Technip Energies still having a large volume of LNG and energy infrastructure projects to execute. This can feed revenue and earnings over multiple years once converted.
See why 24 investors see Technip Energies as 21% undervalued.
Result: Fair Value of €39.44 (UNDERVALUED)
Still, if Middle East disruption costs linger and higher corporate and tax expenses bite, the bullish Technip Energies backlog story could start to look stretched.
Find out about the key risks to this Technip Energies narrative.
Another View: Technip Energies On Earnings Multiples
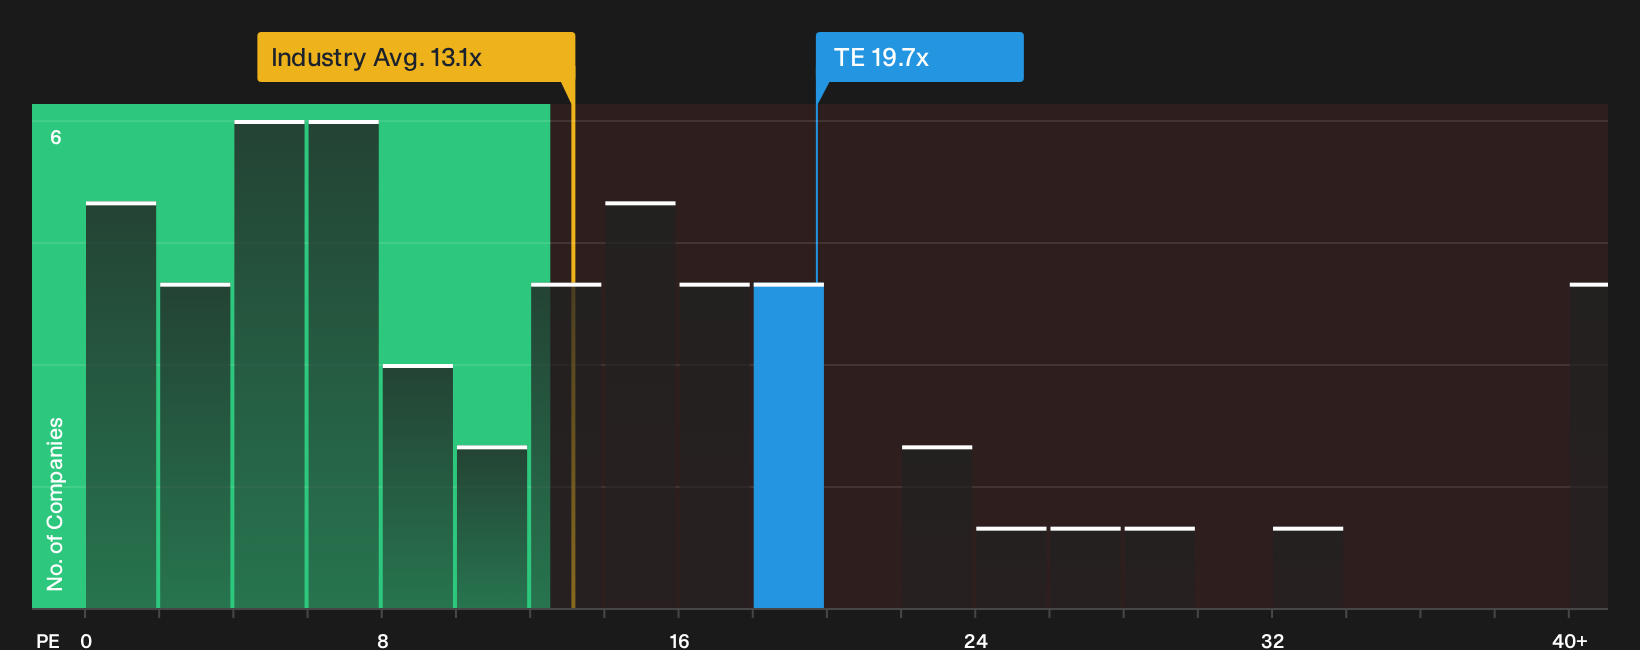
There is a catch. On a P/E basis, Technip Energies trades at 19.7x compared with 13.1x for the European energy services group and 11.7x for its peer set, while the fair ratio is 17.7x. That premium suggests less margin for error if the bullish backlog story wobbles.
To see how that compares with cash flow based estimates, look at how valuation shifts when earnings multiples compress or expand over time, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Technip Energies so far, right? Focus on the numbers instead of the noise and stress test both sides through our overview of 3 key rewards and 1 important warning sign.
Looking for more Technip Energies sized investment ideas?
If you stop with Technip Energies, you risk missing other opportunities that fit your style. Put the Simply Wall Street Screener to work for you today.
- Target resilient compounding potential by running through a tight shortlist of quality companies with strong cash and balance sheets using the list of solid balance sheet and fundamentals (203 results).
- Spot mispriced opportunities early by filtering for financially strong businesses that still trade at a discount through the 189 high quality undervalued stocks.
- Lock in portfolio ballast by focusing on stocks that combine higher yields with staying power using the 215 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com