
Does Earnings Sustainability Debate Change The Bull Case For VTech Holdings (SEHK:303)?
- Vtech Holdings has drawn attention as investors reassess whether its earnings profile supports the current valuation, especially given its lower P/E relative to other communications stocks.
- The core debate focuses on how global expansion efforts and margin optimization plans intersect with questions about the durability of Vtech Holdings' current profit levels.
- This article examines how Vtech Holdings' investment narrative is shaped by closer scrutiny of its earnings sustainability and its discounted P/E ratio.
Compare Vtech Holdings' discounted P/E debate with a curated set of value opportunities by scanning our 189 high quality undervalued stocks, which pairs solid cash flows with stronger balance sheets.
Vtech Holdings Investment Narrative Recap
To hold Vtech Holdings, you need to believe the business can keep earning its valuation discount through resilient cash generation and decent returns on capital, even as growth expectations stay modest. The key near term swing factor is execution on manufacturing shifts and Gigaset integration, which together influence how defensible the current 12.5x P/E looks against higher sector multiples.
The biggest operational risk right now sits in margins. Relocation of production, higher wage pressure and softer pockets in toys and legacy phones could all squeeze profitability if efficiency gains lag. The recent discussion around whether earnings fully support the share price does not, on its own, change those core drivers.
With no fresh company announcements tied directly to this valuation debate, the most relevant backdrop is still Vtech Holdings' stated push to diversify beyond China based production into Malaysia, Mexico and Germany. That manufacturing shift is already central to the earnings story because it shapes exposure to tariffs, supply chain resilience and overall cost structure.
For you, the link is straightforward. Any clear update on how these newer facilities are running, whether utilization is improving and how integration of Gigaset's European footprint is tracking would speak directly to both catalysts and risks. Strong execution could support stable margins. Prolonged disruption or higher than expected costs would pressure the investment case.
Vtech Holdings' current analyst story points to revenues of $2.3b and earnings of $149.0 million by 2029, based on forecast top line growth of 3.6% per year and an earnings step up of about $14.9 million from $134.1 million today.
Uncover why Vtech Holdings' fair value indicates a 22% potential upside to its current price that may not last much longer.
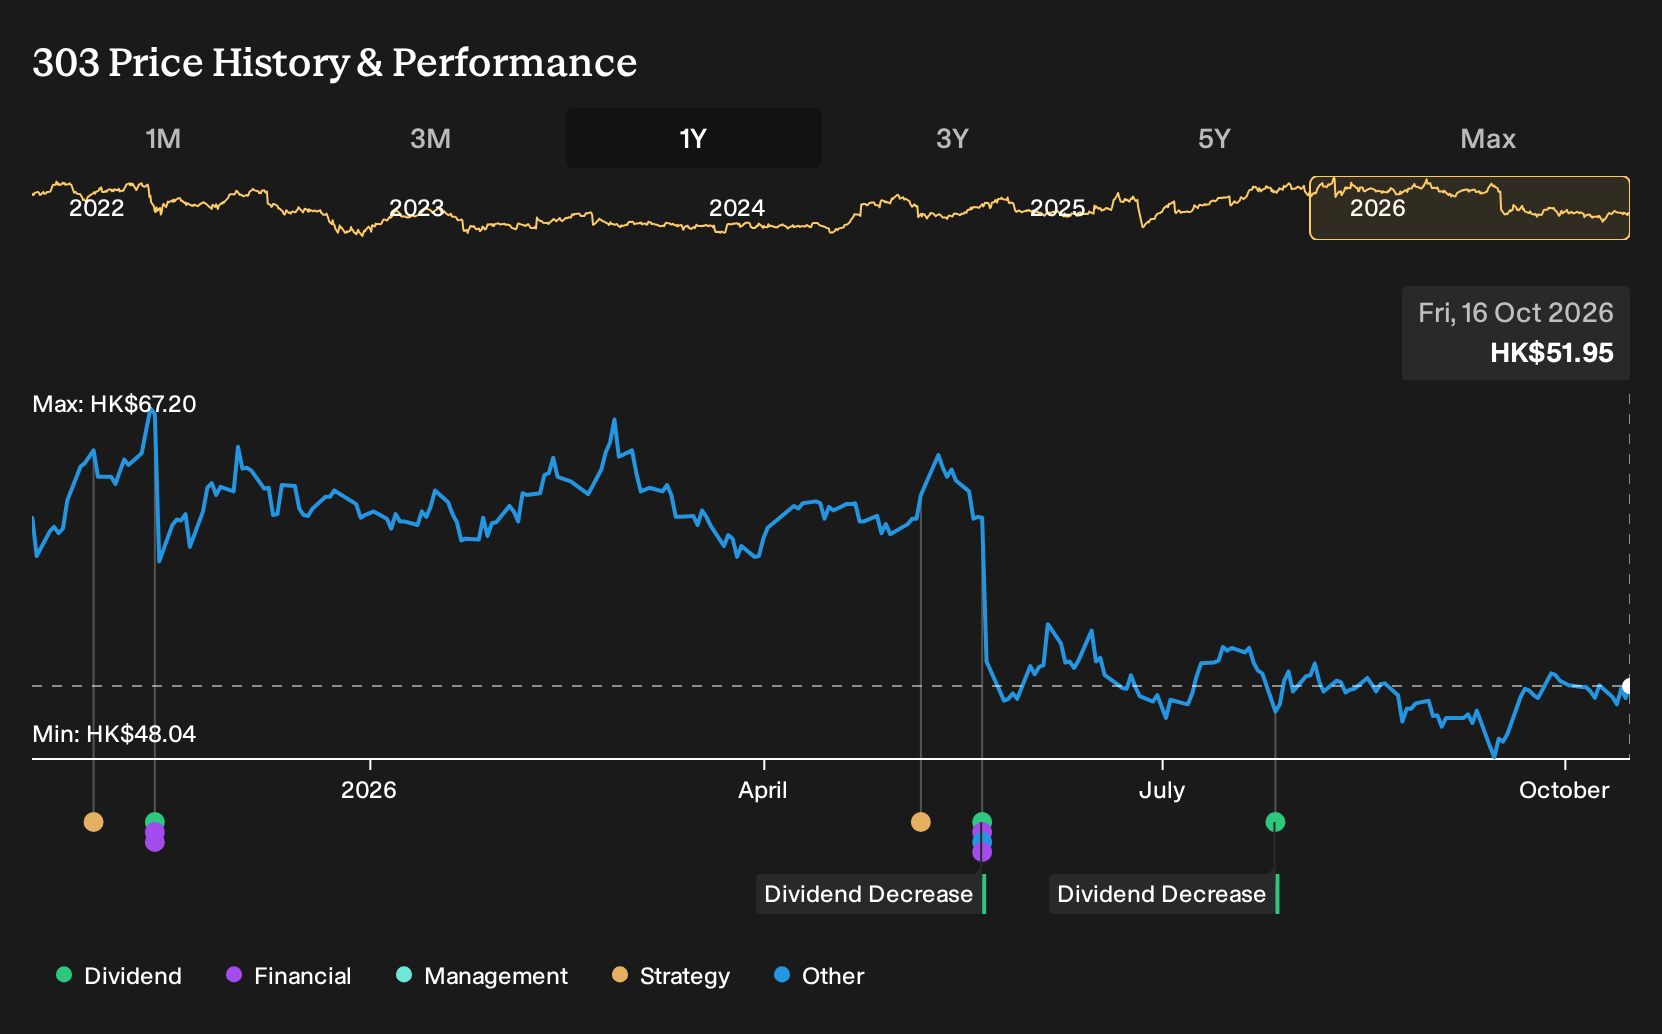
Exploring Other Perspectives
The Simply Wall St Community has only two fair value estimates for Vtech Holdings, yet they stretch from $13.70 to $63.55 per share. That span reflects how far opinions can diverge when tariffs, production relocation and Gigaset integration all sit in the mix. Use that spread to test your own thesis against competing views.
Explore another Vtech Holdings fair value estimate, including one that suggests as much as 74% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Vtech Holdings research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vtech Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vtech Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vtech Holdings?
If the valuation debate around Vtech Holdings has sharpened your appetite for opportunities, it can help to line it up next to other companies with clear fundamental stories. The Simply Wall St Screener lets you filter by quality, balance sheet strength and risk so you can build a watchlist that actually matches your investing style.
- For investors who care most about stability and want to focus on businesses with more resilient profiles, start with a 232 resilient stocks with low risk scores that may better fit a capital preservation mindset.
- If balance sheet strength is your anchor and you prefer companies with cleaner finances and robust fundamentals, scan the list of solid balance sheet and fundamentals (203 results) to see what else deserves a spot on your radar.
- When you are hunting for opportunities that the crowd may be missing and want to widen the net beyond well known stocks, check out a 614 high quality undiscovered gems that could complement your work on Vtech Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com