
Learn Why The Bull Case For Celldex Therapeutics Stock Could Change Following Shareholder Investigation
- Celldex Therapeutics recently became the subject of a shareholder investigation into past board decisions, putting its governance practices and capital allocation choices under closer scrutiny.
- The probe shines a light on how Celldex Therapeutics’ oversight and decision making could interact with heavy ongoing losses and its mast cell immunology ambitions.
- We will explore how Celldex Therapeutics’ investment narrative around barzolvolimab and a mast cell franchise may be tested by this shareholder investigation.
See how Celldex Therapeutics compares on quality and valuation by measuring it against our hand picked 33 high quality undervalued stocks, which may offer a clearer governance and pricing profile.
Celldex Therapeutics Investment Narrative Recap
To own Celldex Therapeutics, you need to be comfortable that barzolvolimab and the wider mast cell franchise can eventually justify heavy current spending, despite the business making only US$158,000 in revenue and reporting a Q2 2026 loss of US$73.5m and first half loss of US$152.19m. The key near term driver remains execution around chronic spontaneous urticaria and related indications.
The biggest operational risk is continued large losses before any commercial cash flow, which may require extra funding and further shareholder dilution. The new governance investigation does not directly change clinical data or trial timelines. However, it could influence how investors view future capital allocation and oversight quality.
There have been no fresh operational announcements directly tied to this shareholder investigation. The most relevant reference point is still Celldex Therapeutics’ prior disclosure of heavy ongoing losses alongside the barzolvolimab program. That financial profile frames why governance, board decisions and funding choices now attract closer attention.
For catalysts, the focus stays on barzolvolimab’s Phase III program in chronic spontaneous urticaria and broader mast cell indications such as symptomatic dermographism and cold urticaria, plus the early stage CDX-622 asthma work. The probe may prompt some investors to reassess how much risk they are willing to accept around further financing and long dated profitability assumptions.
Celldex Therapeutics' current analyst story lines up around revenues of US$311.0 million and earnings of US$53.6 million by 2029, built on very large implied yearly revenue growth of about 12x and an earnings swing of roughly US$354.1 million from earnings today of a US$300.5 million loss.
Discover how Celldex Therapeutics' fair value indicates a 129% potential upside to its current price that may not last much longer.
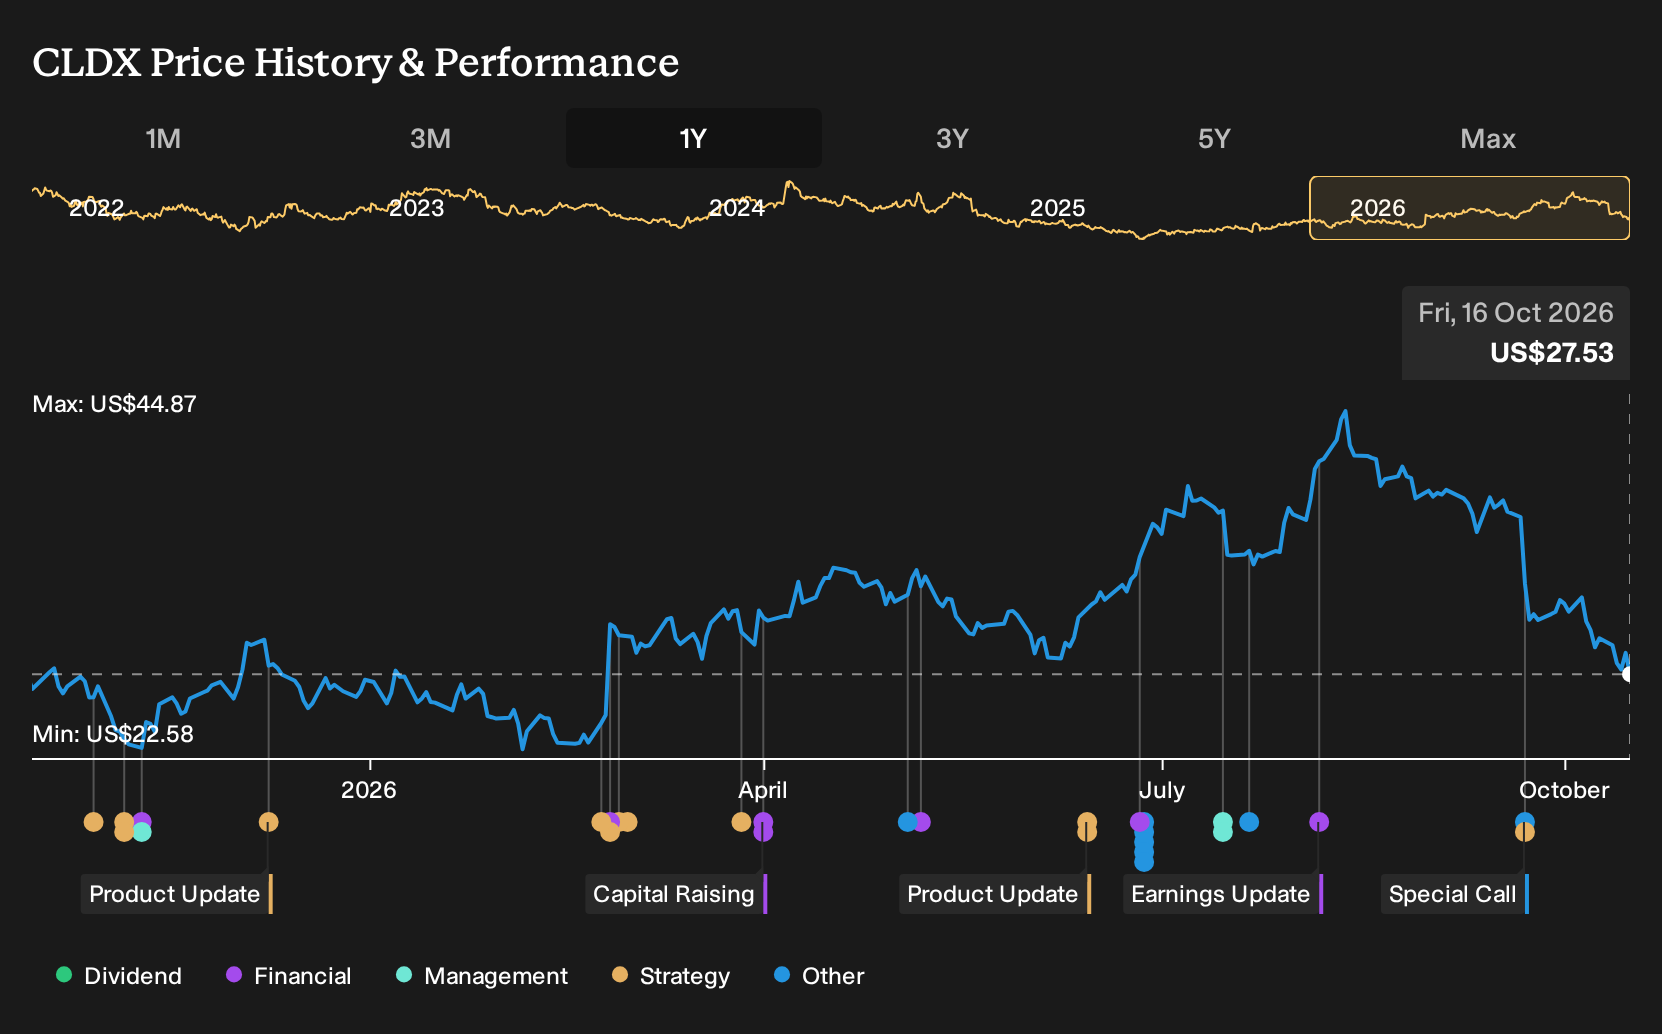
Exploring Other Perspectives
For a very different angle, focus on the bullish catalyst around longer treatment use. The most optimistic analysts were tying Celldex Therapeutics to projected 2029 revenues of about US$383.1 million and earnings near US$65.9 million before this governance probe, which may now prompt you to reassess how comfortable you feel with that optimism.
Explore 2 other Celldex Therapeutics fair value estimates, including one that suggests potential upside of up to 298% from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Celldex Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Celldex Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Celldex Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Celldex Therapeutics?
Once you have a view on Celldex Therapeutics, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If you want potential upside with strict risk controls, consider starting with 32 resilient stocks with low risk scores that focus on resilience and steadier business profiles.
- For investors who care most about balance sheet strength, filter for companies with healthier financial foundations through the list of solid balance sheet and fundamentals (25 results).
- If you are hunting for under followed opportunities with robust fundamentals, cast a wider net using the 20 high quality undiscovered gems and compare how they stack up to your thesis on Celldex Therapeutics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com