
Viking Therapeutics (VKTX) As SUNRISE Phase 3 Starts Is The Stock Fully Priced
Viking Therapeutics (VKTX) has moved into a key stage of its obesity pipeline, kicking off the SUNRISE Phase 3 program for oral VK2735 after earlier Phase 2 success and alongside fully enrolled injectable trials.
The SUNRISE launch comes after a sharp pullback, with Viking Therapeutics’ share price down 30.8% over 90 days and 28.9% year to date, even though the 3-year total shareholder return is up more than 150%. This suggests momentum has cooled as traders reassess trial risk and timing, despite a fuller late-stage VK2735 program and recent maintenance dosing and VANQUISH enrollment updates.
Scan beyond Viking Therapeutics and size up other obesity and metabolic picks in our hand picked 33 healthcare AI stocks that could be setting up their next big move.
Viking Therapeutics has a stock that has fallen hard while analyst estimates and intrinsic value models point far higher. That spread now puts the spotlight on where fair value really sits next.
Preferred Price-to-Book of 7.2x for Viking Therapeutics: Is it justified?
Valuation has swung to an expensive side of the spectrum for Viking Therapeutics, with the stock trading on a rich price-to-book ratio while the share price has already pulled back sharply.
The preferred yardstick here is P/B. That compares the market value of the equity to the accounting book value on the balance sheet. For a loss-making biotech with minimal revenue, investors often lean on this metric because traditional earnings and sales based ratios are not meaningful yet.
Viking Therapeutics is on a P/B of 7.2x, which is materially higher than both its peer group at 3.7x and the broader US biotechs cohort at 1.8x. That gap suggests the market is assigning a premium that goes beyond current financials such as net income of a $534.796m loss and effectively no revenue, and is instead concentrated on expectations around the clinical pipeline.
Compared with the sector, this valuation multiple is not just a small premium. It is more than double the US biotechs average and almost twice the direct peer mark. This points to investors paying up heavily for Viking Therapeutics’ late stage obesity and metabolic portfolio despite volatility, insider selling over the past three months, and a forecast for the business to remain unprofitable with no revenue next year.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 7.2x (OVERVALUED)
Still, the story can change quickly if Viking Therapeutics faces trial setbacks on VK2735 or requires more equity funding than expected to keep programs running.
Find out about the key risks to this Viking Therapeutics narrative.
Another View on Viking Therapeutics: Our DCF Model Paints a Harsher Picture
The market is already paying a steep P/B multiple for Viking Therapeutics, yet our DCF model lands in a very different place. On that cash flow view, VKTX at $25.17 is above an estimated future cash flow value of $8. In practical terms, the stock screens as overvalued on this second yardstick. So which signal do you treat as the anchor when expectations around VK2735 and the wider pipeline are this stretched?
Look into how the SWS DCF model arrives at its fair value.
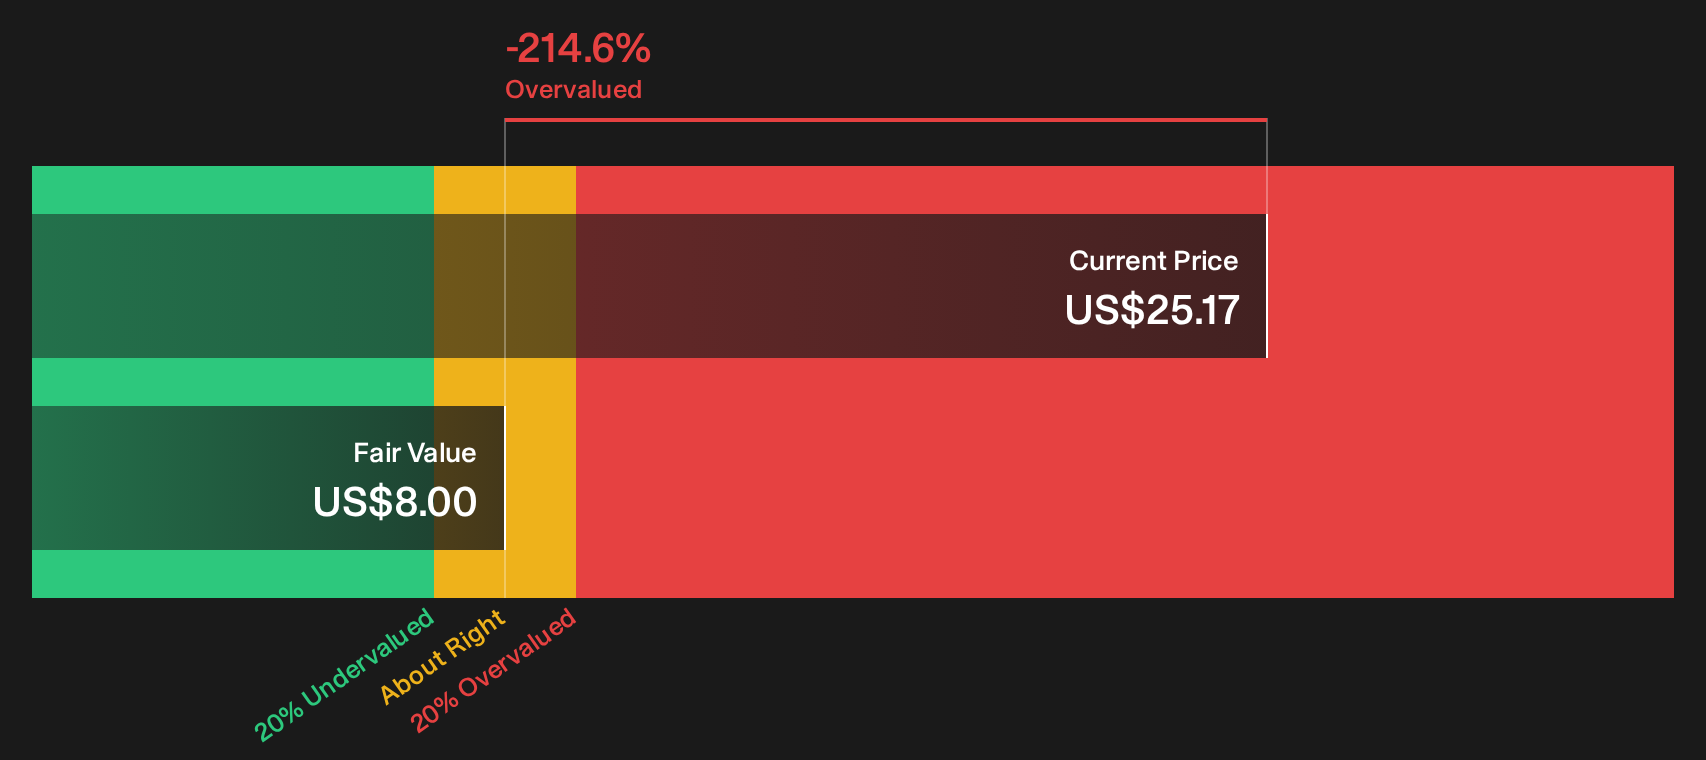
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Viking Therapeutics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
After a run of sharp moves and mixed valuation signals around Viking Therapeutics, the real edge comes from testing the numbers yourself and not relying on any single model. If you want to pressure test the downside as well as the upside, start with the 4 important warning signs.
Looking for more investment ideas beyond Viking Therapeutics?
If Viking Therapeutics has sharpened your focus on risk and reward, do not stop here. Use fresh screens to spot the next opportunity worth your attention.
- Target potential bargains early and review a curated 20 high quality undiscovered gems that filters for quality fundamentals before wider attention catches up.
- Prioritise resilience first and scan a 32 resilient stocks with low risk scores that focuses on businesses with lower risk scores and steadier financial profiles.
- Anchor your shortlist in financial strength by checking a list of solid balance sheet and fundamentals (25 results) that highlights companies with sturdy balance sheets and sound fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com