
Missed Out On Saputo's Run? Here's The Bet Holders Made
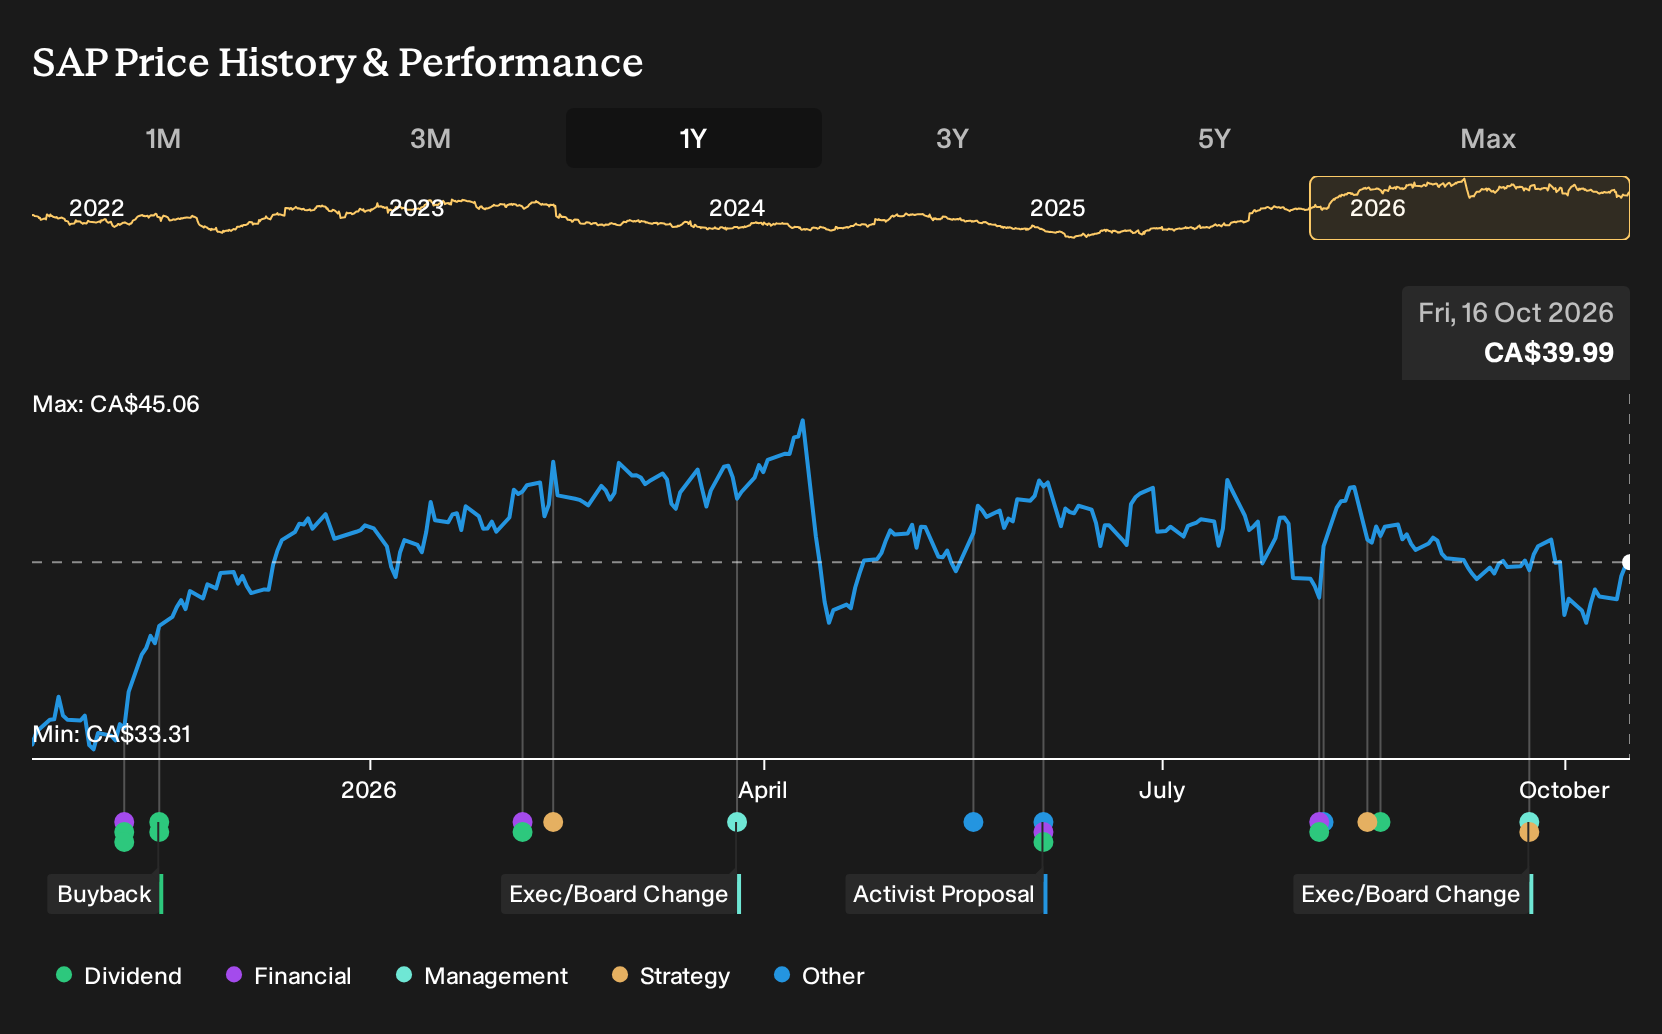
If you followed Saputo headlines over the past year, the surprise was not another efficiency target or a new ingredients focus but a signed deal to sell the UK dairy arm to Lactalis for about £988 million and a plan to sharpen the portfolio. Holding Saputo over the past year would have returned 20.1%, including dividends. If you had bought on 16 October 2025, what exactly did you need to believe before that UK sale and the Argentina stake sale were on the table?
If the move has made Saputo harder to judge, start where the gap is still open and scan 5 high quality undervalued stocks.
The Two Saputo Stories Analysts Were Arguing About
The shares cost CA$33.48 at the start of the period, and anyone looking at Saputo then was really choosing between two grounded stories about the same dairy group.
The bullish camp saw a Fair Value of CA$38, a price implied by their projections, built on revenue growth of 3.2% a year and profit margins rising from a loss to 5.0%, helped by cost savings and premium dairy demand.
The more cautious view pointed to a Fair Value of CA$27.37 and assumed only 2.3% annual revenue growth, with dairy margins pressured by plant-based alternatives and tighter environmental rules even if profitability still improved to 4.2%.
What The Saputo Evidence Actually Tested
The key development for Saputo was the agreed £988 million sale of its UK dairy arm, which supported the bullish idea that the group could reshape its portfolio and free up capital. Q1 2027 revenue of CA$4,421 million and net income of CA$183 million, with net margin at 4.1%, also pointed to the optimistic profitability story. The evidence still cut both ways.
The whole episode turned on whether margin improvement would show up in hard numbers. For any other stock with a similar debate, track net income and net margin in each set of results, and compare these figures with the specific targets used in your own growth and P/E assumptions.
What Saputo's Higher Narrative Is Asking You To Pay For Now
With Saputo trading at CA$39.99, the selected Narrative sees a Fair Value above that level and leans on higher earnings power from mix, margins and capital returns rather than broad dairy volume hopes.
For that higher figure to be reached, a buyer today would need to believe EBITDA margin improvements around the Ingredients Division and capital deployment will hold up.
"Key Takeaways: Bullish analysts expect Saputo to compound profit and margin gains from its more efficient, ingredients focused network into higher long term earnings power that the market does not fully recognize. The main thing that has to go right is that Saputo continues to execute on portfolio simplification and operational efficiencies so recent EBITDA margin improvements across Canada, the U.S., International and Europe prove durable."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking One Step Beyond Saputo
Saputo is a story about reshaping a traditional food business. You can also look sideways at what people drink.
Energy drinks target many of the same shoppers who read ingredient labels. These buyers want convenience, flavour and a claim of functional benefits.
Another consumer company leans into that demand. It sells sugar free, performance focused drinks tied to fitness and active lifestyles.
That focus on wellness positioning and distribution reach has reshaped its category. The open question is how far that preference shift spreads.
One Narrative has already put a figure on it. → Uncover the company trading 49% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com