
Rocket Lab (RKLB) Dropped, So What Is Behind The Latest Attention?
Rocket Lab (RKLB) has become a flashpoint after delaying the debut of its Neutron medium lift rocket to 2027 because of a first stage tank defect, a move that coincided with a nearly 7% drop in its share price.
The Neutron delay lands on top of a tough tape for Rocket Lab. The share price has fallen 7.98% over the past day, 25.47% over the past week and 33.10% year to date, while the 1 year total shareholder return is down 23.28% even after a very large 3 year total shareholder return that is more than 10x.
That slump is unfolding alongside fresh contract wins and rising scrutiny. In 2026, Rocket Lab secured a record Synspective deal for 20 Electron launches scheduled from 2028 to 2031. Yet the stock has come under pressure as Neutron delays, a CFO share sale and weaker sentiment toward high growth names have weighed on risk appetite.
Short term momentum is fading, which signals that investors are now reassessing how Neutron execution risk, the Synspective backlog and the company’s broader launch cadence might reshape both future growth expectations and the level of volatility they are willing to tolerate in the Rocket Lab story.
Seize this pullback moment around Rocket Lab to reassess your risk bucket and compare it with hand picked 32 resilient stocks with low risk scores that may offer a smoother ride through volatility.Bulls point to Rocket Lab’s record Synspective backlog and revenue growth, while bears focus on Neutron delays and recent share weakness. Which story does the current valuation actually support next?
Most Popular Narrative: 40.2% Undervalued
On the narrative view, Rocket Lab’s recent close at $50.84 sits well below a fair value estimate of $85.04. This frames the pullback as a valuation gap rather than just a sentiment swing.
Rocket Lab is mid-transformation from a small-launch specialist into a vertically integrated space and defense prime, with Space Systems now approximately 67% of revenue and growing fastest. A $1.85B backlog (+73% YoY) anchored by the $816M SDA Tranche 3 award provides multi-year revenue visibility that the current trailing P/S of approximately 72x does not yet fully reflect.
See why 117 investors see Rocket Lab as 40% undervalued.
Result: Fair Value of $85.04 (UNDERVALUED)
Still, the Rocket Lab narrative can break if Neutron timelines slip again or if large defense customers slow contract conversion and weaken that backlog story.
Find out about the key risks to this Rocket Lab narrative.
Another View: Rocket Lab Looks Expensive On Sales
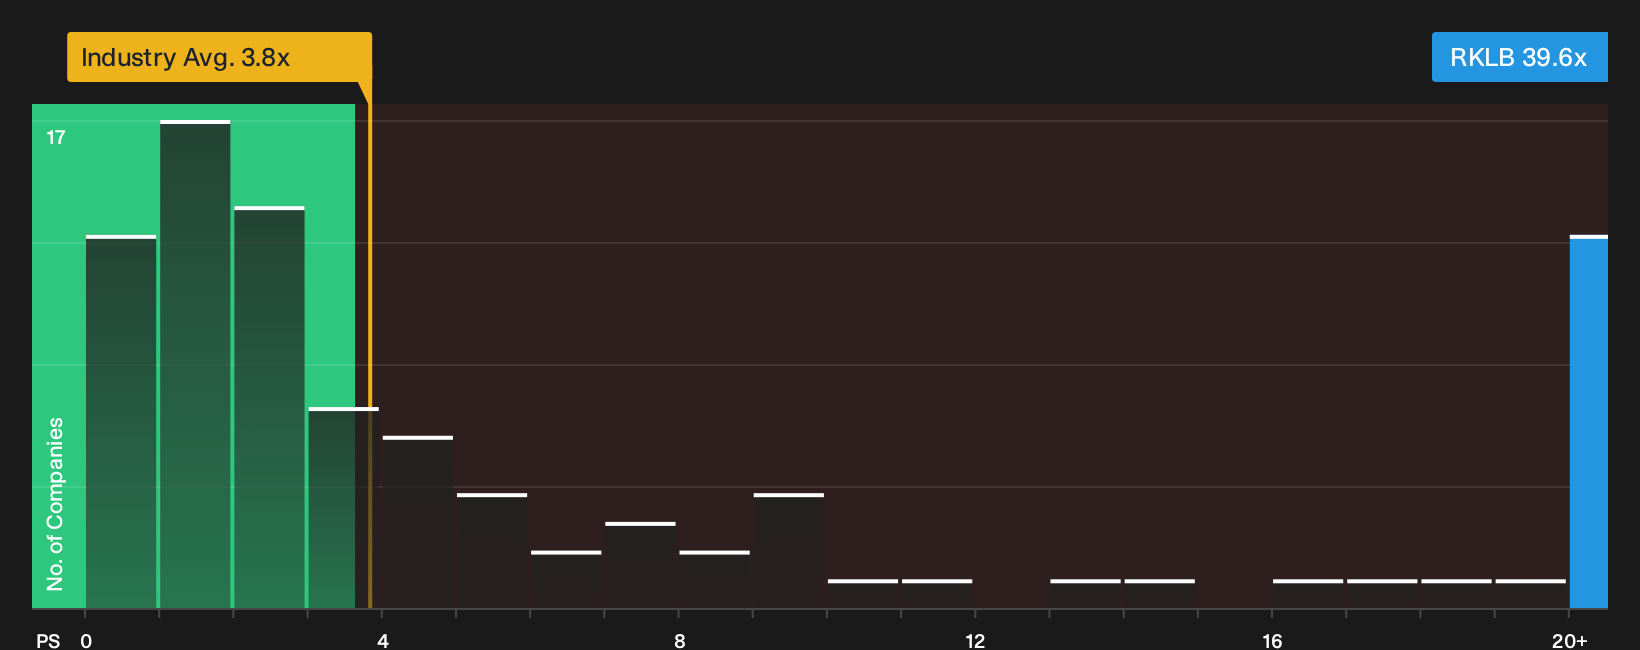
There is a very different message when you look at Rocket Lab through its P/S ratio. The stock trades at 39.6x sales, compared with 7.3x for peers and 3.8x for the wider US Aerospace & Defense group, while the fair ratio is 10.9x. That wide gap suggests the share price already bakes in a lot of optimism and leaves less room for error if the story changes.
For investors who prefer to anchor decisions on simple market multiples rather than narratives, this kind of premium can be a useful stress test for position size and risk tolerance, especially when a single project like Neutron carries so much weight in the Rocket Lab thesis. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Rocket Lab’s valuation and execution risk can pull you in opposite directions, so move quickly to check the numbers and decide where you stand by weighing its 2 key rewards and 2 important warning signs.
Looking for more Rocket Lab sized opportunities?
If Rocket Lab has you rethinking your playbook, do not stop here. Use targeted screeners to uncover fresh ideas that actually match your risk and return goals.
- Target potential mispricing by reviewing companies on the 33 high quality undervalued stocks that may trade below what their fundamentals suggest.
- Strengthen your core holdings by scanning the list of solid balance sheet and fundamentals (25 results) focused on businesses with robust financial footing.
- Hunt for future standouts by checking the 20 high quality undiscovered gems featuring under-the-radar stocks with strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com