
Should Valuation Gap Require Action From Volex (LSE:VLX) Investors?
- Volex has attracted fresh attention after a discounted cash flow review suggested its current market valuation sits well above estimated cash generation, even as the firm continues to integrate acquisitions such as Kepler SignalTek into its operations.
- The Kepler SignalTek deal deepens Volex's exposure to medical and patient connected products. This tightens the link between future execution in this segment and the sustainability of the current valuation debate.
- We will now look at how Volex's investment narrative is being reshaped by the DCF valuation gap flagged in recent analysis.
Compare Volex's valuation gap with other potential mispricings by scanning our hand picked list of 7 high quality undervalued stocks that also combine cash generation with solid balance sheets.
Volex Investment Narrative Recap
To own Volex, you need to be comfortable with a story built on execution in higher value segments like medical, EV and complex industrial assemblies, while the group continues integrating deals such as Murat Ticaret and Kepler SignalTek. The core near term catalyst is operational delivery that supports current pricing and margins against cost inflation and supply chain complexity.
The biggest risk right now is that integration work in Turkey, medical and patient connected products drags on profitability or working capital more than expected. The recent DCF work mostly affects sentiment rather than day to day trading, unless it starts to constrain management options for further projects.
Among recent developments, the Kepler SignalTek acquisition is the clearest operational hook for this valuation debate. It increases Volex exposure to medical and patient connected products, where performance often depends on quality, regulatory reliability and tight customer relationships rather than volume alone.
That purchase also concentrates execution risk around this healthcare oriented push. Delivery on medical revenues and margins now matters more for the investment case and for closing any perceived gap between cash generation and share price. If integration progresses smoothly, it could help support the current narrative around growth in higher specification connectivity.
Volex's current analyst narrative points to forecast revenue of US$1.5b and expected earnings of US$96.2 million by 2029. This rests on assumed yearly revenue growth of 7.3% and an earnings increase of about US$30 million from current earnings of US$65.8 million.
Uncover why Volex's fair value indicates a 9% potential upside to its current price that could narrow quickly.
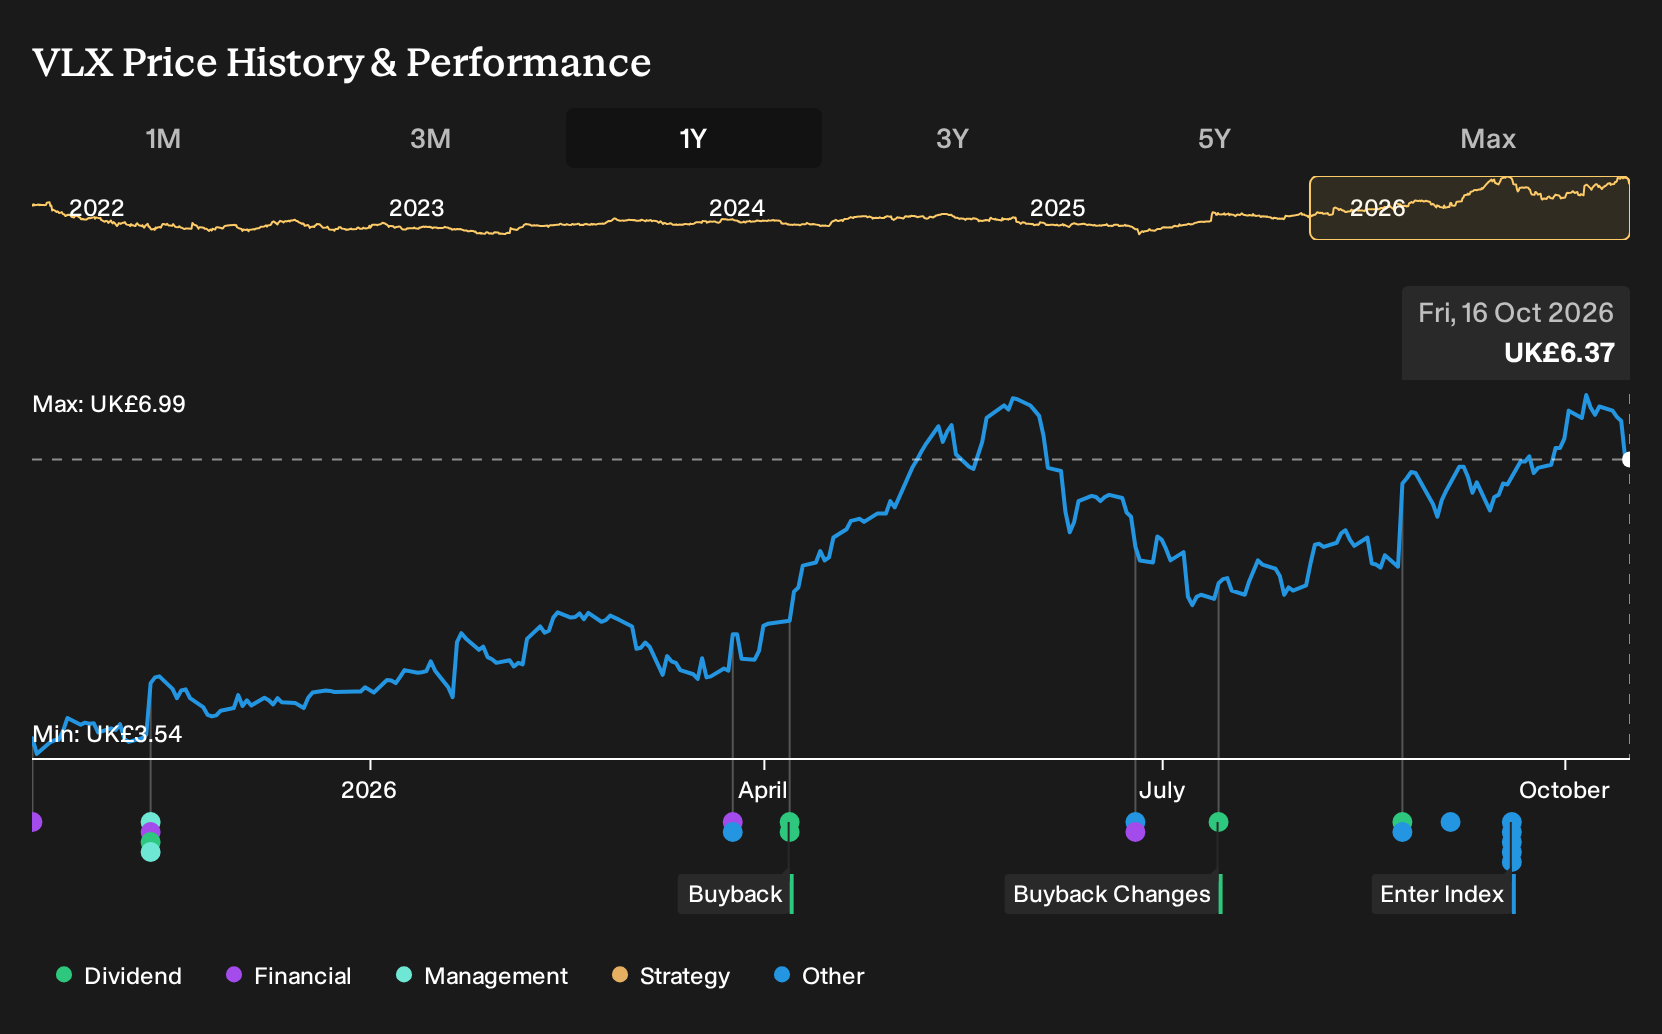
Exploring Other Perspectives
Some of the most optimistic analysts focus on data center and AI demand rather than medical exposure. They were modelling revenue of about US$1.7b and earnings near US$119.7 million by 2029, compared with the US$1.5b and US$96.2 million consensus. With the latest Volex news, those projections may change over time.
Explore 3 other Volex fair value estimates, including one that suggests as much as 32% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Volex research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Volex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Volex's overall financial health at a glance.
Looking For More Ideas Beyond Volex?
Once you have formed a view on Volex, it can help to compare that thesis with opportunities in other areas of the market using the Simply Wall St Screener.
- If you want mispriced quality with income potential, scan a hand picked group of cash generative businesses offering strong yields through the 2 dividend fortresses.
- For those who care most about resilience and capital preservation, filter for companies with lower risk profiles and sturdier fundamentals using the 4 resilient stocks with low risk scores.
- If you are hunting for overlooked potential, search for under the radar businesses with solid financials through the 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com