
Should ETF Support Win Require Action From SS&C Technologies Holdings (SSNC) Investors?
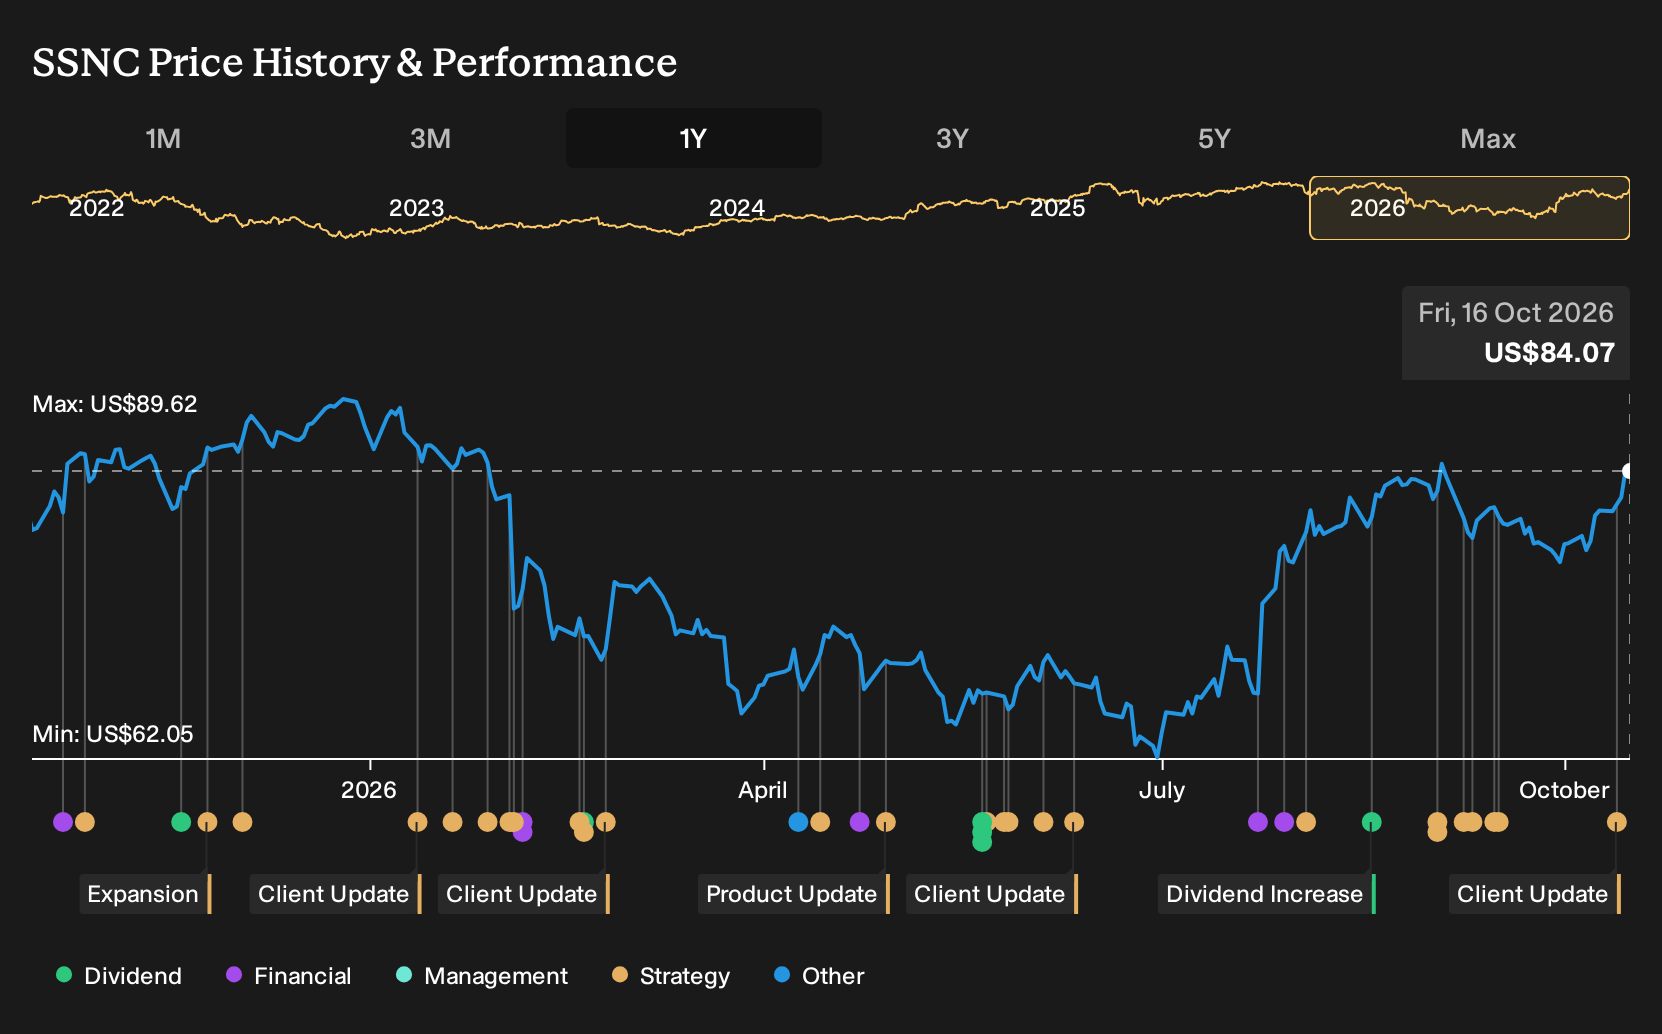
- Thornburg Investment Management announced that it selected SS&C Technologies Holdings to support ETF share class structures for two actively managed mutual funds, adding to an existing service relationship that already covers distribution, investor services, ETF distribution and transfer agency.
- The expanded ETF mandate gives SS&C Technologies Holdings deeper involvement in complex fund operations, from calculation and reconciliation to conversion processing. This underlines how its workflow tools are being used for sophisticated share class structures with more than US$860 million in associated assets.
- We will now look at how SS&C Technologies Holdings' deeper role in Thornburg's ETF share classes could influence the wider investment narrative.
Scan the operational backbone theme behind SS&C Technologies Holdings and Thornburg, then size up other fund infrastructure plays in our curated list of list of solid balance sheet and fundamentals (25 results).
SS&C Technologies Holdings Investment Narrative Recap
To own SS&C Technologies Holdings, you need to believe that its outsourced operations model remains sticky and that investments in automation can support margins even as growth expectations stay moderate. The Thornburg ETF share class work sits squarely in that story, since it uses SS&C for complex, recurring workflows rather than one off projects.
The near term swing factor still looks like execution on cost control and automation, given past pressure on operating and free cash flow margins. Thornburg’s mandate helps, but on its own it does not materially change the biggest risk, which is that expenses stay elevated while growth and valuation expectations remain high.
Among recent themes, the push into AI driven automation through platforms like Blue Prism and WorkHQ ties most closely to the Thornburg announcement. Those tools are already framed as levers to reduce operating costs and support EBITDA margin resilience when clients outsource intricate tasks such as ETF conversions, reconciliations and exception handling.
Thornburg’s ETF share class structure leans on exactly those strengths. When combined with growth areas like private markets servicing through GlobeOp and wealth solutions such as Black Diamond, the deal illustrates how successful delivery on complex mandates could act as a catalyst, while any missteps would quickly feed concerns about profitability and execution risk.
SS&C Technologies Holdings is covered by analysts who project that revenues could reach US$7.5b with earnings of US$1.3b by 2029, which lines up with a 4.6% yearly revenue growth rate and implies an earnings increase of about US$436m from current earnings of US$864.0m.
Uncover why SS&C Technologies Holdings' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community currently contributes two fair value views on SS&C Technologies Holdings, with estimates spread between about US$93.56 and US$190.92 per share. That gap shows how far opinions can stretch. Set those expectations against margin pressure risks, AI automation or international expansion catalysts, then weigh several contrasting viewpoints yourself.
Explore another SS&C Technologies Holdings fair value estimate, including one that suggests it could be worth just $93.56.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SS&C Technologies Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SS&C Technologies Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SS&C Technologies Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond SS&C Technologies Holdings?
Once you have a view on SS&C Technologies Holdings, it can help to compare that thesis with other companies that have different risk and return profiles. Use the Simply Wall St Screener to scan for stocks that fit the kind of balance sheet strength, income profile or upside potential you want to research next.
- For investors who care most about financial resilience and steady fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that keep debt and liquidity in focus.
- If you are hunting for mispriced opportunities with quality traits, cast a wider net across 33 high quality undervalued stocks that combine solid metrics with room for sentiment to shift.
- Income focused readers can scan for reliable payers by filtering for 8 dividend fortresses that pair higher yields with balance sheets you can scrutinize in detail.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com