
Adeia Stock Gets A Charter License Renewal
- Adeia announced that it renewed a multi year intellectual property license agreement with Charter Communications for Spectrum’s pay TV, video, broadband and mobility services, extending coverage across multiple business lines.
- The renewal keeps a major customer tied into Adeia’s media IP portfolio, which can help support recurring licensing income across several distribution channels.
- We will now explore how Adeia's investment narrative could be influenced by this multi year IP renewal with Charter Communications.
Scan for other media and telecom plays that are building value from recurring IP and subscription cash flows by focusing on 20 high quality undiscovered gems in this corner of the market.
Adeia Investment Narrative Recap
To own Adeia, you need to believe that a focused intellectual property platform can keep turning patents into predictable royalties, even as media and semiconductor markets change around it. The Charter renewal supports that view by keeping a key distributor tied into the media portfolio. This helps underpin near term licensing visibility rather than transform it.
The most important short term swing factor still sits in Adeia’s ability to close and renew a handful of large licenses while keeping litigation costs contained. The biggest risk remains deal timing and legal spend. Missed renewals or heavier legal outlay could matter more than this single, albeit helpful, contract extension.
The earlier multiyear media renewal with Google is the cleanest reference point for this Charter announcement. Both agreements show large distribution platforms opting to secure access to Adeia’s content delivery IP over several years. This supports the idea of a broad, long duration royalty base rather than one off settlements.
For catalysts, investors are watching how this cluster of large tech and Pay TV contracts translates into mix shift toward OTT and streaming, and how that interacts with semiconductor royalty progress. These renewals do not eliminate risks around regulation, litigation or customer concentration, but they provide additional real world evidence of customers continuing to license Adeia’s portfolio at scale.
Adeia's current earnings sit at US$122.7 million, and analysts expect this to move to US$106.8 million by 2029. This implies an earnings decline of about US$15.9 million, even as they model flat revenue and forecast revenues of US$465.5 million in that same year.
Uncover how Adeia's fair value signals a 111% potential upside to its current price before that gap narrows.
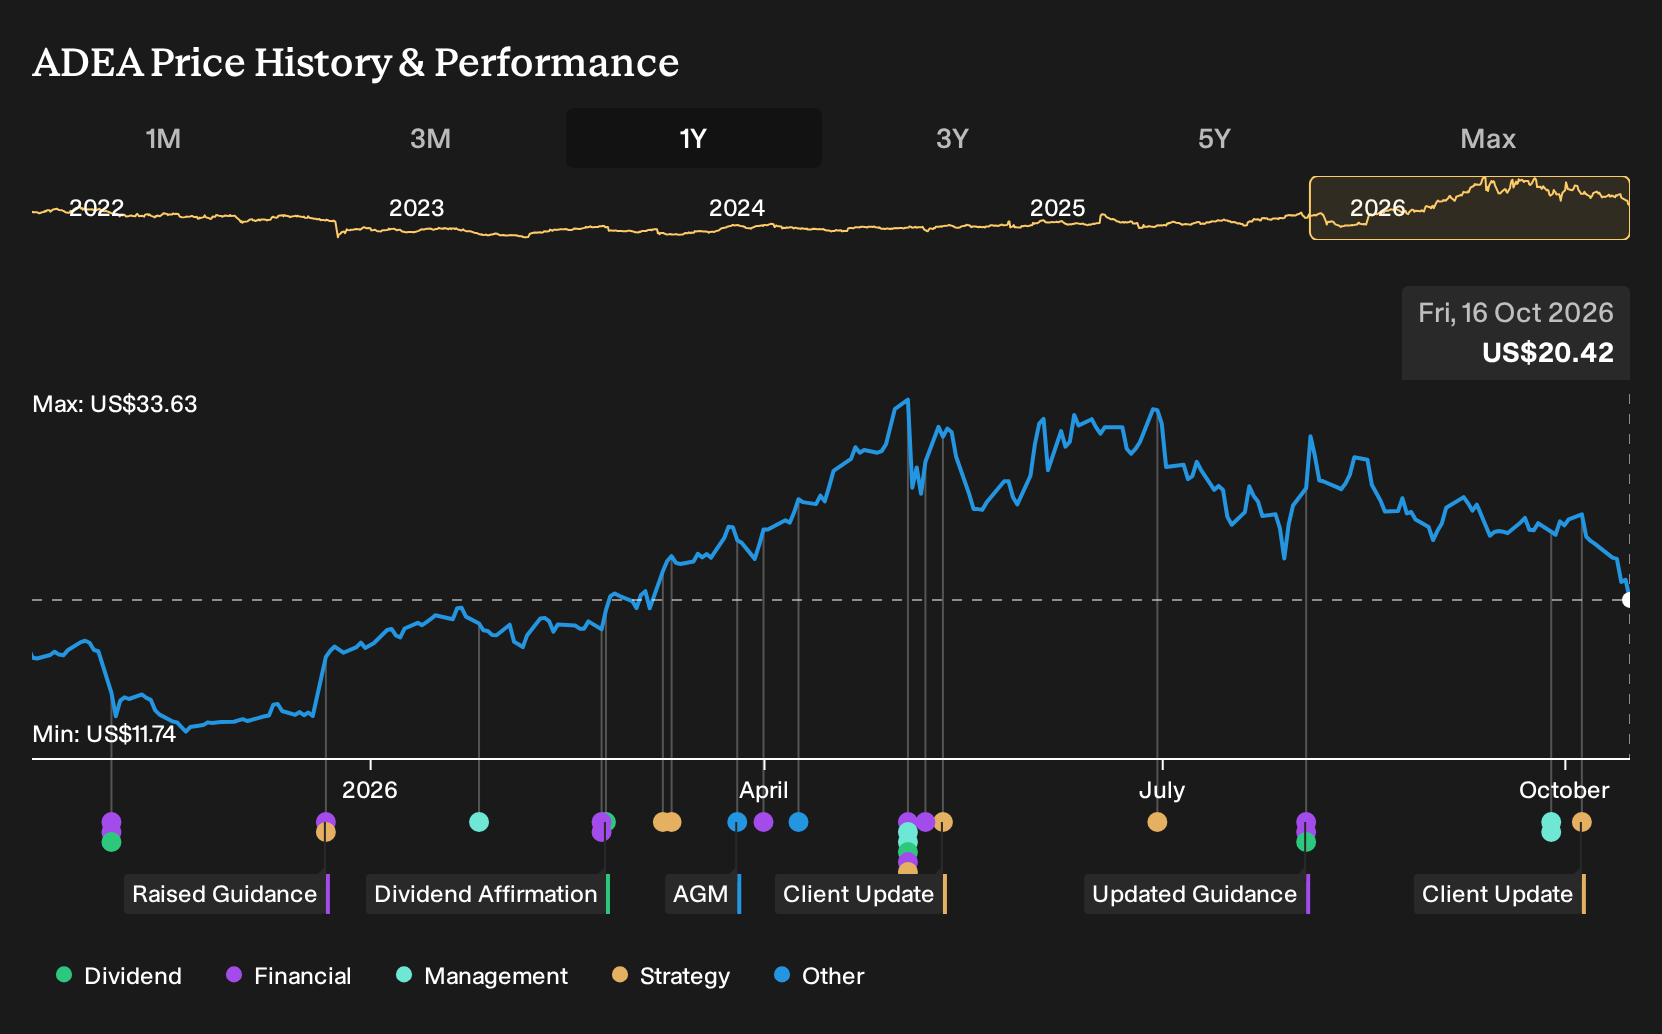
Exploring Other Perspectives
One alternate angle on Adeia focuses on contract concentration risk. The most cautious analysts feared key renewals might slip or reprice lower and were penciling in about US$476.5 million of 2029 revenue and US$112.0 million of earnings before this Charter news. That creates a more pessimistic tone. Use it as a prompt to compare multiple narratives and decide which assumptions feel more realistic to you.
Explore 4 other Adeia fair value estimates, including one that suggests as much as 6% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Adeia research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Adeia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adeia's overall financial health at a glance.
Looking for more Adeia style investment ideas?
If Adeia has you interested in recurring cash flows and resilient business models, it can help to compare it with other stocks that share different combinations of quality, value and balance sheet strength. The Simply Wall St Screener gives you a way to filter for these traits directly instead of jumping between tickers one by one.
- For investors who want income without giving up resilience, review a curated set of high yield payers by scanning 8 dividend fortresses.
- If capital preservation comes first for you, start with companies that score well on stability and financial risk by checking the 32 resilient stocks with low risk scores.
- When you are hunting for under followed opportunities with solid fundamentals, broaden your watchlist using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com