
EastGroup Properties (EGP) Adds Audit Voices, Is It Still A Bargain?
EastGroup Properties (EGP) recently expanded its board-level oversight by adding Bethany Logan Ropa and Robyn R. Werner to the Audit Committee on October 8. The stock reaction gives investors a fresh reason to reassess governance and risk controls.
At around US$196.37 a share, EastGroup Properties has seen its short term share price weaken, with the 30 day share price return down 3% and the 90 day share price return down 11%. This comes even though the year to date share price return is 9% and the 1 year total shareholder return is 11%, which hints that recent governance moves and changing risk perceptions are arriving after a strong multi year run that includes a 40% total shareholder return over three years.
Scan how EastGroup Properties compares with other real estate trusts by jumping across to our hand picked list of solid balance sheet and fundamentals (25 results) that are weathering similar governance and market pressures.
EastGroup Properties runs a focused industrial portfolio and has delivered solid longer term returns. Yet the recent pullback and fresh audit oversight raise a simple issue: Are investors paying a premium or getting fair value for that quality?
Most Popular Narrative: 14% Undervalued
On the most followed view, EastGroup Properties screens as undervalued, with a fair value estimate of $227.90 against the recent $196.37 close, so the stock is being treated as if its cash generation and asset base deserve a higher tag.
Structural demand for EastGroup Properties infill shallow bay assets in fast growing Sunbelt markets, supported by tenant comments on higher diesel costs and traffic congestion, can keep occupancy and re leasing spreads healthy. This feeds directly into rental revenue and same store NOI. Growing leasing from data center related and advanced manufacturing tenants, which accounted for roughly one quarter of development leasing in the first half of 2026, diversifies the customer base and can add incremental demand that supports revenue and earnings resilience.
See why 7 investors see EastGroup Properties as 14% undervalued.
Result: Fair Value of $227.90 (UNDERVALUED)
Still, if easing releasing spreads persist or new projects arrive into softer tenant demand, the bullish EastGroup Properties thesis could be tested quickly.
Find out about the key risks to this EastGroup Properties narrative.
Another View: EastGroup Properties On Earnings Multiples
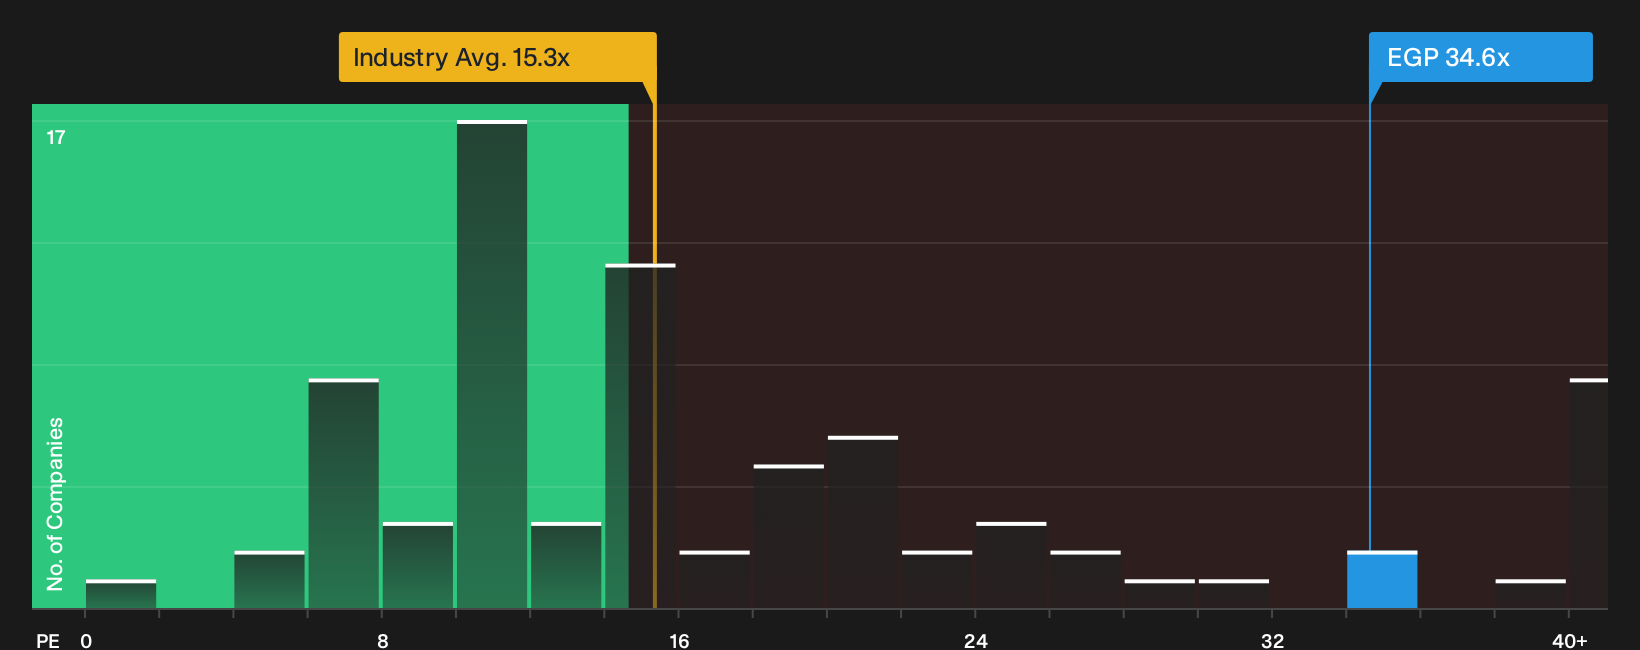
A different lens paints EastGroup Properties as expensive. The stock trades on a P/E of 34.6x, compared with 15.3x for the global Industrial REITs group and a fair ratio of 32.6x. That richer tag can signal quality, or it can simply compress future return potential. Which side do you think it reflects today?
To see how this richer valuation stacks up and where the market could move if pricing drifts toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on EastGroup Properties can feel uncomfortable, especially with both risks and rewards in play. Move quickly and review the full picture for yourself with 4 key rewards and 1 important warning sign.
Looking for more EastGroup Properties style investment ideas?
If EastGroup Properties has you rethinking what quality and valuation really look like, do not stop here. Use the Simply Wall St screener to hunt for new opportunities with different risk, income, and upside profiles across the market.
- Target potential mispricings by scanning companies that pair strong fundamentals with appealing valuations through the 33 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that offer robust yields and payout histories via the 8 dividend fortresses.
- Dial down portfolio risk by focusing on financially resilient businesses sourced from the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com