
3 Asian Growth Companies With Insider Ownership Up To 38%
As global markets navigate the complexities of AI spending concerns and inflation pressures, Asian economies continue to capture investor attention with their unique growth opportunities. In this environment, companies with high insider ownership often signal confidence in their long-term potential, making them intriguing prospects for those looking to align with management interests and capitalize on regional market dynamics.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Circuit Electronics (TWSE:2368) | 29.9% | 46.1% |
| Fulin Precision (SZSE:300432) | 11.7% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Here we highlight a subset of our preferred stocks from the screener.
Plus Alpha ConsultingLtd (TSE:4071)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Plus Alpha Consulting Co., Ltd. offers marketing and HR solutions in Japan with a market cap of ¥93.34 billion.
Operations: The company's revenue is derived from ¥14.94 billion in HR Solutions and ¥3.68 billion in Marketing Solutions.
Insider Ownership: 38.3%
Plus Alpha Consulting Ltd. demonstrates robust growth potential with earnings forecasted to grow at 14% annually, outpacing the JP market's 9.5%. The company's revenue is also expected to increase by 11.5% per year, surpassing the market average of 6.6%. Recent strategic moves include a ¥23.1 billion stake acquisition by Rakus Co., Ltd., and a completed share buyback program worth ¥1 billion, highlighting efforts to enhance shareholder value amidst leadership restructuring challenges.
- Take a closer look at Plus Alpha ConsultingLtd's potential here in our earnings growth report.
- According our valuation report, there's an indication that Plus Alpha ConsultingLtd's share price might be on the cheaper side.

AMIYA (TSE:4258)
Simply Wall St Growth Rating: ★★★★★☆
Overview: AMIYA Corporation is engaged in the development, manufacturing, and sale of cybersecurity products and services with a market cap of ¥54.34 billion.
Operations: The company's revenue is derived from two main segments: the Data Security Business, contributing ¥2.88 billion, and the Network Security Business, generating ¥3.84 billion.
Insider Ownership: 23.2%
AMIYA Corporation's growth trajectory is underscored by earnings projected to rise 23.44% annually, significantly outpacing the JP market's 9.5%. Revenue growth is also strong at an expected 27.5% per year, exceeding the market average of 6.6%. Recent strategic initiatives include a share buyback program amounting to ¥851.84 million, aimed at enhancing capital efficiency amid a volatile share price environment, and its inclusion in the S&P Global BMI Index supports its market presence expansion.
- Delve into the full analysis future growth report here for a deeper understanding of AMIYA.
- The analysis detailed in our AMIYA valuation report hints at an inflated share price compared to its estimated value.

Voltronic Power Technology (TWSE:6409)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Voltronic Power Technology Corp. and its subsidiaries manufacture and sell uninterruptible power systems (UPS) in Taiwan and Mainland China, with a market capitalization of NT$79.16 billion.
Operations: The company generates revenue of NT$19.58 billion from the manufacturing and trading of uninterruptible power systems and inverters.
Insider Ownership: 20.9%
Voltronic Power Technology's growth outlook is characterized by significant earnings growth projected at 26.5% annually, surpassing the TW market's 25.3%. However, revenue growth of 10.5% per year lags behind the market average of 21.8%. Despite trading at a value below its estimated fair value, recent earnings reports indicate declining net income and EPS compared to last year. The company's high future return on equity forecast (41.9%) remains a positive indicator for potential investors.
- Click to explore a detailed breakdown of our findings in Voltronic Power Technology's earnings growth report.
- Insights from our recent valuation report point to the potential overvaluation of Voltronic Power Technology shares in the market.
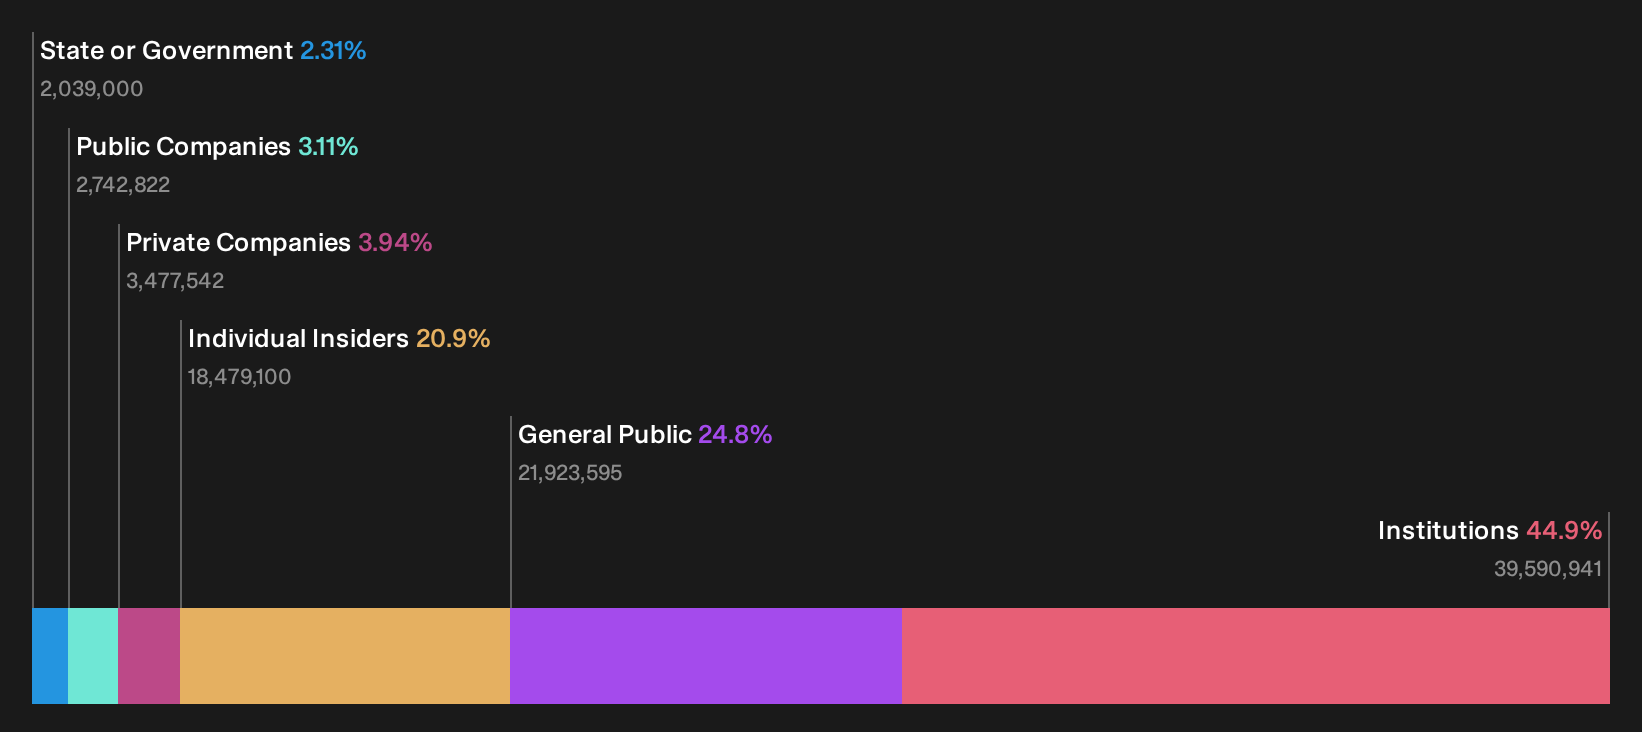
Turning Ideas Into Actions
- Click through to start exploring the rest of the 507 Fast Growing Asian Companies With High Insider Ownership now.
- Want To Explore Some Alternatives? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com