
Clas Ohlson (OM:CLAS B) Sales Jump Puts Its Valuation Back In Focus
Clas Ohlson (OM:CLAS B) is back in focus after reporting September net sales of SEK 1,119 million, up 19% year on year, with organic growth, acquisitions and currency all lifting the top line.
Investors have reacted quickly to the stronger trading update, with Clas Ohlson’s share price delivering a 14.11% 1 month share price return and a 56.06% year to date share price return. The 5 year total shareholder return is very large and points to momentum that remains firmly intact.
Capitalize on Clas Ohlson’s strong sales update by scanning a curated group of retailers showing solid momentum and fundamentals with the 613 high quality undiscovered gems.Bulls see Clas Ohlson’s surge and sales jump as confirmation that the rerating has room to run. Bears argue expectations already look full. Which side do the current valuation numbers lean toward from here?
Most Popular Narrative: 3% Undervalued
Clas Ohlson’s most followed narrative pegs fair value at SEK488.33 using a 6.5% discount rate, compared with a last close of SEK473.80. This frames a modest valuation gap for investors weighing the latest sales surprise against longer term expectations.
Clas Ohlson's shift from a generalist retailer to a multi-niche player allows them to differentiate within multiple market segments, which should drive continued sales growth and improve operating margins.
The focus on a profitable online business, with online sales growth at 22%, aims to continually increase the share of online sales, positively impacting revenue and potentially improving net margins.
See why 7 investors see Clas Ohlson as 3% undervalued.
Result: Fair Value of SEK488.33 (UNDERVALUED)
Still, the narrative around Clas Ohlson could be tested if currency swings pressure gross margins or if higher salary costs in Finland squeeze operating profitability.
Find out about the key risks to this Clas Ohlson narrative.
Another View: Clas Ohlson Through Its P/E
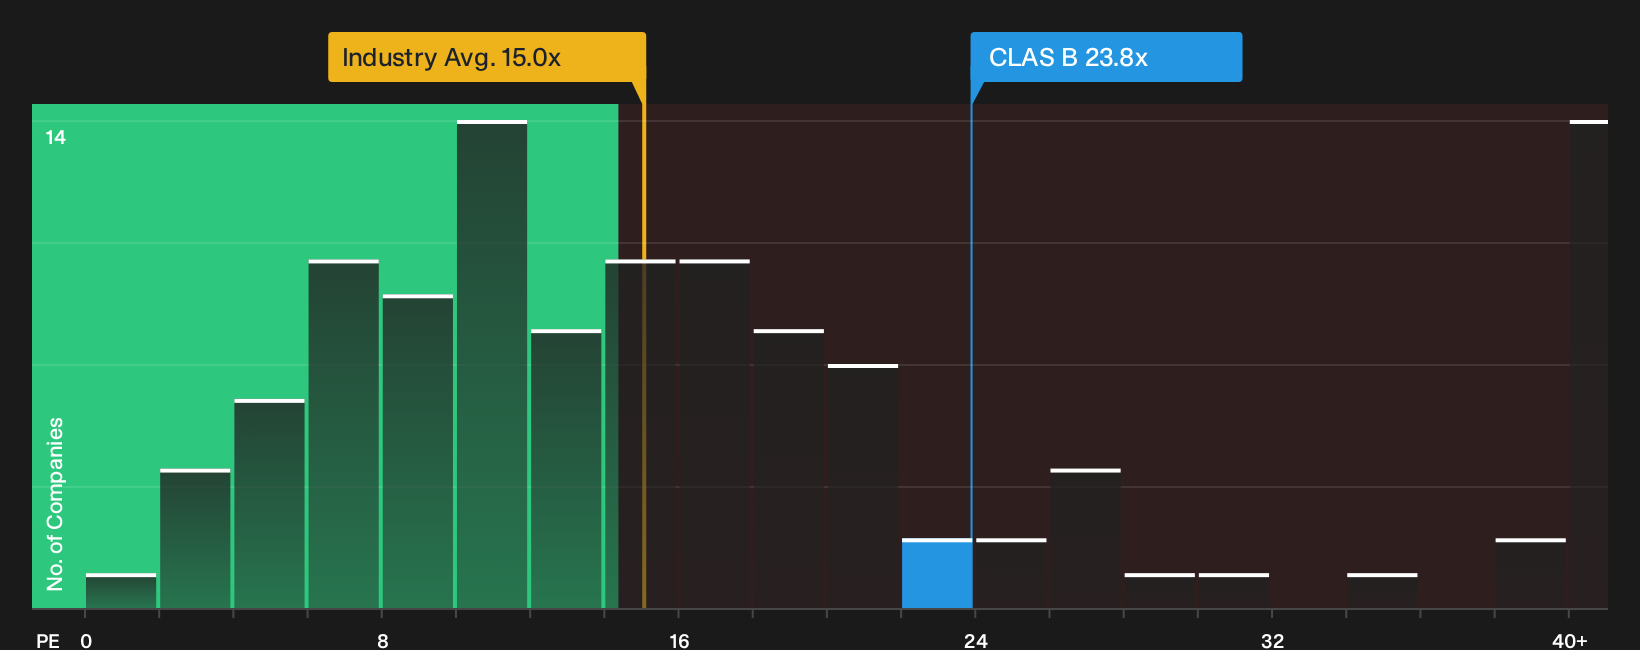
The fair value narrative points to Clas Ohlson trading about 11.6% below an estimated worth, but the current P/E of 23.8x tells a different story. That multiple is above the European Specialty Retail average of 15x, the peer average of 20.6x, and the fair ratio of 18.5x.
This gap suggests investors are already paying a premium for the recent growth and high return on equity. That raises the risk that any stumble on earnings or margins could hit the share price harder than a more modestly valued retailer. Does that rich P/E reflect durable strengths, or just enthusiasm for strong recent returns?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Clas Ohlson’s valuation and momentum can feel murky, so pull up the data, test your assumptions, and weigh both sides with 3 key rewards and 1 important warning sign.
Looking for more Clas Ohlson style investment ideas?
If Clas Ohlson’s setup has you thinking bigger, use the Simply Wall Street Screener to quickly surface fresh opportunities before they move without you.
- Target stability with companies that pair strong financial footing and low risk profiles using the 231 resilient stocks with low risk scores.
- Hunt for quality at a sensible price by scanning a curated set of potential bargains through the 195 high quality undervalued stocks.
- Build a watchlist of cash generators by zeroing in on income opportunities screened via the 216 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com