
Why Svenska Handelsbanken (OM:SHB A) Is Drawing Fresh Attention
Recent commentary on Svenska Handelsbanken (OM:SHB A) has focused on the bank’s returns on equity and generous payout profile, putting its dividend driven approach to shareholder value under a brighter spotlight.
Svenska Handelsbanken’s recent price action has been quietly positive, with a 90 day share price return of 8.8% and a year to date gain of 13.17% to SEK153.85. The 1 year total shareholder return of 41.97% signals that dividend reinvestment has been a major driver of overall gains.
Scan other income focused banks that show similar momentum and disciplined capital returns in our curated list of 216 dividend fortresses.
Svenska Handelsbanken’s mix of strong past shareholder returns and a rich dividend stream now meets a higher share price. Does that recent 1 year total return of 41.97% still leave enough upside on the table?
Most Popular Narrative: 8% Overvalued
Svenska Handelsbanken last closed at SEK153.85, which sits above the most followed narrative fair value of SEK142.24 that is based on a 6.28% discount rate. The story now hinges on whether its fee driven model can carry earnings without much help from loan growth.
The main factor that has to go right is that growth in savings and asset management fees, together with tight cost discipline and improving returns in the UK and Netherlands, continues to offset weaker lending growth and margin pressure in the Nordic loan books.
See why 28 investors see Svenska Handelsbanken as 8% overvalued.
Result: Fair Value of SEK142.24 (OVERVALUED)
Still, the whole narrative on Svenska Handelsbanken can be upset if net interest income keeps slipping after rate cuts, or if very high cash returns keep lifting funding costs.
Find out about the key risks to this Svenska Handelsbanken narrative.
Another View: SWS DCF Flags Upside For Svenska Handelsbanken
The analyst narrative pegs Svenska Handelsbanken’s fair value at SEK142.24, which makes today’s SEK153.85 look rich. The SWS DCF model tells a different story. On that framework, the shares are trading around 36.5% below an estimated cash flow value of SEK242.26, which points to a very different risk reward balance.
Both approaches rely on assumptions about fee durability, margins and payouts, yet they land far apart on “fair.” That kind of gap is where investors need to decide which set of inputs feels closer to how Svenska Handelsbanken actually runs its business.
To understand what sits inside that cash flow view, and how sensitive it is to small tweaks in growth or discount rates, Look into how the SWS DCF model arrives at its fair value.
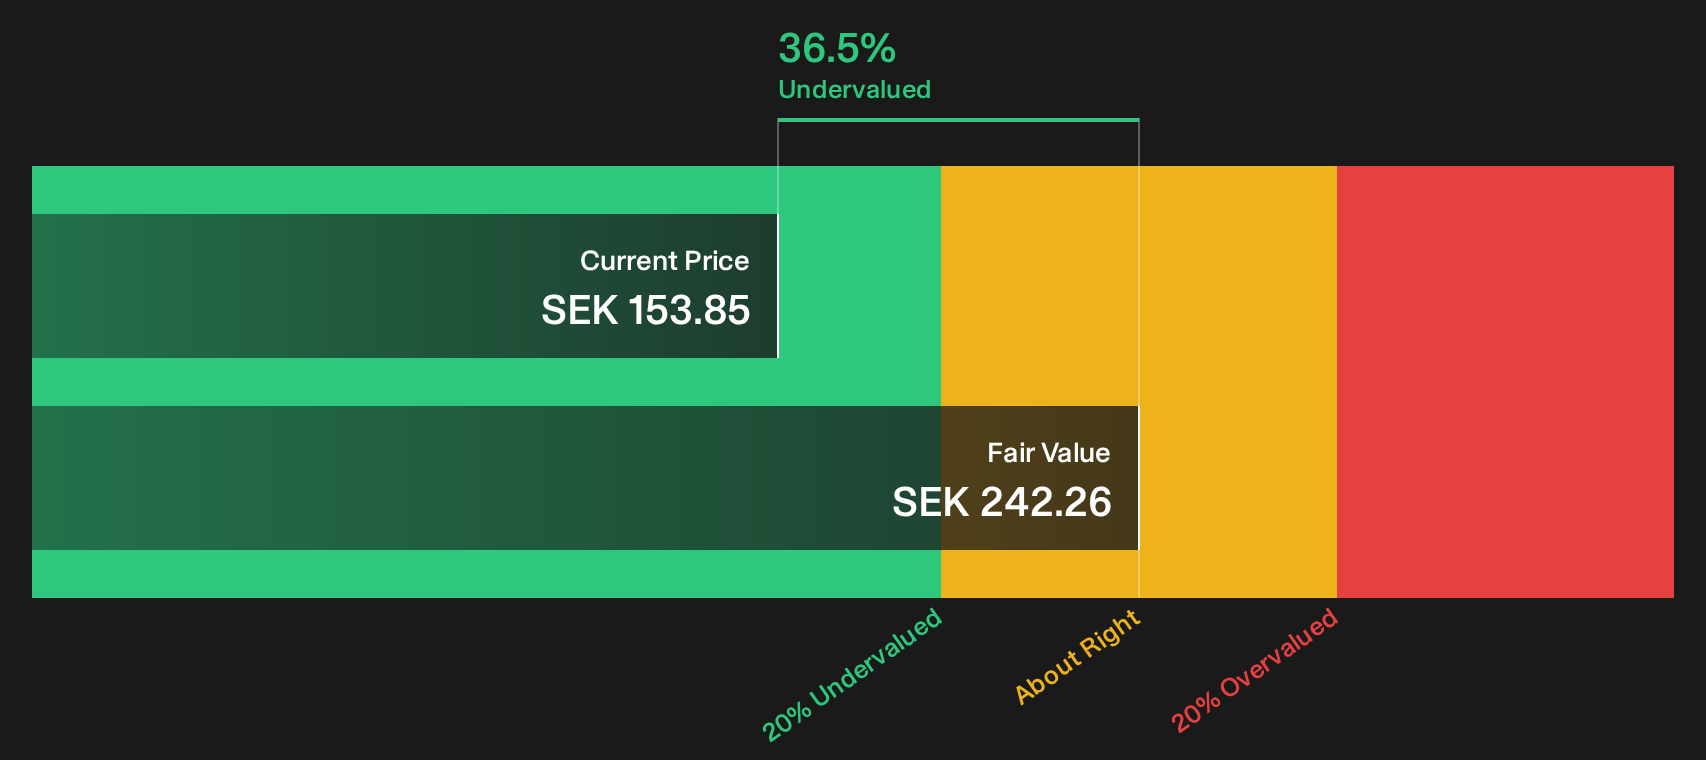
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Svenska Handelsbanken for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Svenska Handelsbanken so far. Act while sentiment is divided and weigh the full picture for yourself by checking the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Svenska Handelsbanken?
If Svenska Handelsbanken has sharpened your focus on quality and price, do not stop here. Broader opportunities across sectors might suit your goals even better.
- Target potential mispricing by scanning a tightly filtered set of quality companies that trade below their implied worth through the 195 high quality undervalued stocks.
- Prioritise resilience by focusing on firms with strong finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (203 results).
- Spot tomorrow’s potential leaders early by checking a curated pool of underfollowed businesses with solid fundamentals inside the 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com