
UK Growth Companies With High Insider Ownership
As the UK market grapples with global economic uncertainties, particularly influenced by China's sluggish recovery and its impact on commodity prices, investors are keenly observing how these conditions affect indices like the FTSE 100 and FTSE 250. In such a volatile environment, growth companies with high insider ownership can offer a unique perspective as insiders' vested interests may align closely with shareholders', potentially driving strategic decisions that foster long-term value creation.
Top 10 Growth Companies With High Insider Ownership In The United Kingdom
| Name | Insider Ownership | Earnings Growth |
| TPXimpact Holdings (AIM:TPX) | 19.5% | 106% |
| TEAM (AIM:TEAM) | 32% | 85.3% |
| Quantum Base Holdings (AIM:QUBE) | 31.8% | 111.8% |
| Mortgage Advice Bureau (Holdings) (LSE:MAB1) | 18.4% | 22.4% |
| Hardide (AIM:HDD) | 20.8% | 76.2% |
| Energean (LSE:ENOG) | 19.3% | 32.8% |
| EARNZ (AIM:EARN) | 10.1% | 90.6% |
| Crimson Tide (AIM:TIDE) | 33.5% | 119.1% |
| Built Cybernetics (AIM:BUC) | 22.6% | 122.1% |
| Beauty Tech Group (LSE:TBTG) | 19.9% | 23.8% |
Let's dive into some prime choices out of the screener.
Afentra (AIM:AET)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Afentra plc, with a market cap of £203.32 million, is an upstream oil and gas company operating primarily in Africa through its subsidiaries.
Operations: The company's revenue is primarily derived from its oil and gas exploration and production segment, which generated $153.40 million.
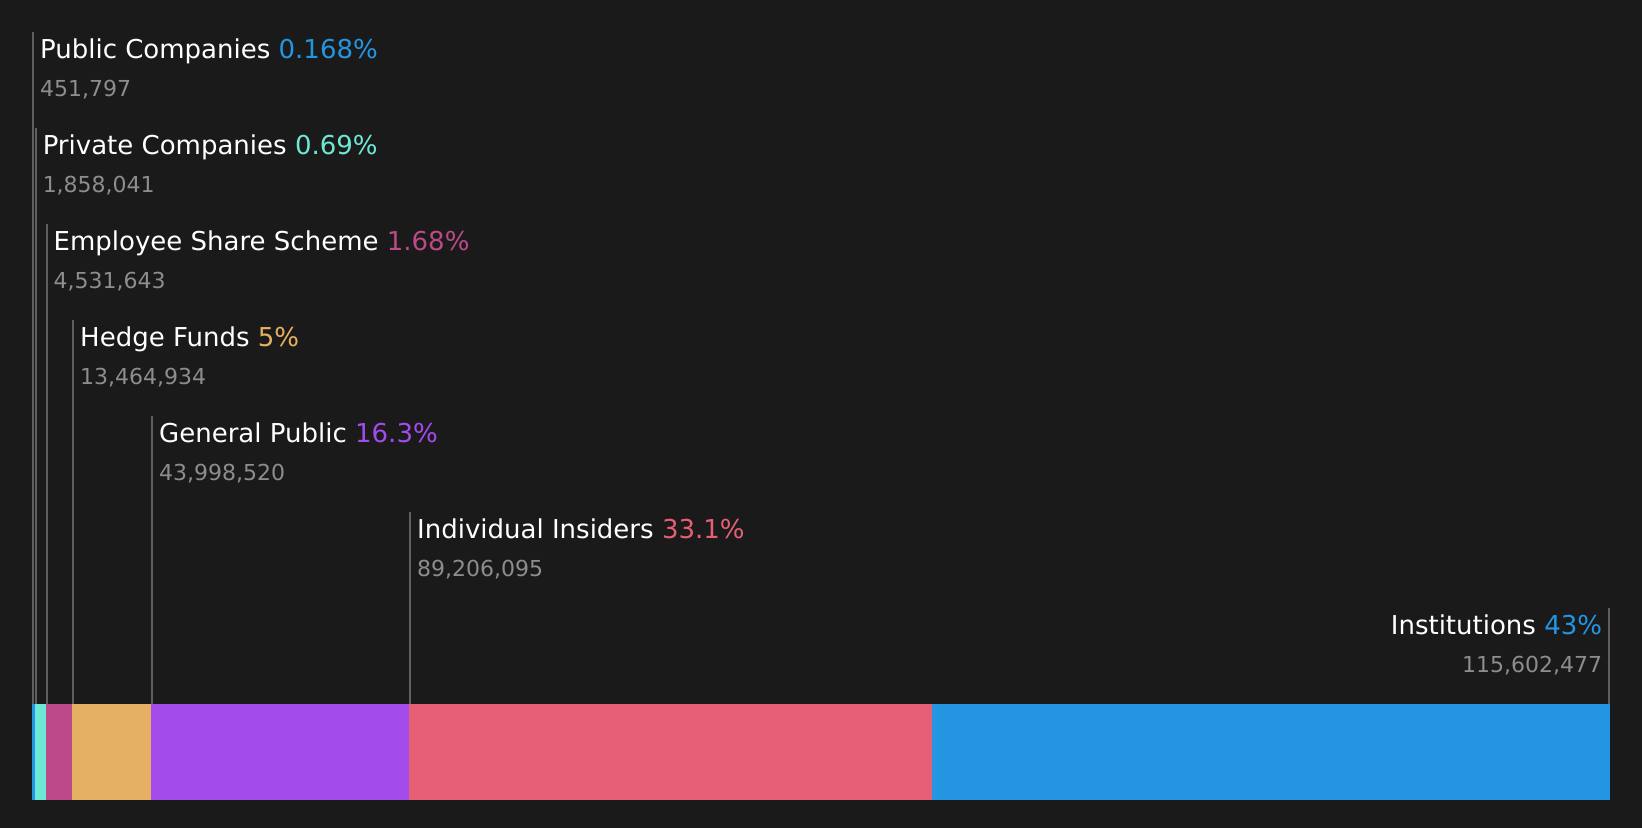
Insider Ownership: 32.4%
Afentra's strategic moves in offshore Angola, including the Impala-2 and Pacassa SW developments, highlight its growth potential. The company's operational updates reflect a focus on optimizing drilling schedules and resource upgrades. Despite recent financial losses, Afentra's revenue is projected to grow at 19.7% annually, outpacing the UK market average. The company trades significantly below estimated fair value and analysts anticipate a substantial price increase. However, past shareholder dilution may concern some investors.
- Click here to discover the nuances of Afentra with our detailed analytical future growth report.
- Our valuation report here indicates Afentra may be undervalued.
Computacenter (LSE:CCC)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Computacenter plc offers technology and services to corporate and public sector organizations across the UK, Germany, Western Europe, North America, and internationally, with a market cap of £5.35 billion.
Operations: The company's revenue from Computer Services amounts to £12.05 billion.
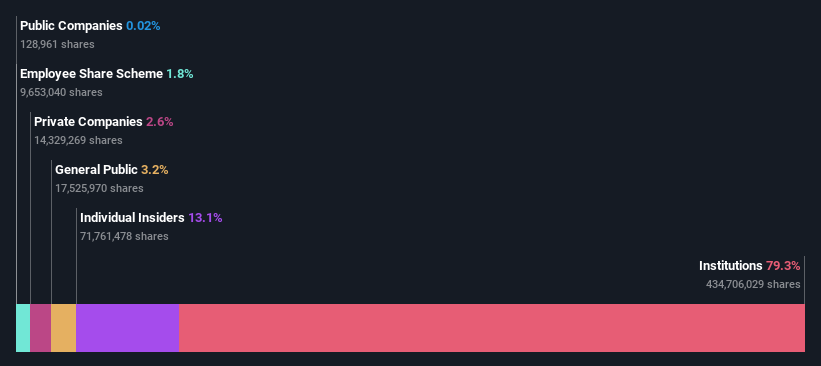
Insider Ownership: 15.6%
Computacenter demonstrates promising growth potential with its revenue and earnings projected to outpace the UK market. Recent earnings results show substantial improvement, with sales reaching £6.85 billion and net income doubling compared to last year. The company declared an increased interim dividend of 27.1 pence per share, reflecting financial strength. Although insider buying is present but not substantial, the stock trades below analyst price targets, indicating potential upside in valuation amidst a competitive IT sector landscape.
- Click here and access our complete growth analysis report to understand the dynamics of Computacenter.
- The analysis detailed in our Computacenter valuation report hints at an deflated share price compared to its estimated value.

QinetiQ Group (LSE:QQ.)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: QinetiQ Group plc delivers science and technology solutions in the defense, security, and infrastructure sectors across the United States, Australia, Canada, and Germany with a market cap of £2.55 billion.
Operations: The company's revenue is primarily derived from its EMEA Services segment, which accounts for £1.53 billion, followed by the Global Solutions segment at £393.40 million.
Insider Ownership: 14.4%
QinetiQ Group shows strong growth potential, with earnings projected to grow 16.8% annually, outpacing the UK market's 11.2%. The stock trades at a significant discount to its estimated fair value and offers good relative value compared to peers. Despite no recent insider trading activity, QinetiQ became profitable this year and maintains a reliable dividend yield of 2.21%. Revenue is expected to grow at 5.1% per year, surpassing the broader market rate.
- Get an in-depth perspective on QinetiQ Group's performance by reading our analyst estimates report here.
- Our comprehensive valuation report raises the possibility that QinetiQ Group is priced lower than what may be justified by its financials.
Taking Advantage
- Access the full spectrum of 64 Fast Growing UK Companies With High Insider Ownership by clicking on this link.
- Ready For A Different Approach? Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 32 best rare earth metal stocks of the very few that mine this essential strategic resource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com