
China Energy Engineering (SEHK:3996) Could Be Fully Priced On Green Ammonia Shipping First
China Energy Engineering (SEHK:3996) drew fresh attention after its green ammonia project supplied 1,000 tonnes of fuel for the world’s first commercial ship-to-ship bunkering at Zhoushan Port on 13 October 2026.
That green ammonia milestone lands at a time when China Energy Engineering’s shares have had a softer run. The latest HK$1.03 quote comes after a 1-day share price gain of 1.48%, but the year-to-date share price return has declined 4.63%, while the 1-year total shareholder return has fallen 12.04% compared with a still positive 36.61% over three years.
Scan beyond China Energy Engineering and identify other potential beneficiaries of the energy transition in our hand picked 42 power grid technology and infrastructure stocks, aligned with large scale infrastructure and cleaner power demand.
China Energy Engineering now trades at HK$1.03 after a weaker year, even as it links green ammonia supply to a headline grabbing shipping first. Does that recent slip already reflect the risks, or is patience on price entry still worth considering before running the numbers?
Preferred P/E of 7.2x for China Energy Engineering: Is it justified?
On Simply Wall St’s metrics, China Energy Engineering trades on a P/E of 7.2x, while the last close sits at HK$1.03. Against that earnings multiple, the stock looks cheaper than the wider Hong Kong market but richer than its closest construction peers.
P/E compares the current share price with earnings per share, so you are effectively asking how many dollars of price you pay for one dollar of profit. For a capital heavy builder and power infrastructure group like China Energy Engineering, investors often watch this closely because profit quality, cash conversion and balance sheet strength can all shift how comfortable they feel with that earnings tag.
China Energy Engineering scores highly on earnings quality, yet there are pressure points. Profit margins currently sit at 1.2%, which is below last year’s 1.8%, and earnings declined 34.6% over the past year even though they have grown on average 1% a year over five years. Debt is not well covered by operating cash flow and all funding is described as higher risk external borrowing, which can justify a lower P/E if investors worry about cash generation or financial resilience.
The comparison with others in Hong Kong is mixed. Relative to the broader Hong Kong market on 10.6x, the 7.2x P/E suggests investors are paying a lower price for each dollar of China Energy Engineering earnings. Compared with the Hong Kong Construction industry on 12.6x, the discount looks even wider. Against its own direct peer group though, the stock looks expensive, since its 7.2x P/E sits above a 5.3x peer average. That gap implies the market is attaching a richer tag to this ticker than to similar construction stocks, despite softer recent profit trends.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 7.2x (OVERVALUED).
Still, heavy reliance on higher risk external borrowing and thin 1.2% profit margins could quickly challenge the China Energy Engineering story if project cash flows disappoint.
Find out about the key risks to this China Energy Engineering narrative.
Another View on China Energy Engineering using our DCF model
The P/E suggests China Energy Engineering trades on a modest earnings tag, yet the SWS DCF model paints a tougher picture. At HK$1.03 versus an estimated future cash flow value of HK$0.32, the shares screen as overvalued. Which lens do you trust more when profit quality and cash generation pull in different directions?
Look into how the SWS DCF model arrives at its fair value.
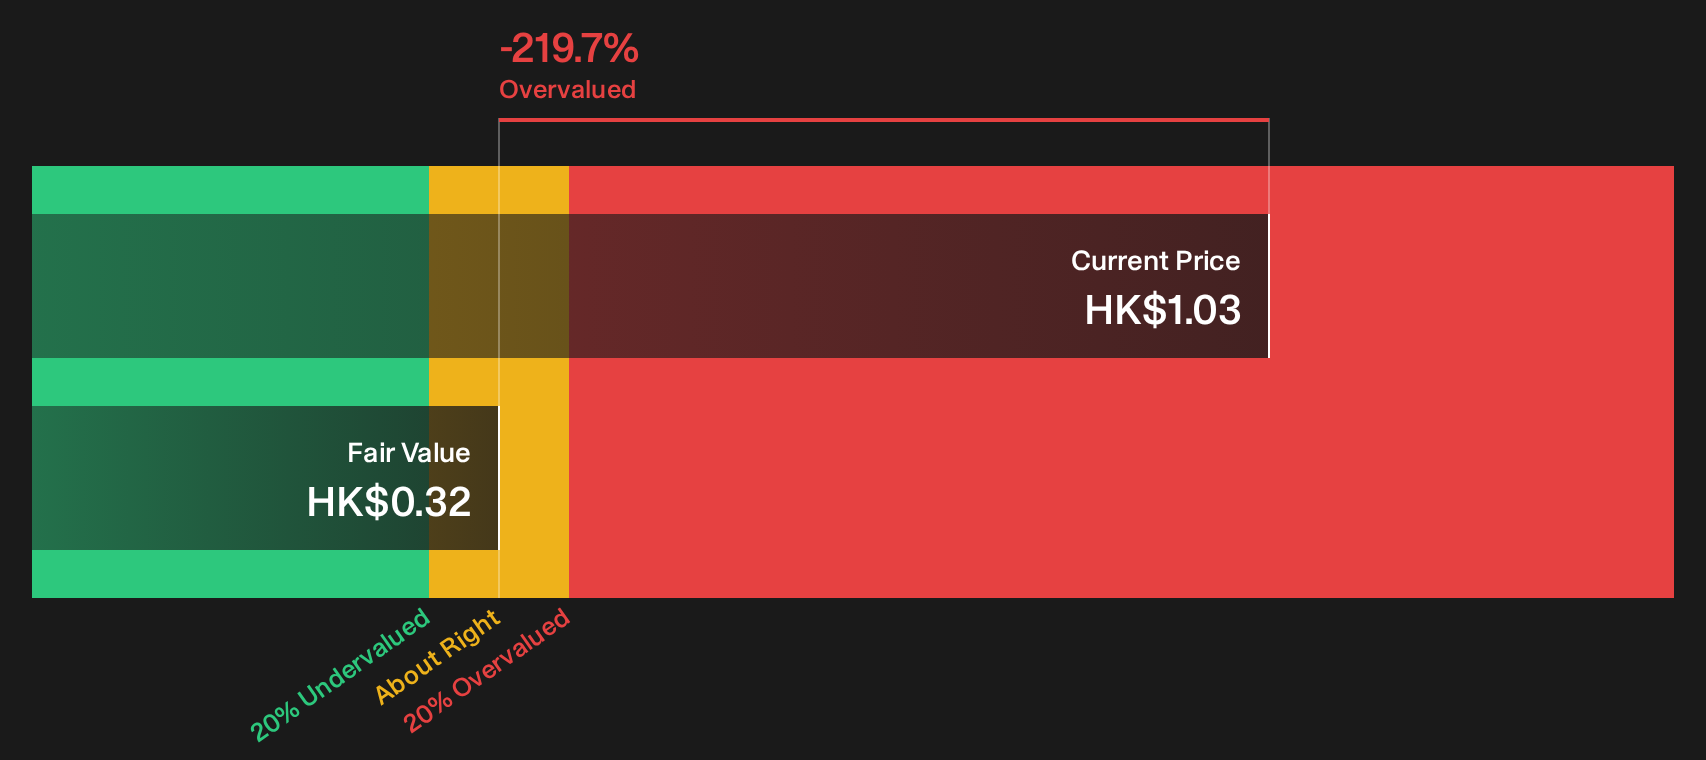
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Energy Engineering for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the China Energy Engineering story can feel confusing, especially with both clear concerns and clear positives on the table. Move quickly from headline impressions to your own judgment by reviewing the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond China Energy Engineering?
If China Energy Engineering has sharpened your thinking, do not stop there. Fresh ideas often come from comparing it with high quality alternatives uncovered by data driven screens.
- Target resilience by scanning companies that pass tough balance sheet and fundamentals filters with our list of solid balance sheet and fundamentals (203 results).
- Hunt for value by reviewing the 195 high quality undervalued stocks that combine stronger cash flows with sturdier financial profiles.
- Spot overlooked potential by checking the 613 high quality undiscovered gems that rarely hit headlines yet already show solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com