
Can Service Momentum Reframe The DEUTZ Stock Valuation Debate
- Recent commentary on DEUTZ highlights multi-year execution and questions whether the current valuation aligns with earnings, with close attention on its high-margin service activities, recent acquisitions, and customer partnerships.
- An interesting angle is that some investors now frame DEUTZ as a service-led industrial platform, where recurring aftermarket work and acquired capabilities could matter as much as engine volumes.
- We will now look at how DEUTZ's investment narrative may shift given the focus on its high margin service business momentum.
Scan other industrials with service-led momentum by reviewing the hand-picked 195 high quality undervalued stocks that, like DEUTZ, are being watched closely for earnings support and potential mispricing.
What Is DEUTZ's Investment Narrative?
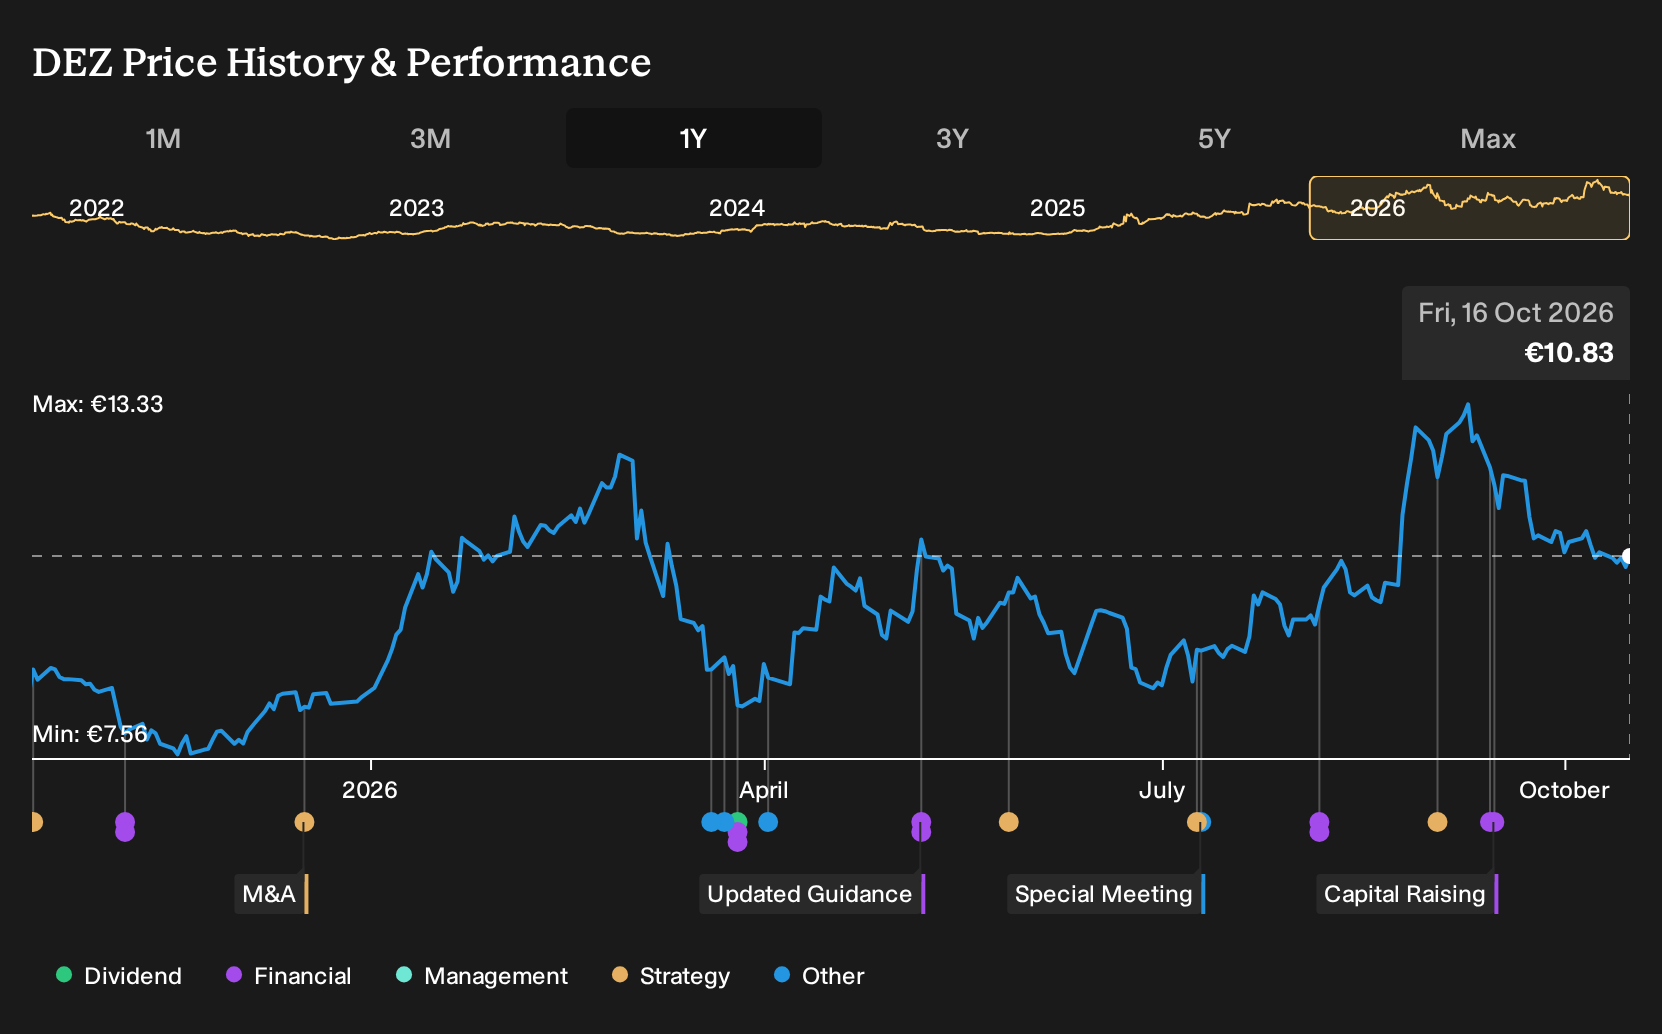
To own DEUTZ today, you need to buy into a fairly simple idea. The real story is whether a service led engine platform, with recurring aftermarket work and acquired capabilities, can keep supporting earnings that some models say are not fully reflected in the current €10.83 share price. Recent commentary that frames DEUTZ as 29% undervalued leans heavily on that services momentum. The short term swing factors are still pretty operational though. Engine order patterns, pricing discipline and how efficiently new acquisitions are integrated will probably matter more than headline opinion on valuation.
Execution risk is not small. This is an asset heavy industrial group with a high level of debt, a dividend that is not well covered by free cash flow and recent results that include large one off items. Those ingredients can all amplify both good and bad cycles in demand. Analysts currently expect faster earnings and revenue growth than the wider German market, which supports the idea that the premium P/E to the Machinery industry can be earnings backed if management delivers. If that service led narrative stumbles or leverage bites at the wrong moment, the re rating argument could change quickly.
That said, the more interesting part of the DEUTZ story right now is the one thing the bullish narrative tends to skim over...
There's only one way to know the right time to buy, sell or hold DEUTZ. Head to Simply Wall St's company report for the latest analysis of DEUTZ's Fair Value.
Exploring Other Perspectives
One alternate view on DEUTZ leans heavily on the planned FFG driven defense unit. The most optimistic analysts had pencilled in revenue of €5.3b and earnings of €572.5m by about 2029, far above consensus. Those projections were set before this news, so you should expect opinions and models to evolve.
Explore 5 other DEUTZ fair value estimates, including one that suggests up to 200% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DEUTZ research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for DEUTZ. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DEUTZ's overall financial health at a glance.
Looking For More Investment Ideas Beyond DEUTZ?
If DEUTZ has sharpened your focus on valuation, balance sheet strength and downside protection, it can help to line it up against other opportunities using a consistent framework.
- For investors who want quality on sale, compare DEUTZ against a broader set of undervalued opportunities using the 195 high quality undervalued stocks.
- If capital preservation and stability matter most to you, filter for businesses with robust finances and steady fundamentals through the list of solid balance sheet and fundamentals (203 results).
- When you are hunting for resilient performers with lower risk profiles, widen your search with the 231 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com