
New $1.1 Billion Credit Line Might Change The Case For Investing In Werner Enterprises (WERN)
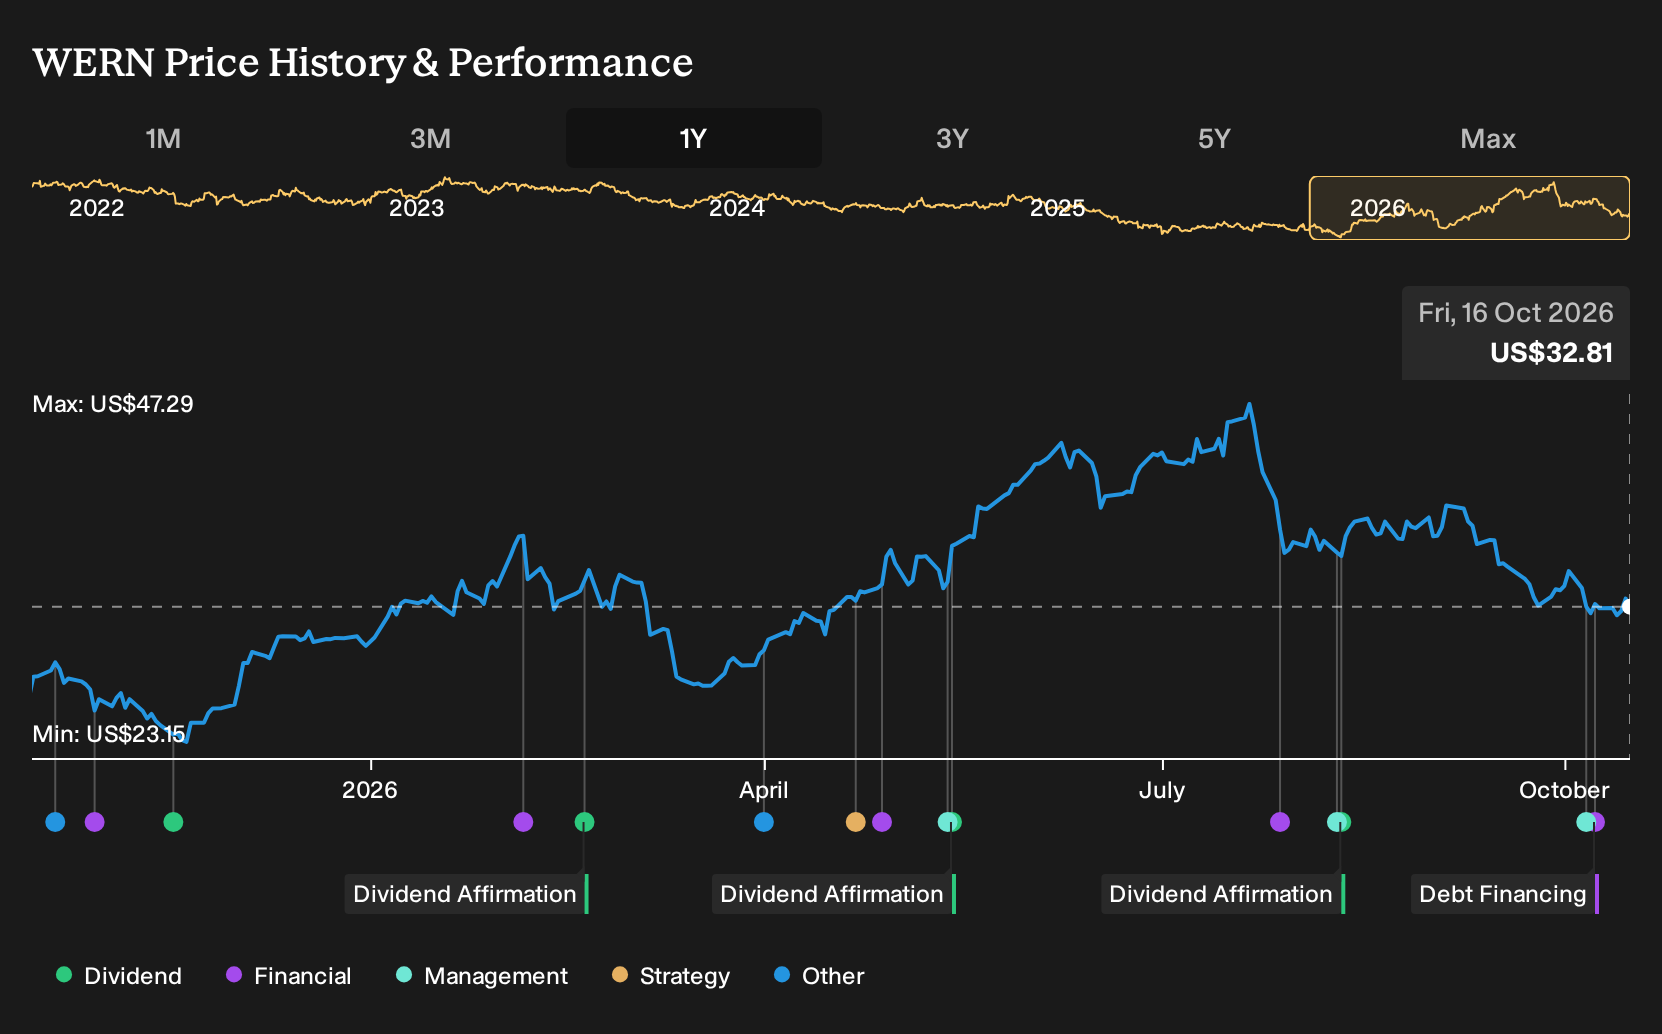
- Werner Enterprises entered a new US$1.1b unsecured credit facility maturing in 2031, replacing its prior agreement and providing revolving capacity, swingline loans and letter of credit support tied to leverage based pricing.
- The facility removes the prior SOFR credit adjustment spread and keeps US$603.1m of remaining borrowing capacity, giving Werner Enterprises substantial room to fund equipment, acquisitions, share repurchases and day to day needs without near term principal repayments.
- The next consideration is how this larger unsecured credit facility, with its extended maturity and flexible uses, could reshape Werner Enterprises' investment narrative.
Werner Enterprises Investment Narrative Recap
To own Werner Enterprises, you need to believe its push into Dedicated, private fleet conversions and tech enabled trucking can translate into steadier margins even while Logistics fixes recent weakness. The new US$1.1b unsecured facility mostly supports that story by extending liquidity and giving the business more flexibility to fund fleet and systems work.
The key near term swing factor is still whether truckload mix and pricing can offset pressure from insurance, litigation and driver costs, not the refinancing itself. The biggest risk remains that higher legal, labor and interest expenses outpace efficiency gains, which would keep returns and net income under pressure.
Among recent announcements, the new credit agreement is the most relevant because it directly intersects with Werner Enterprises’ balance sheet and investment priorities. The facility runs to 2031, carries leverage based pricing and leaves about US$603.1m of capacity available for fleet, acquisitions, repurchases and working capital if management chooses to use it.
This extra headroom can support the existing catalysts you are watching, including Dedicated expansion, FirstFleet integration and digital platform roll out, but it does not remove execution risk. Interest payments still need to be supported by future earnings, so the operational job remains the same: to lift profitability in Truckload and restore Logistics margins.
Werner Enterprises' current analyst narrative points to revenue of US$4.4b and earnings of US$300.3m by 2029. That profile is built on 10.6% yearly revenue growth and an earnings swing of about US$346.6m from today’s loss of US$46.3m to the forecast profit.
Uncover why Werner Enterprises' fair value indicates a potential 31% upside to its current price before that discount closes.
Exploring Other Perspectives
You might view this new Werner Enterprises credit facility as a potential growth catalyst, yet the most cautious analysts emphasize cost risks. Before this news, they were only penciling in about US$4.1b of revenue and US$277.4m of earnings by 2029, which reflects a more conservative outlook. Use that gap to stress test your own view.
Explore 2 other Werner Enterprises fair value estimates, including one that suggests there may be as much as 6% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Werner Enterprises research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Werner Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Werner Enterprises' overall financial health at a glance.
Looking for more investment ideas beyond Werner Enterprises?
Once you have a view on Werner Enterprises, it can help to line it up against a wider watchlist so you are not relying on a single story. The Simply Wall St Screener lets you quickly filter for different traits, whether you care most about value, balance sheet strength or income potential.
- For investors who want quality at a sensible entry point, compare Werner Enterprises against a broader bench of opportunities using the 33 high quality undervalued stocks.
- If capital preservation and balance sheet resilience are your priority, broaden your research with a 32 resilient stocks with low risk scores that may better match your comfort level.
- For those focused on income, round out your watchlist with a 8 dividend fortresses that could complement Werner Enterprises in a diversified portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com