
Could MATSUDA SANGYO (TSE:7456) Be A Bargain Following Fresh Focus On Its 8x P E?
Recent commentary has put MATSUDA SANGYO (TSE:7456) in focus after its P/E ratio appeared below industry averages, prompting investors to reassess whether the current share price reflects its underlying earnings profile.
Recent moves suggest sentiment around MATSUDA SANGYO is being reset rather than collapsing. The share price is up 22.91% over 90 days and 24.53% year to date, yet the 30-day share price return is down 10.08%. This hints that momentum has cooled even as the 1-year total shareholder return of 50.59% and 3-year total shareholder return of 180.39% keep the longer-term story firmly in positive territory.
Spot opportunities with a similar earnings story by scanning our hand-picked list of 13 high quality undervalued stocks that, like MATSUDA SANGYO, trade on valuations the market might be underrating.
After a sharp run over three years and a recent 10.08% pullback in 30 days, MATSUDA SANGYO now trades on a lower P/E than peers. Does that set up a reasonable entry now, or is it better to wait?
Price-to-Earnings of 8x: Is it justified?
MATSUDA SANGYO closed at ¥6,600 with a P/E of 8x, which screens as inexpensive compared to both peers and the broader JP market based on current earnings.
The P/E ratio shows how much investors are paying today for each unit of profit the business generates. For a group like MATSUDA SANGYO that earns income from precious metals processing and a food-related arm, this metric helps you see how the market values its current profitability relative to similar commercial services stocks.
Here, the picture is clear. The shares trade on a P/E of 8x against a peer average of 11.3x and a JP Commercial Services industry average of 13.5x, which is a steep discount. Compared to an estimated fair P/E of 17.4x, the gap is even wider, suggesting the multiple could move toward a much higher level if sentiment and expectations align more closely with that fair ratio.
Explore the SWS fair ratio for MATSUDA SANGYO.
Result: Price-to-Earnings of 8x (UNDERVALUED)
Still, MATSUDA SANGYO relies heavily on precious metals recovery and industrial waste volumes, so weaker activity or pricing in those areas could quickly blunt the current valuation case.
Find out about the key risks to this MATSUDA SANGYO narrative.
Another view on MATSUDA SANGYO
The P/E story points to value, but the SWS DCF model paints a different picture. In that framework, MATSUDA SANGYO at ¥6,600 trades above an estimated future cash flow value of ¥3,451.68, which screens as overvalued. Which lens is more useful for assessing a cyclical precious metals and waste processor?
Look into how the SWS DCF model arrives at its fair value.
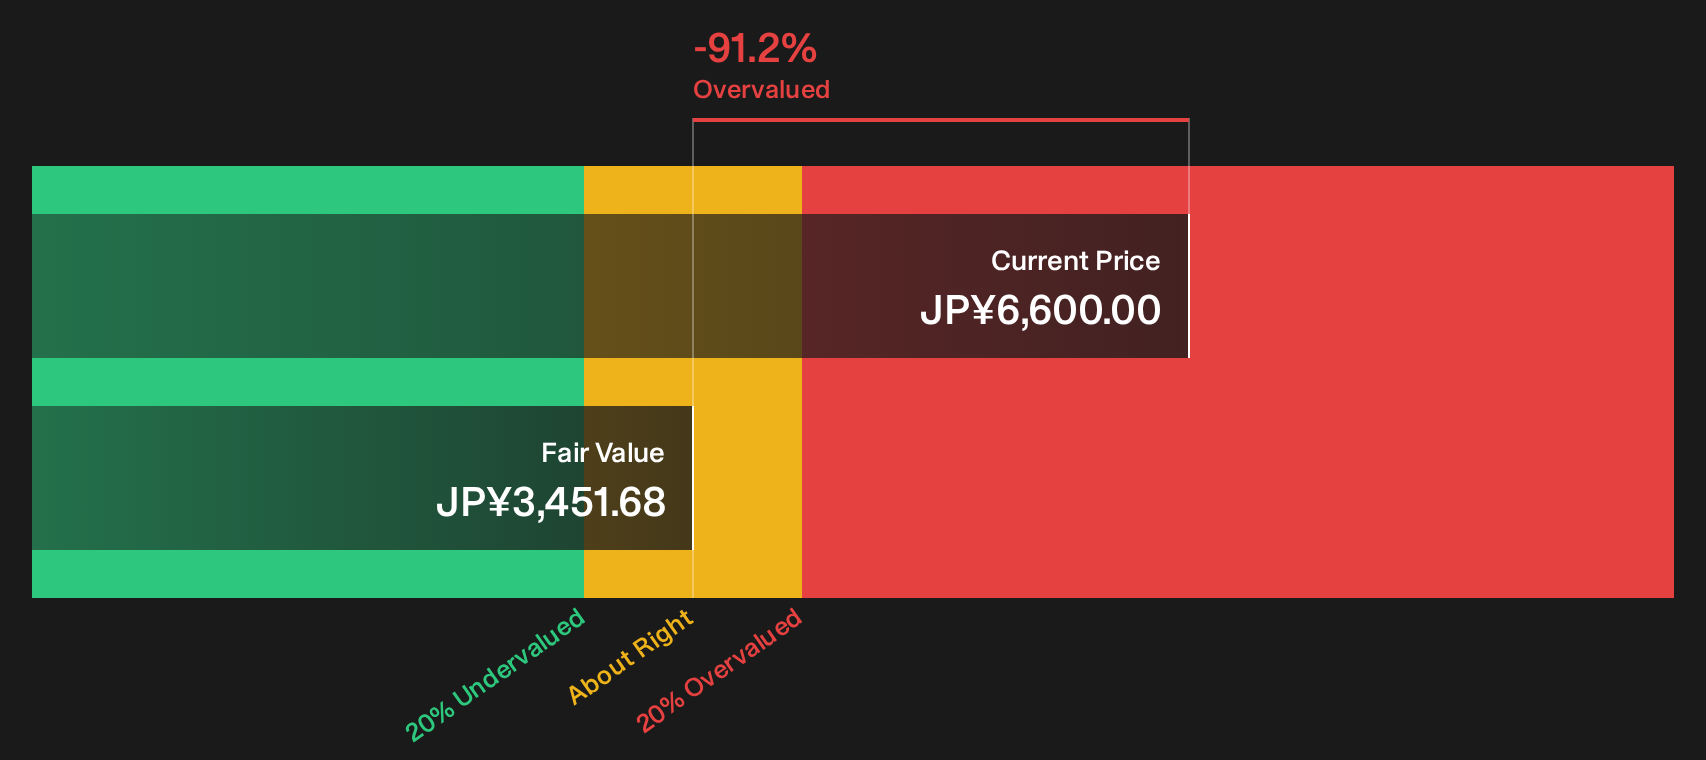
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MATSUDA SANGYO for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around MATSUDA SANGYO can feel confusing, so treat them as a prompt to scrutinise the data yourself, move quickly, and decide what the risk reward balance looks like in your own portfolio using the 4 key rewards and 2 important warning signs.
Looking for more MATSUDA SANGYO sized investment ideas?
If MATSUDA SANGYO has sharpened your focus on pricing and risk, do not stop here. Broaden your watchlist now so the next opportunity does not pass you by.
- Target potential bargains before they are crowded by scanning a curated pool of 13 high quality undervalued stocks that combine appealing prices with solid fundamentals.
- Seek more predictable cash flows in your portfolio by reviewing a hand-picked group of income ideas through the 29 dividend fortresses.
- Limit your downside risk by focusing on financially robust businesses using the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com