
How Investors Are Reacting To AT&T (T) Expanded Service Guarantees
- AT&T has recently expanded its America's Best Guarantee with faster support response commitments, outage credits, Internet Backup for fiber customers, and AI generated care summaries, while also deepening its work with Itron to connect utility gas and water modules over AT&T's LTE M network.
- The combination of richer service guarantees and embedded utility connectivity positions AT&T to lean harder into higher value, stickier recurring relationships across both households and enterprise utility clients.
- Next, the focus shifts to how AT&T's reinforced customer guarantees could influence the existing investment narrative built around fiber convergence.
AT&T Investment Narrative Recap
To own AT&T, you need to believe the heavy spend on fiber, 5G and convergence can keep service revenue steady while legacy copper costs are cut out over time. The immediate swing factor is execution on that shift and whether customer guarantees actually translate into more reliable retention and fewer support touches.
The biggest near term risk still sits in high debt, slower copper retirement and rich device promos that could pressure margins if customer value does not keep up. These new service guarantees look helpful for loyalty but do not fundamentally change those core execution and balance sheet questions.
The new America’s Best Guarantee update matters most because it ties directly into AT&T’s push to grow converged households on fiber and wireless. Faster support response, outage credits and Internet Backup aim to make the bundle feel more dependable for customers who pay for multiple services under one roof.
For investors watching catalysts, the key test is whether these commitments reduce churn and support pricing power while subsidies such as up to US$1,200 iPhone trade in credits remain aggressive. If support costs or make good credits escalate without clear operational efficiencies, margin pressure could offset some of the convergence benefits.
AT&T's analyst narrative points to forecast revenue of US$137.1b and projected earnings of US$18.7b by 2029, based on an assumed 2.5% yearly revenue growth rate. This profile implies earnings today of US$21.5b and an earnings decline of US$2.8b to reach the 2029 consensus figure.
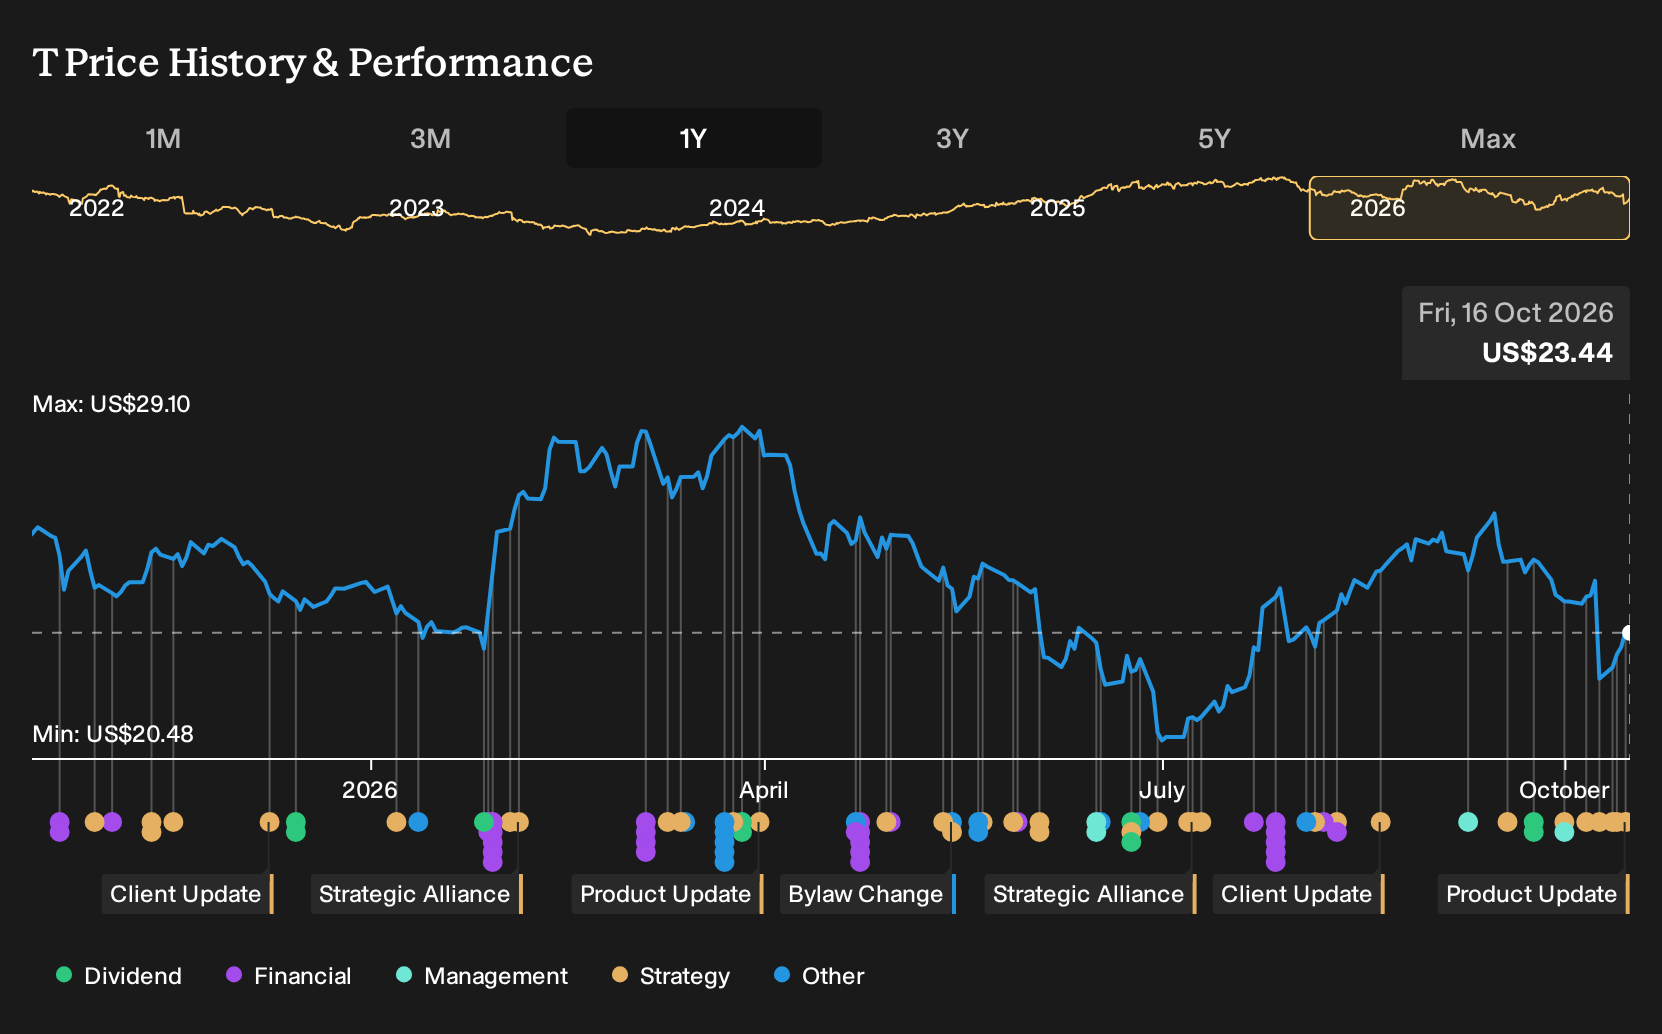
Discover how AT&T's fair value indicates a 24% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into AT&T’s copper retirement plan as the real catalyst. They were already modeling revenue of about US$140.0b and earnings of US$19.4b by 2029, compared with the US$137.1b and US$18.7b in the baseline view. You can treat these richer service guarantees as fresh inputs that might push those narratives to shift in very different directions.
Explore 7 other AT&T fair value estimates, including one that suggests as much as 266% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent analysis.
- A great starting point for your AT&T research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for AT&T. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AT&T's overall financial health at a glance.
Looking For More Investment Ideas Beyond AT&T?
If AT&T helps anchor your watchlist, it can still pay to scan a wider field of opportunities. Use the Simply Wall St Screener to widen your net in a structured way instead of scrolling through tickers at random.
- For investors who want potential mispricings with quality fundamentals, run your eye over 33 high quality undervalued stocks that may warrant a closer look.
- If capital preservation ranks high on your list, take a look at 32 resilient stocks with low risk scores that score well on resilience and lower risk profiles.
- When income is the priority, start with 8 dividend fortresses that combine yields above 5% with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com