
Is Zai Lab (ZLAB) A Bargain Following Its ZL 1503 Data Update?
Zai Lab (ZLAB) is back on investors' radar after the company said it will share first-in-human data for its bispecific antibody ZL-1503 at the ACAAI 2026 scientific meeting in November.
That announcement lands after a choppy year for Zai Lab, with the share price up 33.81% year to date, but the 1-year total shareholder return still down 19.31%. This suggests recent momentum has improved even as longer term holders remain under water.
Spot other potential breakout stories in immunology and biotech by scanning the 33 healthcare AI stocks that pair cutting-edge science with data driven drug development.After a sharp rebound in Zai Lab over the past few months, the key question is whether meaningful upside still lies ahead or whether the bulk of the rerating is already in the rearview mirror as valuation comes into focus.
Most Popular Narrative: 30% Undervalued
Against a last close of $23.19, the most followed narrative anchors Zai Lab’s fair value around $33.30. This frames today’s price as a discount and places extra weight on how its pipeline and China footprint evolve from here.
Multiple high-potential product launches and label expansions over the next 12-18 months (including VYVGART, bemarituzumab, KarXT, TIVDAK, Tumor Treating Fields), combined with a deep pipeline in oncology and immunology, are expected to significantly increase Zai Lab's addressable market and diversify revenue streams, supporting both top-line growth and future earnings.
See why 13 investors see Zai Lab as 30% undervalued.
The most widely followed view ties this valuation to a discount rate of 7.87%, a fair value estimate of $33.30, and revenue growth assumptions of roughly 22% a year. Analysts behind this framework do not project Zai Lab to reach profitability within the next 3 years. As a result, the gap between the current share price and the narrative fair value leans heavily on the long runway for oncology and immunology medicines in China and on execution across its partnered portfolio.
Result: Fair Value of $33.30 (UNDERVALUED)
Still, the bullish Zai Lab narrative relies on smooth execution in China. Setbacks in regulatory decisions or partner funded programs could quickly challenge those assumptions.
Find out about the key risks to this Zai Lab narrative.
Another View: Zai Lab Looks Expensive On Sales
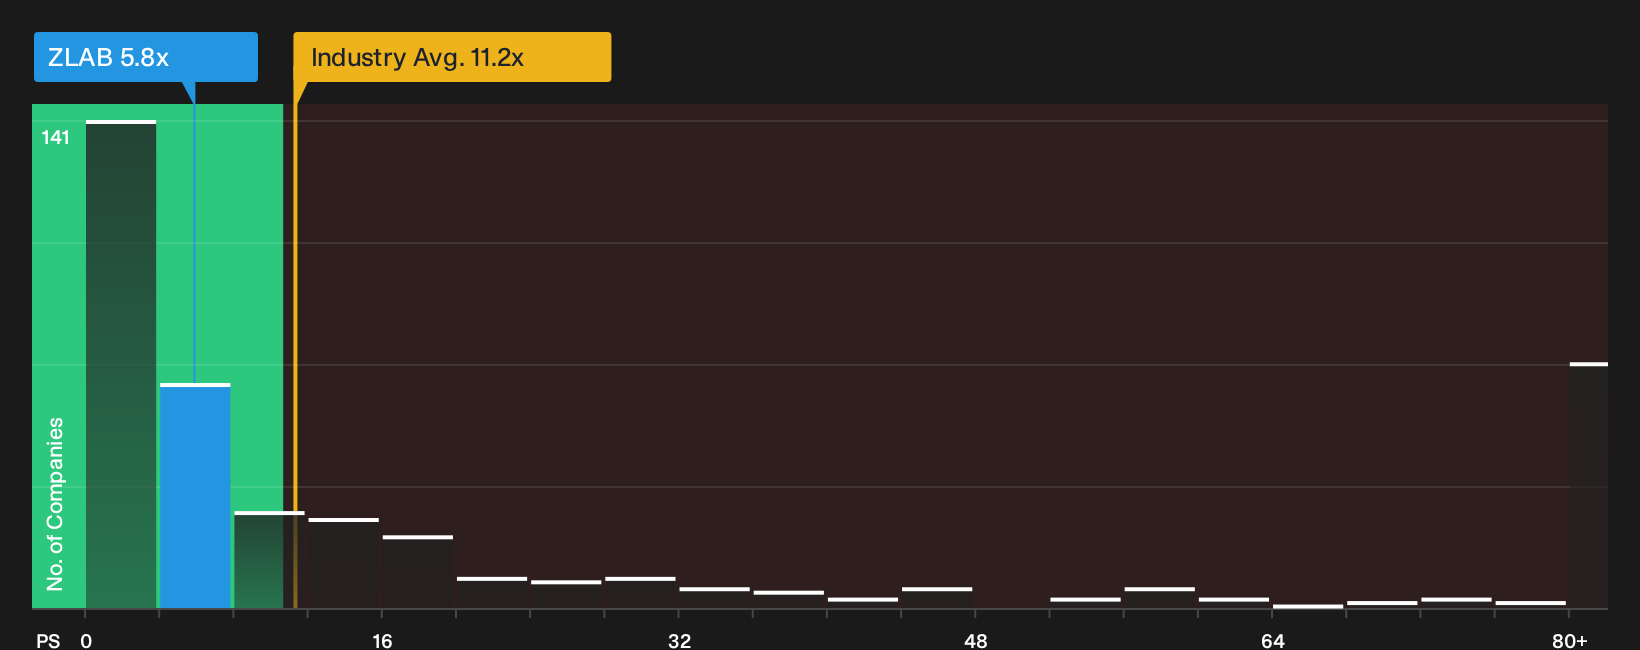
The bullish Zai Lab narrative leans on a big gap to fair value, yet the P/S ratio tells a more cautious story. The stock trades on 5.8x sales, while the fair ratio sits at 3.3x and the broader US Biotechs group sits higher at 11.2x.
Peers on average change hands at 9.7x, so Zai Lab screens cheaper than similar companies but richer than where the fair ratio suggests the multiple could drift. That mix of apparent discount to the sector yet premium to the fair ratio raises a simple question for you: Is this a margin of safety or a valuation trap in the making?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Investors are divided on whether the recent Zai Lab rebound meaningfully changes the long-term risk reward profile or simply sets up the next key test. Review both the concerns and the potential upside, then make up your own mind with the 3 key rewards and 1 important warning sign.
Looking for more Zai Lab style investment ideas?
Do not stop with one ticker. Broader opportunity often sits just outside your current watchlist, and skipping that hunt could mean missing your next difference maker.
- Target potential mispricings by running your filters through the 33 high quality undervalued stocks tailored to financially stronger companies.
- Strengthen your downside protection by checking the 32 resilient stocks with low risk scores that screens for businesses with more resilient risk profiles.
- Get ahead of the crowd by scanning the 20 high quality undiscovered gems that highlight lesser known stocks with solid underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com