
Is IDACORP (IDA) Undervalued As Its Dividend Update Meets A Richer P E?
IDACORP (IDA) announced a quarterly dividend of US$0.90 per share, payable on November 30, 2026. The ex dividend and record dates are November 5, which matters for timing your income eligibility.
IDACORP’s latest dividend update lands after a steady rebound in the share price, with a 1-month share price return of 5.11% and an 8.64% share price return year to date. This comes even though the 3-month share price performance declined 5.14% and the 1-year total shareholder return sits at 3.03%. Meanwhile, the 3-year total shareholder return of 61.88% and 5-year total shareholder return of 53.50% point to momentum that has built over a longer stretch rather than in a straight line.
Scan beyond IDACORP and identify other income-focused utilities with resilient balance sheets using our curated list of solid balance sheet and fundamentals (25 results) for your watchlist.
For IDACORP, the latest rebound could signal confidence in the underlying utility business or simply a mood shift in a choppy year. The next step is to see which story the current valuation supports.
Most Popular Narrative: 12% Undervalued
Compared with IDACORP’s last close at $138.30, the most followed thesis pins fair value near $157.33. This estimate is based on a 7.24% discount rate and detailed load, capital spending, and regulatory assumptions that anchor that higher figure.
Massive planned capital investments, with IDACORP expecting to spend between US$1.3b and US$1.5b on CapEx in 2026 and around US$7b from 2026 to 2030 on generation, storage and transmission projects such as B2H and SWIP North, are forecast to drive rate base from about US$5.3b in 2025 to around US$11b by 2030 and increase regulated earnings.
See why 4 investors see IDACORP as 12% undervalued.
Result: Fair Value of $157.33 (UNDERVALUED)
Still, the IDACORP story can break if hydropower volumes stay weak or if regulators push back on recovering that US$7b CapEx plan through rates.
Find out about the key risks to this IDACORP narrative.
Another Angle On IDACORP’s Valuation
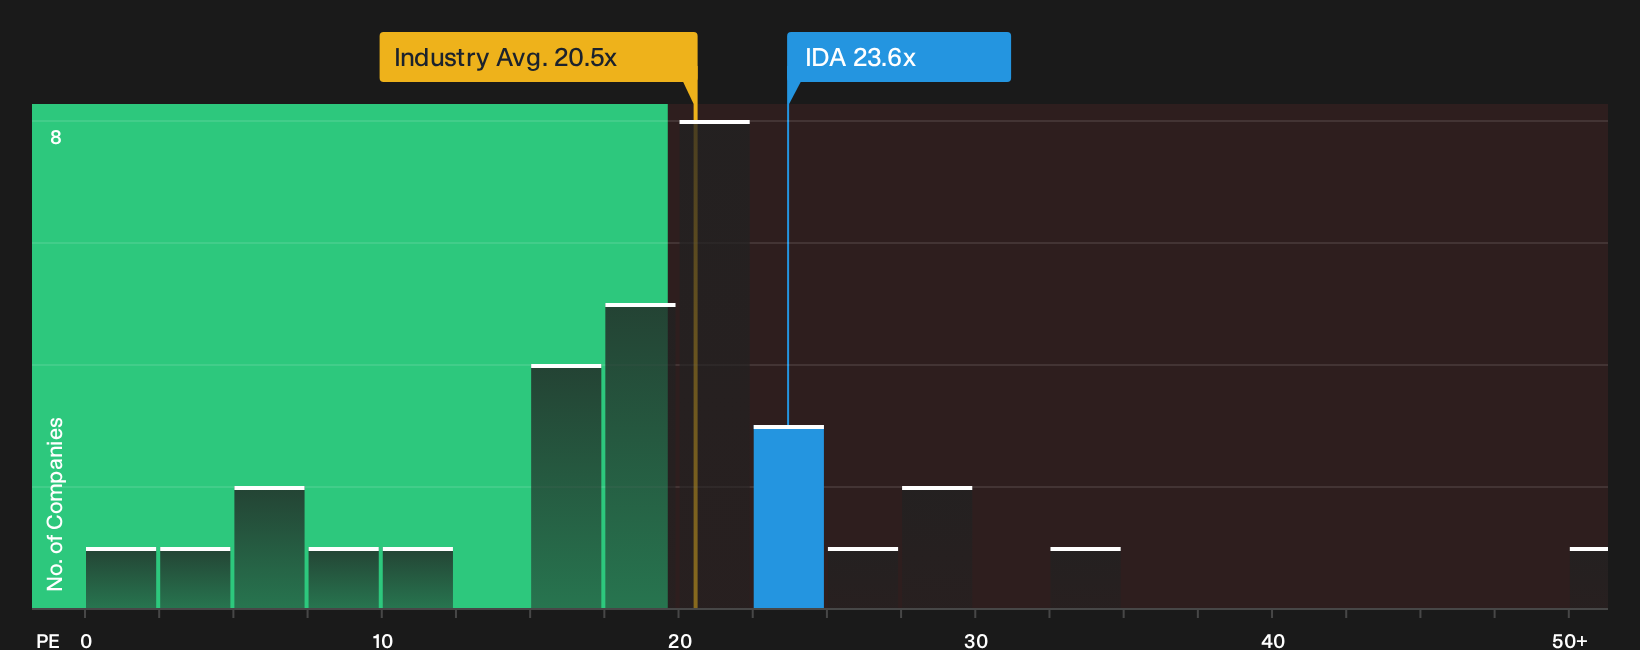
That 12% upside story hinges on analyst fair value assumptions, yet the current P/E of 23.6x already sits above the US Electric Utilities sector at 20.5x and above IDACORP’s own fair ratio of 20.1x. That gap points to valuation risk rather than a clear bargain. Which signal do you treat as more important?
To see how this richer P/E compares in detail against the sector and that fair ratio path the market could move toward, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around IDACORP’s value can make the story feel unresolved, so move fast, pull apart the numbers yourself and test both sides of the argument. To weigh the upside optimism against the concerns that keep showing up in the data, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond IDACORP?
Do not stop with IDACORP. Use the same disciplined mindset to scan fresh opportunities, compare strengths quickly and keep your watchlist packed with quality options.
- Target dependable income by focusing on businesses paying stronger yields and solid cash distributions through the 8 dividend fortresses.
- Hunt for quality at a reasonable price by checking companies that screen as attractively priced on fundamentals using the 33 high quality undervalued stocks.
- Prioritize capital preservation by reviewing resilient businesses that carry lower overall risk scores through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com