
How Declared Dividend Will Impact Costco Stock Investors
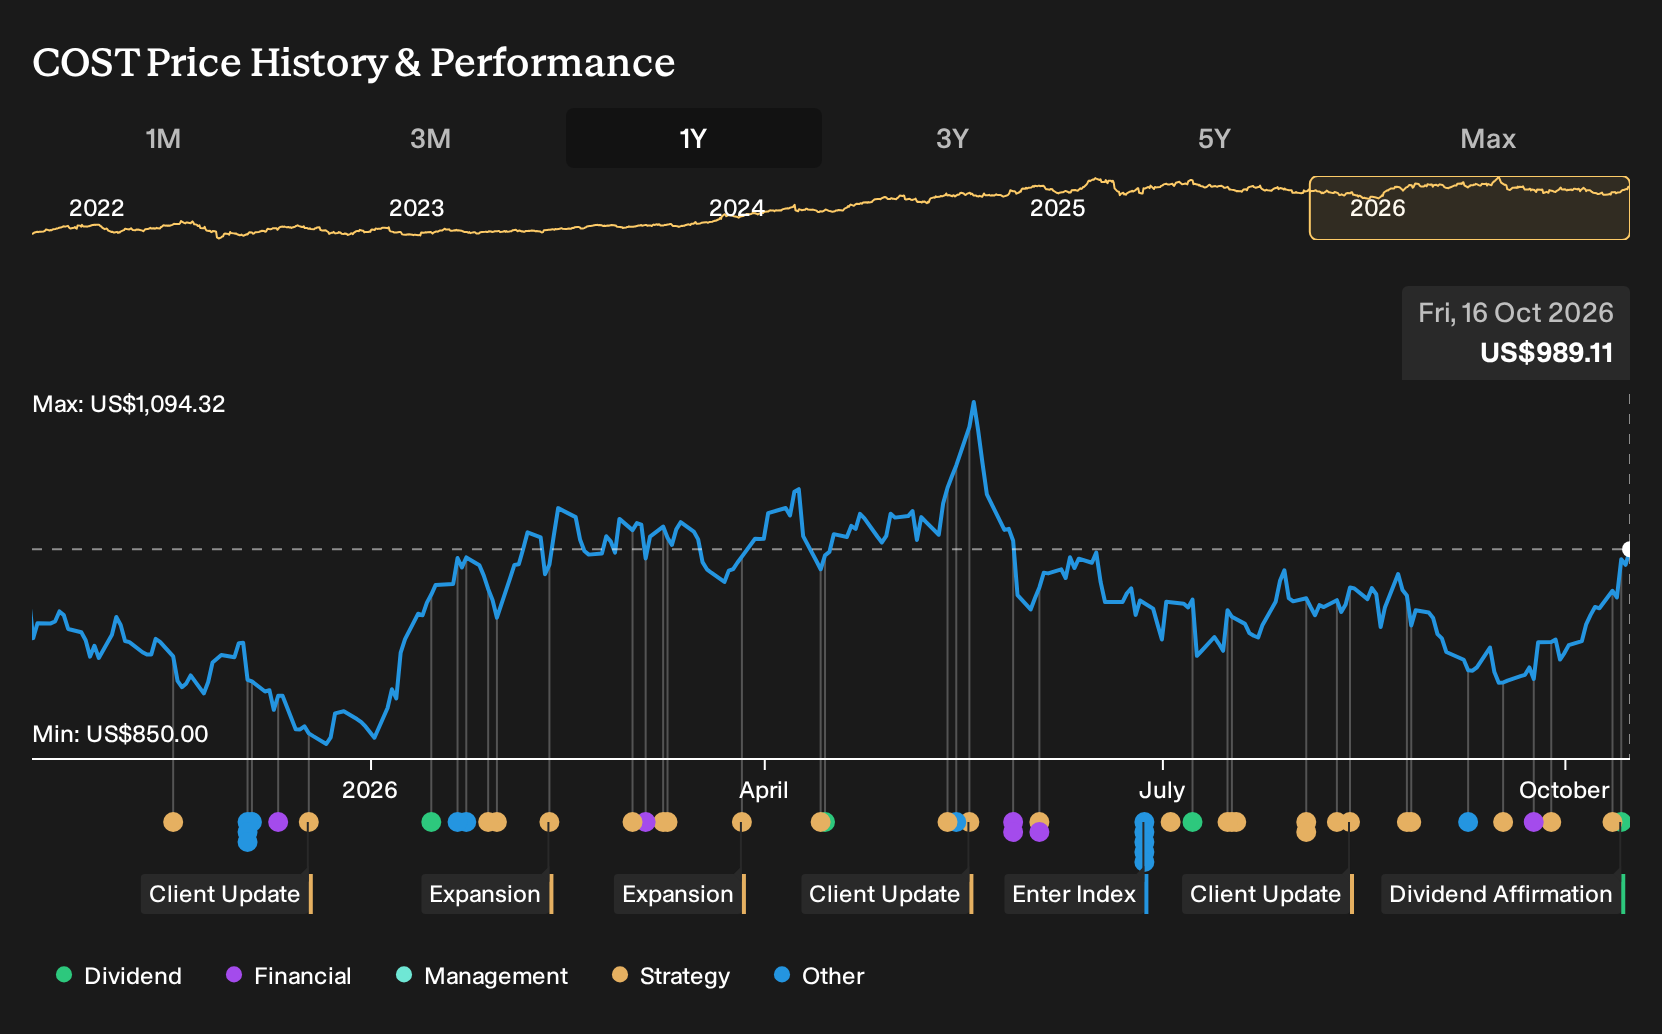
- Costco Wholesale recently reported September net sales of US$30.02b compared with US$26.58b a year earlier and affirmed a quarterly dividend of US$1.47 per share, payable on November 13, 2026 to shareholders of record on October 30, 2026.
- The addition of Hohem’s iSteady M7 AI tracking smartphone gimbal at a discounted member price highlights how Costco Wholesale uses curated, higher ticket items to deepen member engagement alongside core bulk staples.
- We will look at how Costco Wholesale's investment narrative is influenced by the confirmed US$1.47 dividend ahead of the holiday season.
Scan how Costco Wholesale’s membership model compares with other resilient retailers by jumping into a curated list of 32 resilient stocks with low risk scores that aim to keep portfolio swings in check.
Costco Wholesale Investment Narrative Recap
To own Costco Wholesale, you need to believe the membership model, warehouse expansion plan and ancillary services can keep pulling shoppers into stores and onto the app even as membership growth has slowed. The key near term swing factor is whether strong September net sales of US$30.02b around the holiday setup keep traffic and ticket size resilient.
The biggest operational risk right now is that softer member additions and any regulatory pressure, particularly around beef pricing, start to squeeze margins just as capital spending rises toward more warehouses and digital projects. The confirmed US$1.47 dividend looks supportive but does not materially change that risk reward equation.
The dividend affirmation on October 14, with a US$1.47 quarterly cash payout set for November 13 to holders of record on October 30, is the announcement most tied to this moment. For current Costco Wholesale shareholders, it confirms the board’s willingness to keep returning cash while the business funds heavier capital expenditure and digital initiatives.
For you as an investor, the more interesting angle is how that regular dividend interacts with Costco Wholesale’s catalysts such as warehouse openings, third party delivery growth and higher margin ancillary services. Execution against those projects, along with managing foreign exchange and antitrust scrutiny, is likely to matter far more to the long term outcome than this specific payout.
Costco Wholesale's narrative projects US$377.5b revenue and US$12.2b earnings by 2029. This aligns with analyst expectations of 7.6% yearly revenue growth and implies an earnings increase of about US$3b from US$9.2b today.
Uncover why Costco Wholesale's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on digital margin pressure rather than membership resilience. The most pessimistic Costco Wholesale analysts were pencilling in revenue of about US$365.1b and earnings of US$11.8b by 2029 before this dividend and Hohem launch, which is materially softer than consensus. That gap shows how widely opinions can differ, so it makes sense to compare several narratives and decide which assumptions you find more reasonable as new information comes through.
Explore 12 other Costco Wholesale fair value estimates, including one that suggests as much as 43% downside from the current price!
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Costco Wholesale research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Costco Wholesale. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Costco Wholesale's overall financial health at a glance.
Looking for more investment ideas beyond Costco Wholesale?
Once you have a view on Costco Wholesale, casting a wider net can help balance risk and uncover opportunities that fit different roles in your portfolio. The Simply Wall St Screener can be a useful way to filter for businesses that match the financial traits you care about most.
- If capital preservation is high on your list, start with a 32 resilient stocks with low risk scores that aim to keep drawdowns more manageable when markets turn choppy.
- For investors hunting for value, scan a 33 high quality undervalued stocks to see which businesses combine solid fundamentals with prices that appear out of step with their underlying metrics.
- If income is your priority, focus on a 8 dividend fortresses that aim to pair higher yields with balance sheets that look better equipped to support ongoing payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com