
Is Premium P E Valuation Altering The Investment Case For Weis Markets Stock?
- Weis Markets is under fresh scrutiny after investors highlighted that its shares trade at a P/E ratio above both industry and peer averages, raising questions about how current earnings and operations line up with that premium.
- The debate now focuses on whether Weis Markets' profit quality, cost discipline, and balance sheet strength provide enough support for that higher valuation multiple.
- We will look at how Weis Markets' investment narrative is affected by the debate over its premium P/E valuation and earnings strength.
What Is Weis Markets' Investment Narrative?
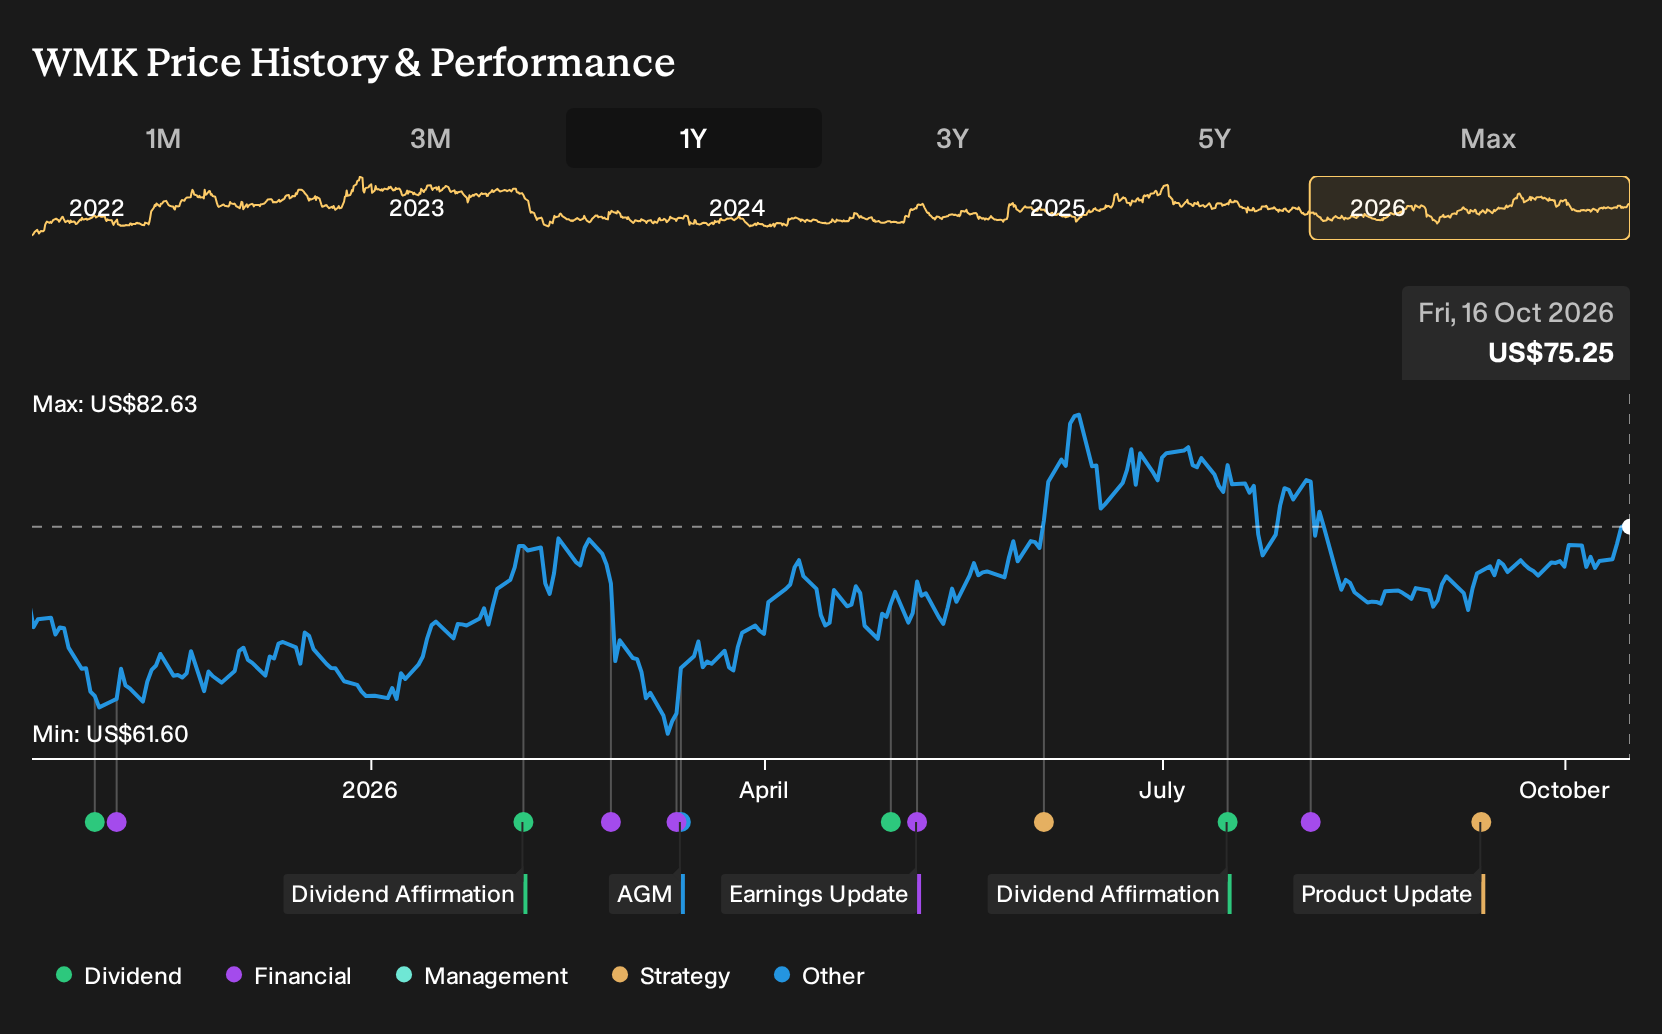
To own Weis Markets, you have to be comfortable with a grocery chain that leans on disciplined operations, steady customer demand, and a capital intensive store base rather than high headline growth. Earnings quality is flagged as high, the balance sheet supports a 1.81% dividend, and returns over 5 years have been solid in absolute terms. The recent focus on its premium P/E multiple simply spotlights an existing tension between a value score of 2, its above peer P/E of 18.7x, and slower historical earnings trends.
In the short term, that valuation debate does not change what matters most for Weis Markets. Day to day execution on pricing, mix, and cost control still drives outcomes in a business where net profit margin sits around 2%. Earnings have declined by 3.9% per year over 5 years and slipped 1.8% in the most recent year, so any wobble in demand or expenses can hit a relatively thin margin quickly. With the stock already under scrutiny after a strong year to date move, the real swing factor is whether operations can simply hold the line rather than...
Yet beneath that seemingly conservative story sits...
There's only one way to know the right time to buy, sell or hold Weis Markets. Head to Simply Wall St's company report for the latest analysis of Weis Markets's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Weis Markets research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weis Markets. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weis Markets' overall financial health at a glance.
Looking For More Ideas Beyond Weis Markets?
If the debate around Weis Markets has you reassessing where you want earnings strength and valuation to meet, it can help to scan a broader watchlist and see how other businesses line up on quality, value, and resilience.
- If you want stronger value support behind current earnings, scan a curated set of companies with compelling valuations through 33 high quality undervalued stocks.
- For investors who prize balance sheet resilience and fundamentals first, filter the market using a focused list of solid balance sheet and fundamentals (25 results).
- If income is a priority, use a targeted screener to zero in on higher yielding payers with sturdier profiles via 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com