
Should AI Cost Saving Research Require Action From Nemetschek (XTRA:NEM) Investors?
- Nemetschek’s subsidiary Bluebeam recently published research on AI driven cost savings in construction, spotlighting potential efficiency gains for contractors and project owners.
- The study highlights how Nemetschek’s AI tools could shift customer focus from one off licenses to higher value recurring workflows that are tightly linked to realized savings.
- We will examine how Nemetschek’s investment narrative is reshaped by Bluebeam’s AI cost saving research and the debate over premium valuation.
Scan beyond Nemetschek and Bluebeam’s AI cost saving angle by reviewing a curated set of construction and infrastructure beneficiaries in our 55 AI infrastructure stocks.
Nemetschek Investment Narrative Recap
To own Nemetschek, you need to be comfortable with a software group leaning heavily into recurring revenue, AI features and construction focused tools, while carrying higher valuation multiples than many peers. In the short term, a key swing factor is how convincingly management can show that Bluebeam and the wider Build segment convert AI cost savings into stickier, higher value workflows.
On the risk side, the HCSS acquisition still hangs over the story, with about €450 million of extra net debt and no clear earnings accretion expected until 2028. The Bluebeam research does not change that funding load, so integration execution, interest costs and any weakness in Media and Entertainment remain the key pressure points.
The fresh Bluebeam study on AI driven cost savings is the announcement that ties closest to Nemetschek’s near term thesis. It directly touches the Build unit, which already contributes more than €500 million of revenue and is central to management’s ambition to scale Construct and Build activities toward the €1b mark with high recurring exposure.
For investors, the relevance is about proof points. If customers increasingly adopt Bluebeam’s AI heavy workflows and link them to measurable construction savings, that can support higher average revenue per user and justify the ongoing shift from one off licenses to subscription. Any gap between the promised efficiencies and what users actually see would limit that pricing power.
Nemetschek Consensus Expectations Behind the AI Story
Nemetschek’s AI pitch around Bluebeam arrives against a backdrop of fairly punchy analyst assumptions. Consensus models point to revenue expanding by 18.1% a year over the next three years, which is a demanding pace for any established software group and leaves limited room for operational missteps in the Build portfolio or with HCSS integration.
On profitability, forecasters are working with current earnings of €246.4 million and expect profit margins to move from 19.6% today to 21.0% in three years. That gap in margin, while modest on paper, relies on AI heavy workflows like Bluebeam Max and recurring Build revenue scaling cleanly without forcing Nemetschek to ramp up selling costs or discounting to drive adoption.
By 2029, the analyst playbook points to earnings of €435.4 million, which is roughly a €189 million step up from today’s level. The range around that figure is wide, with the most optimistic forecasts at €521.4 million and the most cautious at €329.6 million. Anyone leaning on this AI cost saving narrative needs to recognise that professional forecasters themselves do not agree on how far Nemetschek can push its model.
That earnings bridge sits inside a broader revenue picture. For you to line up with the consensus fair value estimates, Nemetschek would be generating about €2.1b of revenue in 2029 and still be priced on a P/E multiple of 27.9x those earnings, compared with 31.6x today and a lower current sector multiple of 16.8x for the GB software peer group.
The capital structure context also matters. Analysts are working with a discount rate of 6.8% to 6.83% and assume the share count stays flat over the next three years, so the heavy lifting in their models comes from revenue growth, margin progress and the AI linked Build contribution, not from financial engineering or aggressive buybacks.
Nemetschek's narrative projects €2.1b revenue and €435.4 million earnings by 2029. This requires 18.1% yearly revenue growth and about €189 million earnings increase from €246.4 million today.
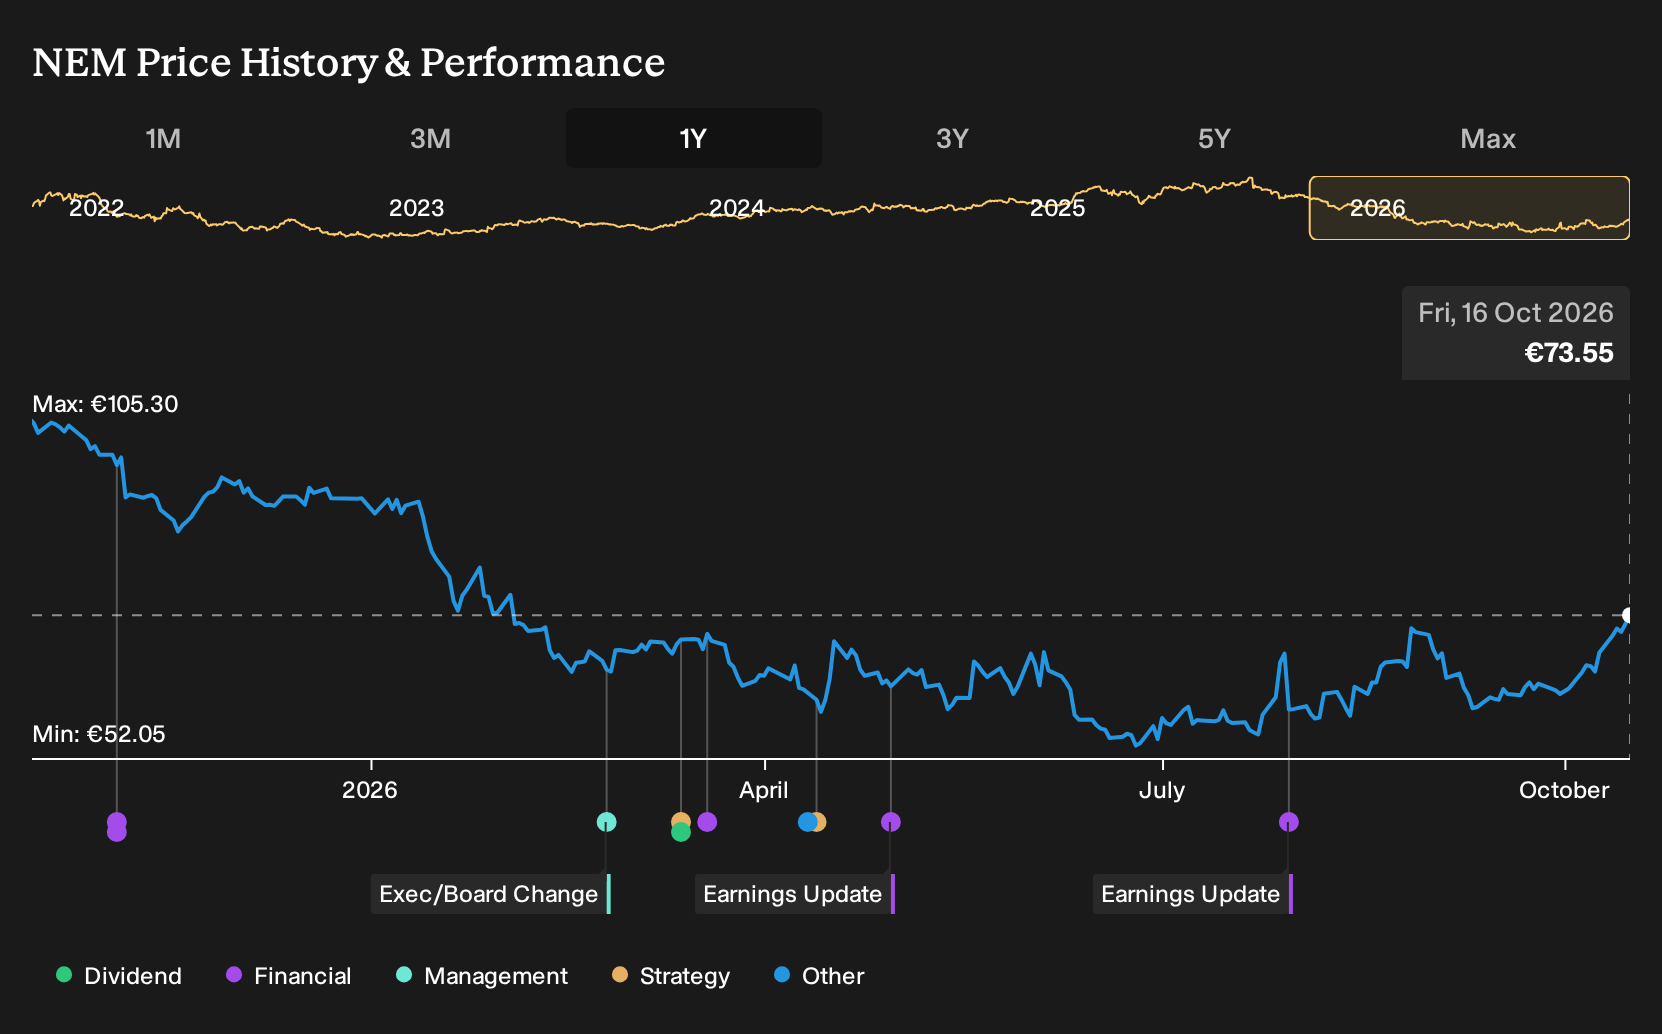
Uncover how Nemetschek's fair value indicates a 17% potential upside to its current price before that discount to Nemetschek’s shares starts to close.
Exploring Other Perspectives
For Nemetschek, the bullish twist is all about a more aggressive AI led Build ramp. The most optimistic analysts were already pencilling in €2.3b revenue and €520.2 million earnings by 2029, well above the baseline €2.1b and €435.4 million view. After Bluebeam’s cost saving study, you can expect those contrasting playbooks to evolve further.
Explore 3 other Nemetschek fair value estimates, including one that suggests as much as 110% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nemetschek research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nemetschek. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nemetschek's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nemetschek?
If you want to set Nemetschek in context, it helps to scan a wider field of potential candidates with different risk and income profiles. The Simply Wall St Screener can surface stocks that match the way you like to invest, whether you care most about value, resilience or future potential.
- For investors who want quality at a discount, compare Nemetschek with a 191 high quality undervalued stocks that currently screen well on both fundamentals and price.
- If capital preservation sits high on your list, weigh Nemetschek against a 231 resilient stocks with low risk scores that may offer lower volatility across market cycles.
- For those who want stronger balance sheets alongside Nemetschek, scan a list of solid balance sheet and fundamentals (203 results) and see which businesses fit your comfort zone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com