
Arm Holdings (ARM) Faces Qualcomm Verdict, Is The Pullback A Valuation Opportunity?
A Delaware jury verdict against Arm Holdings (NasdaqGS:ARM) over its long-standing Qualcomm architectural license now sits at the center of the story, with investors weighing legal pressure alongside newer data center collaboration efforts.
Arm Holdings has seen momentum cool sharply in recent weeks, with the share price falling 6.94% in the last day and down 21.38% over 90 days. Even so, the year-to-date share price return of 98.55% and 1-year total shareholder return of 32.83% still reflect a strong run driven by enthusiasm around its AGI CPU ambitions and prior gains.
Spot opportunities along the same theme by scanning our hand picked 55 AI infrastructure stocks, which could also be sensitive to shifts in Arm Holdings' data center and AGI CPU story.After a near 100% gain this year and a sharp pullback around the Qualcomm verdict, the open question on Arm Holdings is simple. Are investors still early on this AGI CPU and data center push, or are they already late to the story?
Most Popular Narrative: 47% Undervalued
Against a last close of $227.80, the most followed thesis on Arm Holdings leans on a narrative fair value of $430. This frames the recent pullback as a valuation debate rather than a broken story.
The catch is valuation. Arm is now being valued less like a normal semiconductor company and more like a future monopoly-like infrastructure layer for AI compute. The stock recently traded above $400 after a huge run, though it pulled back with the broader semiconductor selloff on July 13, when Arm fell 7.6% alongside other chip leaders.
See why 43 investors see Arm Holdings as 47% undervalued.
Result: Fair Value of $430 (UNDERVALUED)
Still, that story can change quickly if the Qualcomm license dispute escalates, or if regulators push back on how Arm Holdings balances AGI CPU ambitions with its role as a neutral IP supplier.
Find out about the key risks to this Arm Holdings narrative.
Another Take On Arm Holdings’ Valuation
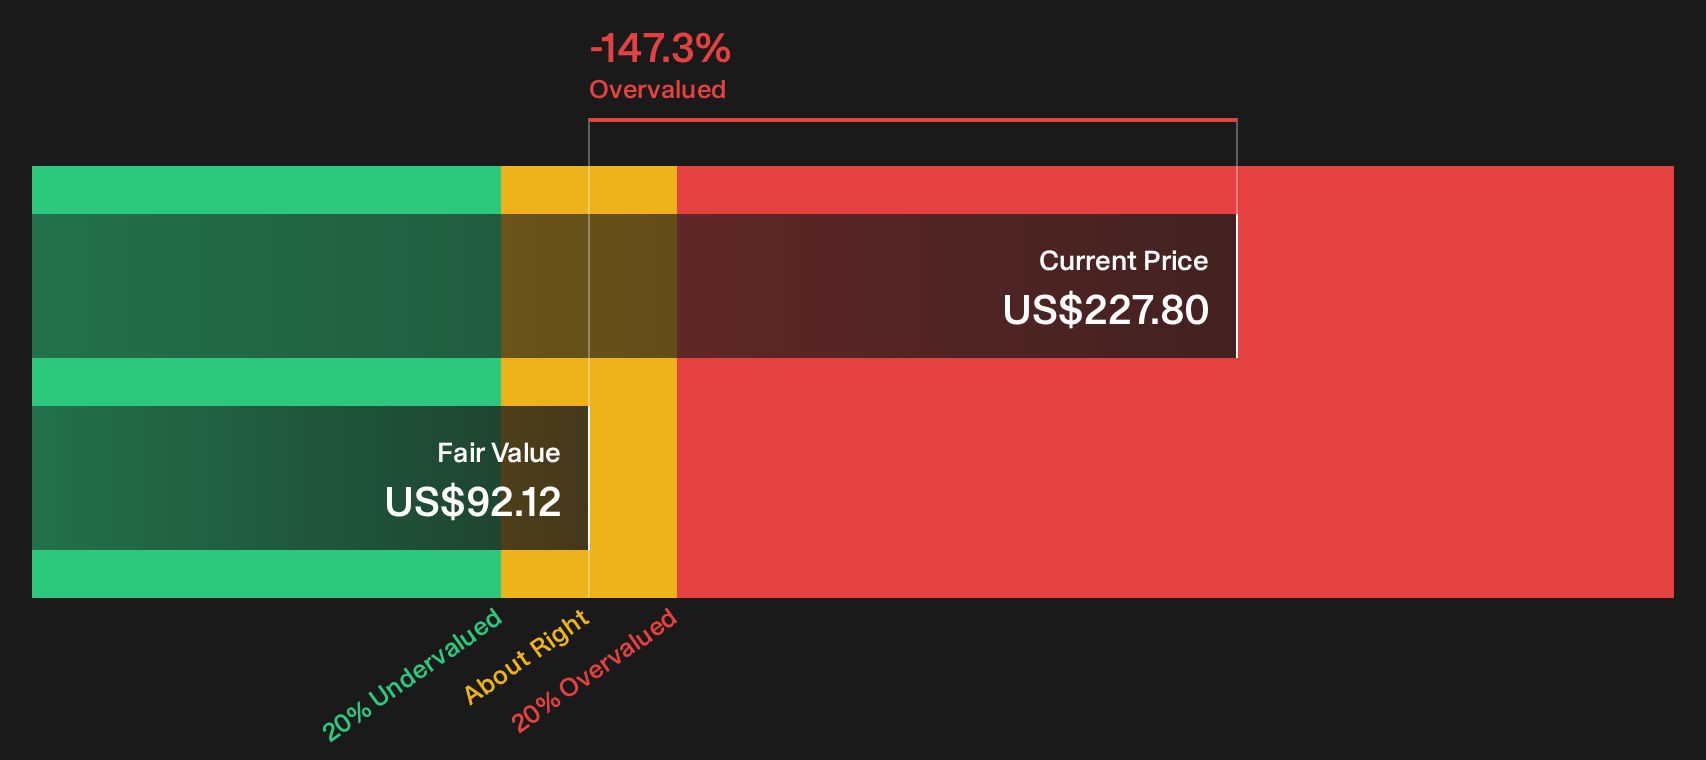
That AGI CPU narrative leans heavily on a $430 fair value, yet the SWS DCF model paints a very different picture. On that cash flow view, Arm Holdings at $227.80 screens as expensive versus an estimated future cash flow value of $92.12. Which story do you put more weight on?
For a closer look at how this cash flow view is built, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Conflicted by Arm Holdings’ rally and the legal overhang? Act quickly, review the data for yourself, then weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Arm Holdings?
Do not stop your research with Arm Holdings. Use this pullback as a prompt to widen your watchlist and compare other opportunities side by side.
- Target reliable income streams by scanning for companies that behave like potential income anchors through the 8 dividend fortresses.
- Hunt for quality at a lower price by reviewing the 33 high quality undervalued stocks that combine fundamentals with attractive valuations.
- Prioritise resilience by focusing on businesses screened in the 32 resilient stocks with low risk scores that aim for steadier performance and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com