
Is Akeso (SEHK:9926) Undervalued On Its Phase III Colon Cancer Trial News?
Akeso (SEHK:9926) has put fresh attention on its core oncology program after dosing the first patient in a Phase III trial of cadonilimab for perioperative MSI-H or dMMR colon cancer.
Akeso’s latest oncology milestone lands after a volatile stretch for the shares, with a 7 day share price return down 16.32% and a year to date share price return down 19.42% from the current HK$91.3 level. Even though the 3 year total shareholder return is up 141.85%, which keeps long term momentum intact, this comes despite a 1 year total shareholder return that has declined 25.53% and recent follow on equity offering news adding short term pressure.
Spot 126 healthcare AI stocks that, like Akeso, are trying to turn high-impact clinical programs into the next wave of oncology and immunology breakthroughs.So is the recent drop in Akeso mainly a verdict on dilution and risk appetite, or a temporary swing in sentiment around a business still leaning hard into high cost, high potential oncology assets? The valuation work starts there.
Most Popular Narrative: 41% Undervalued
Against the last close at HK$91.3, the most followed narrative pegs Akeso’s fair value much higher at about HK$154, which puts the recent drawdown in a very different light and turns the Phase III pipeline into the central swing factor.
The company's R&D pipeline, including advanced bispecific antibodies and ADC candidates, provides a foundation for long-term growth. This is described as setting the stage for potential increases in net margins as products move from development to commercialization. Akeso's comprehensive sales force and manufacturing capabilities, alongside anticipated growth in hospital coverage from 1,000 to 2,000, are cited as supporting a scalable commercial operation that may improve operational efficiencies and contribute to enhanced net margins.
See why 3 investors see Akeso as 41% undervalued.
Result: Fair Value of HK$154 (UNDERVALUED)
Still, the fair value story depends on Akeso turning a loss of CN¥967.2 million into sustainable profits while managing its heavy reliance on cadonilimab and ivonescimab.
Find out about the key risks to this Akeso narrative.
Another View: What Akeso’s Sales Multiple Is Saying
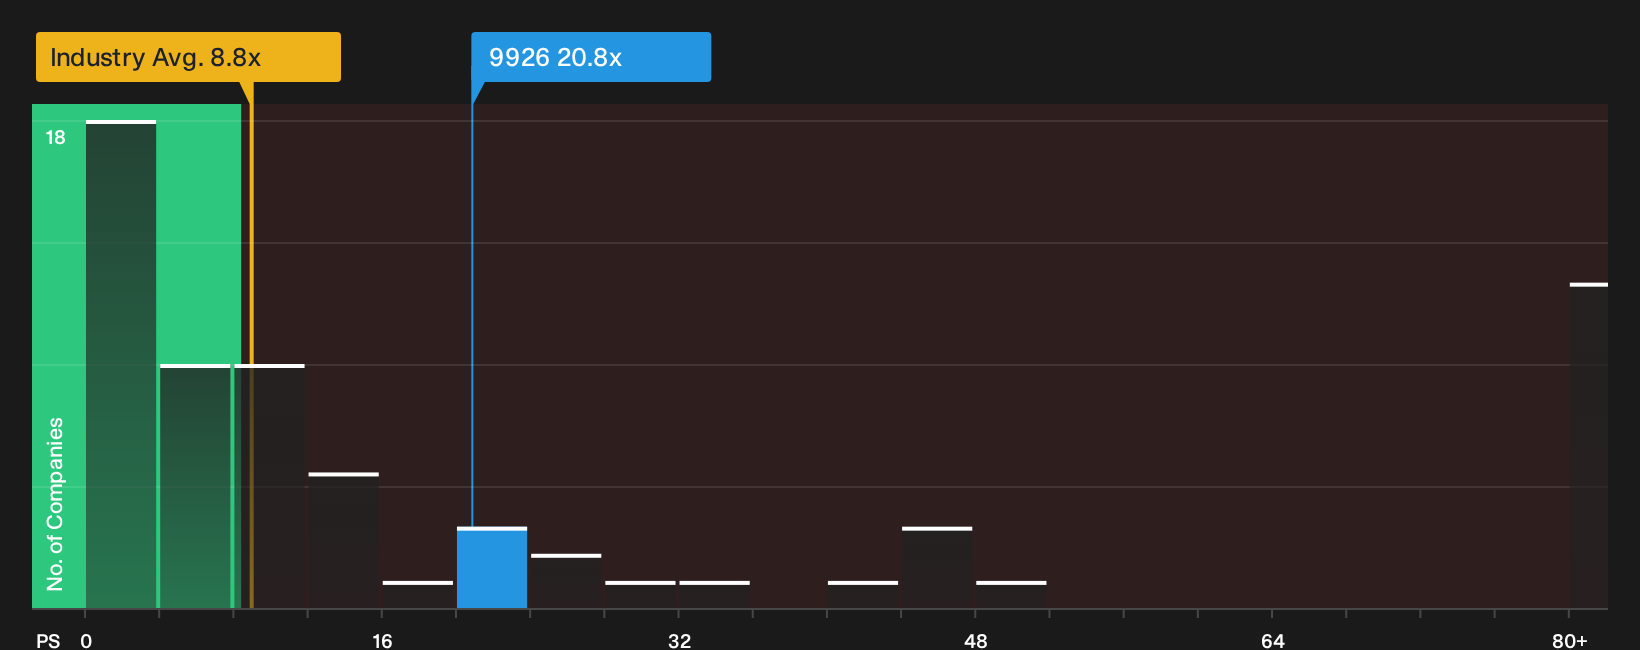
That HK$154 fair value narrative leans on future cash flows, yet Akeso currently trades on a P/S of 20.8x while the Hong Kong biotech group sits around 8.8x and the fair ratio is 12.8x. The gap points to richer expectations on revenue today. Which story do you trust more?
For a closer look at how those sales multiples stack up against what the fair ratio suggests the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Akeso is clearly split, which is exactly why fresh data matters more than headlines. Act quickly and review both the bear points and the 2 key rewards.
Looking for more investment ideas beyond Akeso?
If Akeso has you thinking harder about risk, reward, and timing, then it is worth lining up a few more targets that could sharpen your watchlist.
- Target resilient compounding potential by scanning a 192 high quality undervalued stocks that blends quality fundamentals with prices that may not fully reflect underlying business strength.
- Lock in income-focused opportunities by reviewing a 218 dividend fortresses that screens for higher yielding payers with the balance sheets to support ongoing distributions.
- Lean into durability and stability by checking a 231 resilient stocks with low risk scores built to surface businesses with lower risk scores before the crowd pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com