
Shell And 2 British Undervalued Stocks To Own
Profit warnings from UK listed firms have climbed to a two year high as rising costs and policy uncertainty squeeze margins, which puts reliable cash generation under a brighter spotlight. When earnings guidance feels fragile, businesses that generate steady cash yet trade at discounted prices can appear particularly notable. This article highlights three British stocks that currently screen as undervalued on future cash flows.
The three examples below are only a sample of the ideas that screen well on discounted cash flows. The full filter currently surfaces 24 more UK listed companies with similarly compelling cash generation stories that are not covered here.
If you want to identify and analyze those extra opportunities alongside your own criteria, head straight into the Undervalued Stocks Based On Cash Flows screener.
Shell (LSE:SHEL)
Overview: Shell is a global energy group whose oil, gas, refining and fuels marketing operations generate significant cash that anchors this undervalued cash flow story.
Operations: Shell earns most of its revenue from Marketing at about $135b and Chemicals and Products at roughly $132b, alongside sizeable Integrated Gas and Upstream activities.
Market Cap: £225.1b
Shell matters for this cash flow focused screen because its traditional oil, gas and refining engines still generate large, near-term cash. Newer renewables and energy solutions sit alongside rather than replacing those cash generators.
"With an LNG portfolio exceeding 60 million tons and unparalleled trading capabilities, Shell is the company that benefits most from the volatility in the global gas market."
What happens to those cash flows if a single key pressure on future LNG margins and trading spreads shifts against current expectations?
If that pressure point worries you, read the full narrative for Shell to see how Shell’s cash engine, capex choices and policy risks could be decoupling from headline sentiment.
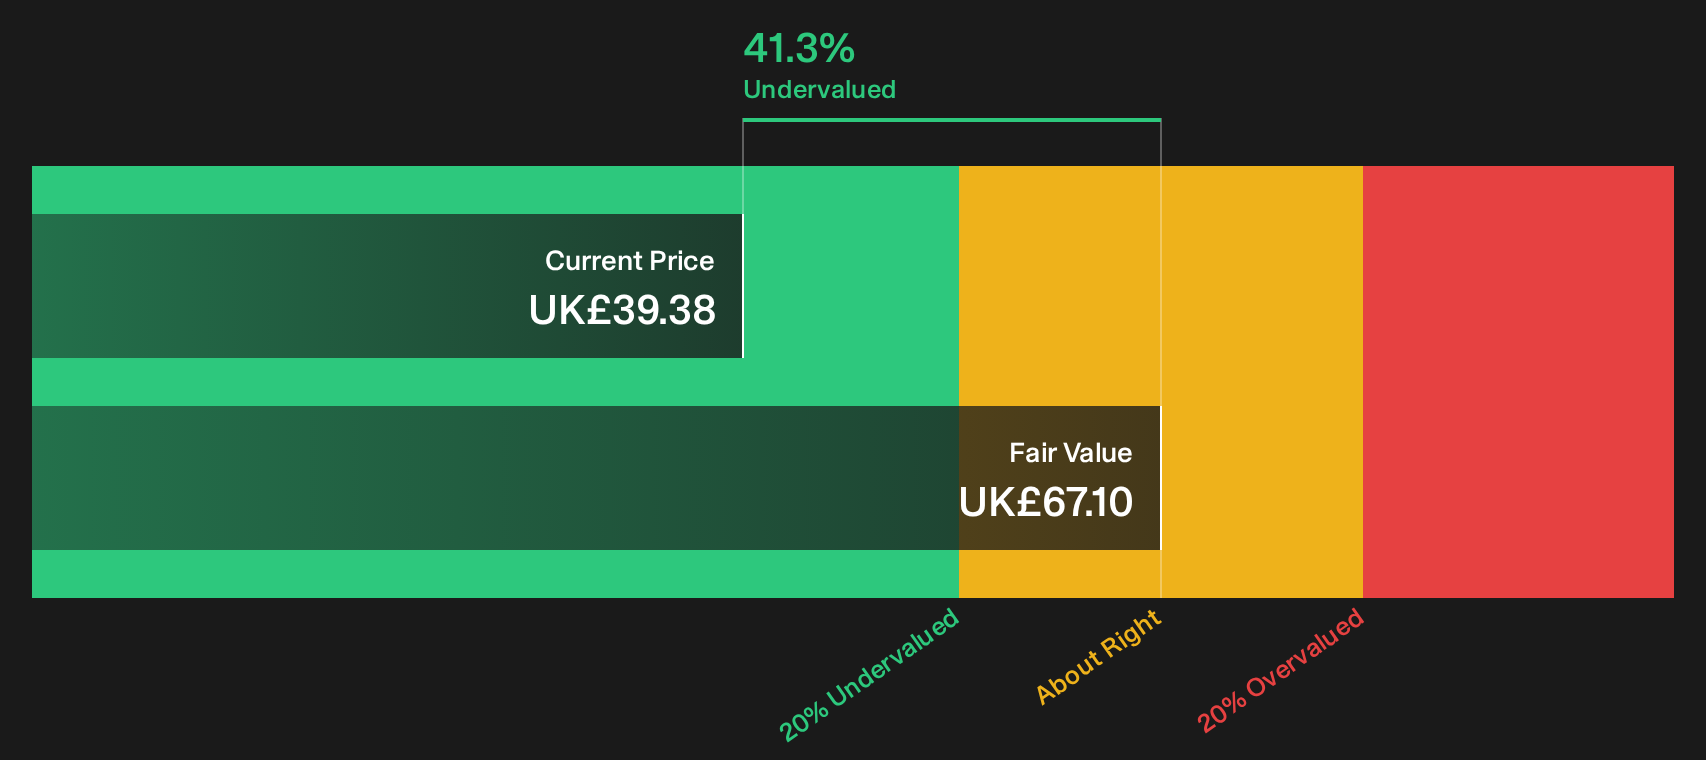
Premier Foods (LSE:PFD)
Overview: Premier Foods manufactures branded ambient grocery and sweet treats such as Bisto, Mr Kipling and Ambrosia that generate steady supermarket led cash flows.
Operations: Premier Foods generates about £860 million of Grocery revenue and £315 million of Sweet Treats revenue, largely from £1.1b of United Kingdom sales.
Market Cap: £1.7b
Premier Foods matters for a cash flow focused screen because its long running cupboard staples and cake brands throw off relatively steady earnings that can be assessed against DCF fair value rather than relying on big speculative growth swings.
"Planned step up in annual CapEx to £55 to £60m in FY27, directed at automated cake lines, insourced sauce capacity, new process plants and energy projects such as efficient boilers and solar arrays, is intended to lower unit costs and improve factory recovery which can support gross margin and trading profit progression."
What happens to that branded cash engine if one key assumption about how efficiently those new assets convert future sales into profit proves too optimistic.
If that efficiency risk is on your mind, read the full narrative for Premier Foods to see how Premier Foods’ cash generation, debt profile and pricing power could be quietly accelerating.
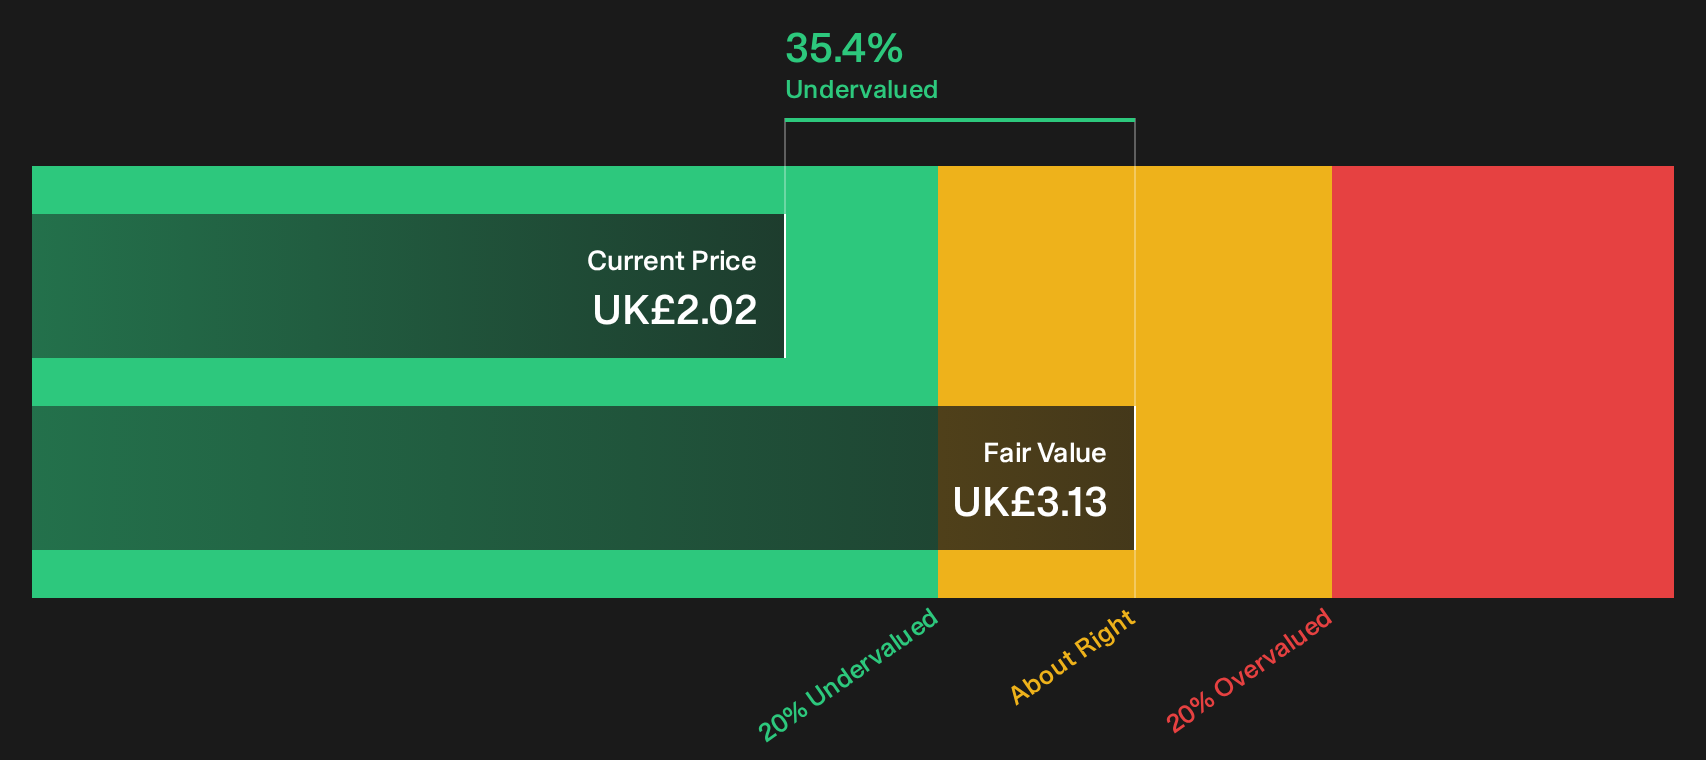
Gamma Communications (LSE:GAMA)
Overview: Gamma Communications delivers cloud-based voice, video and contact-centre subscriptions that create recurring cash flows for business customers across the UK and Europe.
Operations: Gamma Communications generates about £136 million from Enterprise and £121 million from Germany SME, within roughly £463 million of United Kingdom revenue and £196 million across Europe and beyond.
Market Cap: £984 million
Gamma Communications fits this cash flow focused screen because its cloud and VoIP subscriptions convert long term customer contracts into repeatable income that can be valued against discounted future cash rather than short term headline moves.
"Large parts of the business communications market in Germany are still using legacy on premise systems, with only a small portion of that market currently on cloud solutions. This gives Gamma’s existing presence and proprietary platforms such as STARFACE and Placetel a long runway to grow cloud seats and recurring revenue as adoption continues over many years."
What happens to Gamma Communications’ cash rich subscription base if one key shift in competitive pricing or customer churn cuts deeper than expected?
If that kind of hit to cash conversion worries you, read the full narrative for Gamma Communications to see whether pricing power, churn and acquisitions are quietly accelerating Gamma Communications’ story.

Seeking Fresh Alternatives Beyond These Three
Fresh ideas move first. Once momentum builds, prices can be flying before the crowd catches on. Scan these under the radar for now opportunities while it matters and act now.
- Spot steady cash engines and insulation from weak balance sheets by scanning the list of solid balance sheet and fundamentals (9 results) that filters for financial resilience before momentum headlines catch up.
- Ride potential breakout trends in automation by sweeping through the curated 92 robotics and automation stocks packed with businesses tied to factories, warehouses and next generation industrial efficiency.
- Track where power grid upgrades and electrification momentum could concentrate by scanning the hand picked 42 power grid technology and infrastructure stocks focused on transmission, hardware and critical network technology.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com