
Glaukos (GKOS) Could Be 4% Below Fair Value After Trial Data
Glaukos (GKOS) moved back into focus after fresh clinical data on its glaucoma and corneal therapies, as iDose TR and Epioxa each produced positive trial readouts that sharpen the story around the company’s ophthalmology pipeline.
Glaukos has ridden a strong upswing over 2026, with the share price at US$164.84 after a year-to-date share price return of 48.88%. The 1-year total shareholder return of 107.42% and 5-year total shareholder return of 266.15% suggest momentum has been building around the story as these fresh iDose TR and Epioxa data points land.
Scan beyond Glaukos and see how other ophthalmology and medical-device players with strong momentum and clinical pipelines stack up in our hand picked screener of 33 healthcare AI stocks.
Glaukos now trades near record territory after that sharp move, which raises a simple tension for investors. Is this just the warm up act, or has most of the easy upside already been spent?
Most Popular Narrative: 4% Undervalued
Glaukos screens as modestly undervalued in the most widely followed valuation narrative, with a fair value of $172 set against the last close at $164.84. This puts the spotlight on whether the pipeline can carry the extra weight of rising costs and reimbursement scrutiny.
The main factor that must go right is that iDose TR, Epioxa and the broader multi-franchise pipeline offset higher operating expenses and any reimbursement constraints, allowing Glaukos to convert high gross margins into durable operating leverage and future cash-flow breakeven.
The current figures around raised 2026 net sales guidance, high gross margins and an expanded ophthalmic pipeline suggest that Glaukos' fairly valued share price already reflects continued execution on interventional glaucoma and corneal therapies, with additional upside tied to successful reimbursement and new product launches.
See why 2 investors see Glaukos as 4% undervalued.
Result: Fair Value of $172 (UNDERVALUED)
Still, two things could flip that script fast, faster than many models allow for, if iDose TR adoption outpaces cautious expectations and if Epioxa corneal volumes ramp cleanly through reimbursement shifts.
Find out about the key risks to this Glaukos narrative.
Another View: Glaukos Looks Expensive On Sales
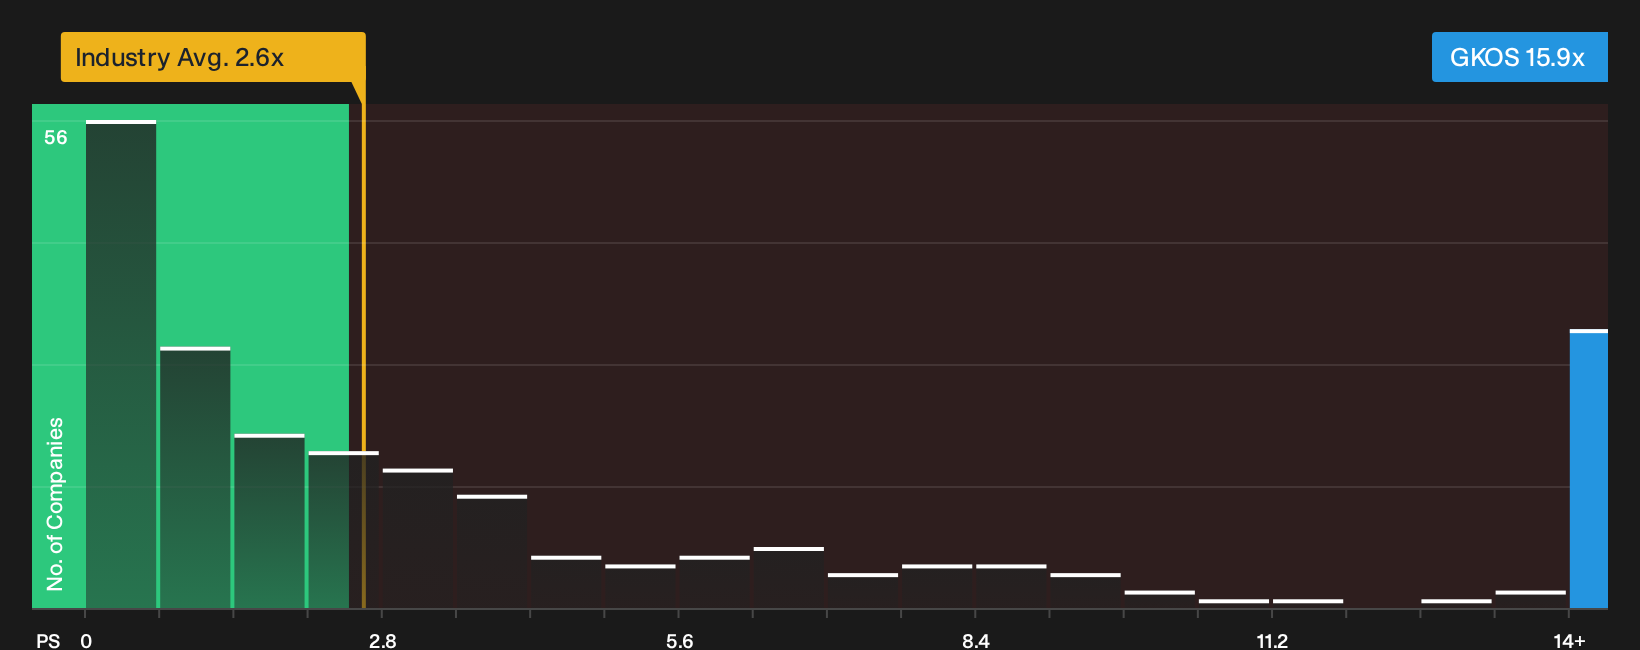
Glaukos appears modestly undervalued at a $172 fair value in the current narrative, yet the price tag tells a different story when you look at sales. The stock trades on a P/S ratio of 15.9x, compared with 2.6x for the US Medical Equipment industry and 4x for peers, while the fair ratio is 9x. That gap suggests investors are paying a heavy premium for growth and execution, so the question becomes whether you are comfortable underwriting that much expectation into the current price.
To pressure test those expectations against what the numbers imply, take a closer look at how that price to sales premium fits into the broader valuation story for Glaukos with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Glaukos can create noise. Move fast, unpack the full picture, and weigh both sides with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Glaukos?
If Glaukos has your attention, do not stop here. The next strong addition to your watchlist could already be lining up in plain sight.
- Spot potential turnaround stories early by scanning the 14 elite penny stocks with strong financials. These pair smaller size with stronger balance sheets and fundamentals than many expect.
- Hunt for quality at a marked-down tag by running through the 33 high quality undervalued stocks. These blend solid cash flows with robust financial footing.
- Build a steadier portfolio core by focusing on the 32 resilient stocks with low risk scores. These score well on resilience while still aiming for meaningful upside potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com