
WEC Energy Group (WEC) Files New Share Plan On Fair Value Debate
WEC Energy Group (WEC) has put a fresh capital plan on the table. The utility filed a US$208.12 million shelf registration for 2,000,000 common shares tied to its dividend reinvestment plan.
Recent price action has been quietly positive for WEC Energy Group, with a 1-day share price return of 2.52% and a 30-day share price return of 5.37% lifting the stock to US$108.71. The 1-year total shareholder return is down 4.32%, while the 3-year total shareholder return is 50.29%. This points to longer term momentum that contrasts with the softer past year.
The fresh shelf registration sits alongside a recently affirmed quarterly dividend of US$0.9525 per share and comes after an uptick in insider selling. Recent gains may reflect investors weighing income stability and capital plans against shifting views on risk.
Scan beyond WEC Energy Group and compare this capital plan with other regulated utilities by reviewing our hand picked 42 power grid technology and infrastructure stocks poised to benefit from grid and infrastructure investment themes.
WEC Energy Group has the profile of a steady regulated utility and a share price that just moved higher on fresh capital news. The real tension now is simple: Are you paying up for that quality or not?
Most Popular Narrative: 9% Undervalued
WEC Energy Group closed at $108.71 against a widely followed fair value view of $118.91. This frames the latest capital move as part of a bigger long term earnings and dividend story.
The planned US$37.5b capital program from 2026 to 2030, focused on regulated gas infrastructure, renewables, storage and transmission, is expected to expand WEC Energy Group’s regulated asset base and drive higher revenue and net income as these assets are placed in service.
The Very Large Customer tariff in Wisconsin, with its defined return on equity of 10.48% to 10.98% and 57% equity layer, creates a framework for future large load projects that can add to regulated earnings and support margin stability as more data center infrastructure is built.
See why 14 investors see WEC Energy Group as 9% undervalued.
Result: Fair Value of $118.91 (UNDERVALUED)
Still, the WEC Energy Group story can break if regulators tighten returns in Wisconsin, or if Very Large Customer and data center projects slow materially.
Find out about the key risks to this WEC Energy Group narrative.
Another View: What WEC Energy Group’s P/E Is Telling You
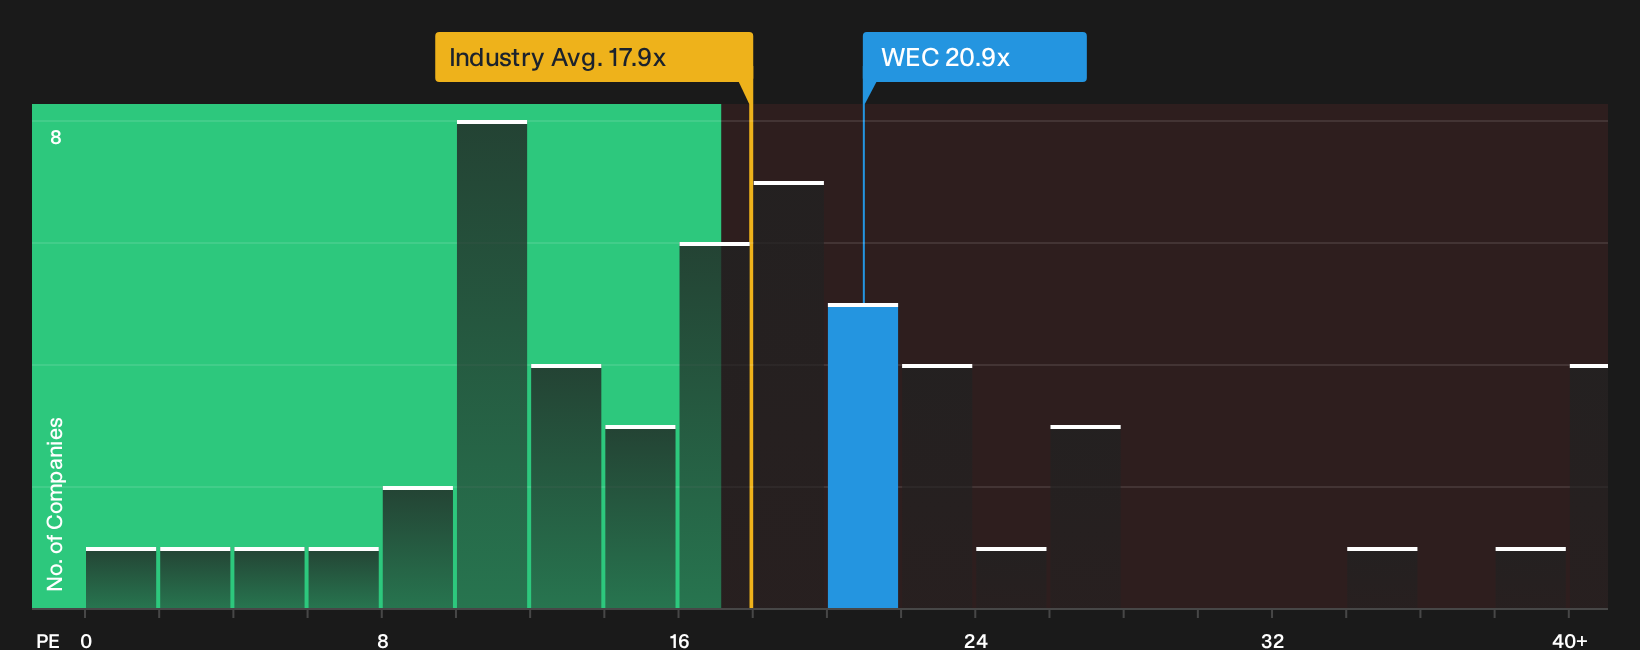
The first narrative says WEC Energy Group looks about 2.2% below fair value. The P/E ratio tells a tougher story. At 20.9x earnings, the stock trades above its 20.7x fair ratio, ahead of the 17.9x global integrated utilities average and the 18.9x peer group. That premium suggests less margin for error if growth or regulation disappoints.
It leaves a simple question for investors sizing up WEC Energy Group: Is that higher multiple a comfort premium worth paying, or a valuation risk if sector sentiment turns?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the WEC Energy Group story so far. Act while the data is fresh, review the numbers yourself, then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WEC Energy Group?
If WEC Energy Group has your attention, do not stop here. Expand your watchlist with fresh ideas that match the way you think about risk and return.
- Target stronger long term value potential by scanning a 33 high quality undervalued stocks that pairs quality fundamentals with prices that may not fully reflect them yet.
- Prioritise resilience in tougher markets and review a 32 resilient stocks with low risk scores that focuses on businesses with more stable financial profiles.
- Hunt for tomorrow’s quiet winners by checking a 20 high quality undiscovered gems that highlights underfollowed companies with solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com