
Undiscovered Gems In Canada Featuring 3 Promising Small Caps
As the Canadian market navigates a complex landscape, with the manufacturing sector showing signs of slowing momentum and the services sector facing challenges from tariff uncertainties and rising costs, economic indicators like resilient household consumption and solid GDP growth continue to support overall stability. In this environment, identifying promising small-cap stocks requires a keen eye for companies that can leverage these conditions to drive growth and innovation.
Top 10 Undiscovered Gems With Strong Fundamentals In Canada
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Fortuna Mining | 7.64% | 12.54% | 45.56% | ★★★★★★ |
| China Gold International Resources | 17.41% | 2.90% | 18.32% | ★★★★★★ |
| Total Energy Services | 3.93% | 18.21% | 37.46% | ★★★★★★ |
| Thor Explorations | NA | 38.45% | 61.95% | ★★★★★★ |
| SSR Mining | NA | 3.57% | -3.80% | ★★★★★★ |
| Alvopetro Energy | 18.59% | 7.72% | 6.43% | ★★★★★☆ |
| Hydreight Technologies | 22.28% | 71.66% | 59.41% | ★★★★☆☆ |
| Kolibri Global Energy | 20.09% | 25.10% | -21.44% | ★★★★☆☆ |
| Rio2 | 22.38% | 105.97% | 53.08% | ★★★☆☆☆ |
| Journey Energy | 11.76% | 6.14% | -39.79% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Kolibri Global Energy (TSX:KEI)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Kolibri Global Energy Inc. is an energy company focused on discovering and developing oil and gas projects in the United States, with a market capitalization of CA$354.24 million.
Operations: Kolibri generates revenue primarily from its oil and gas exploration and production activities, amounting to $72.05 million. The company has a market capitalization of CA$354.24 million.
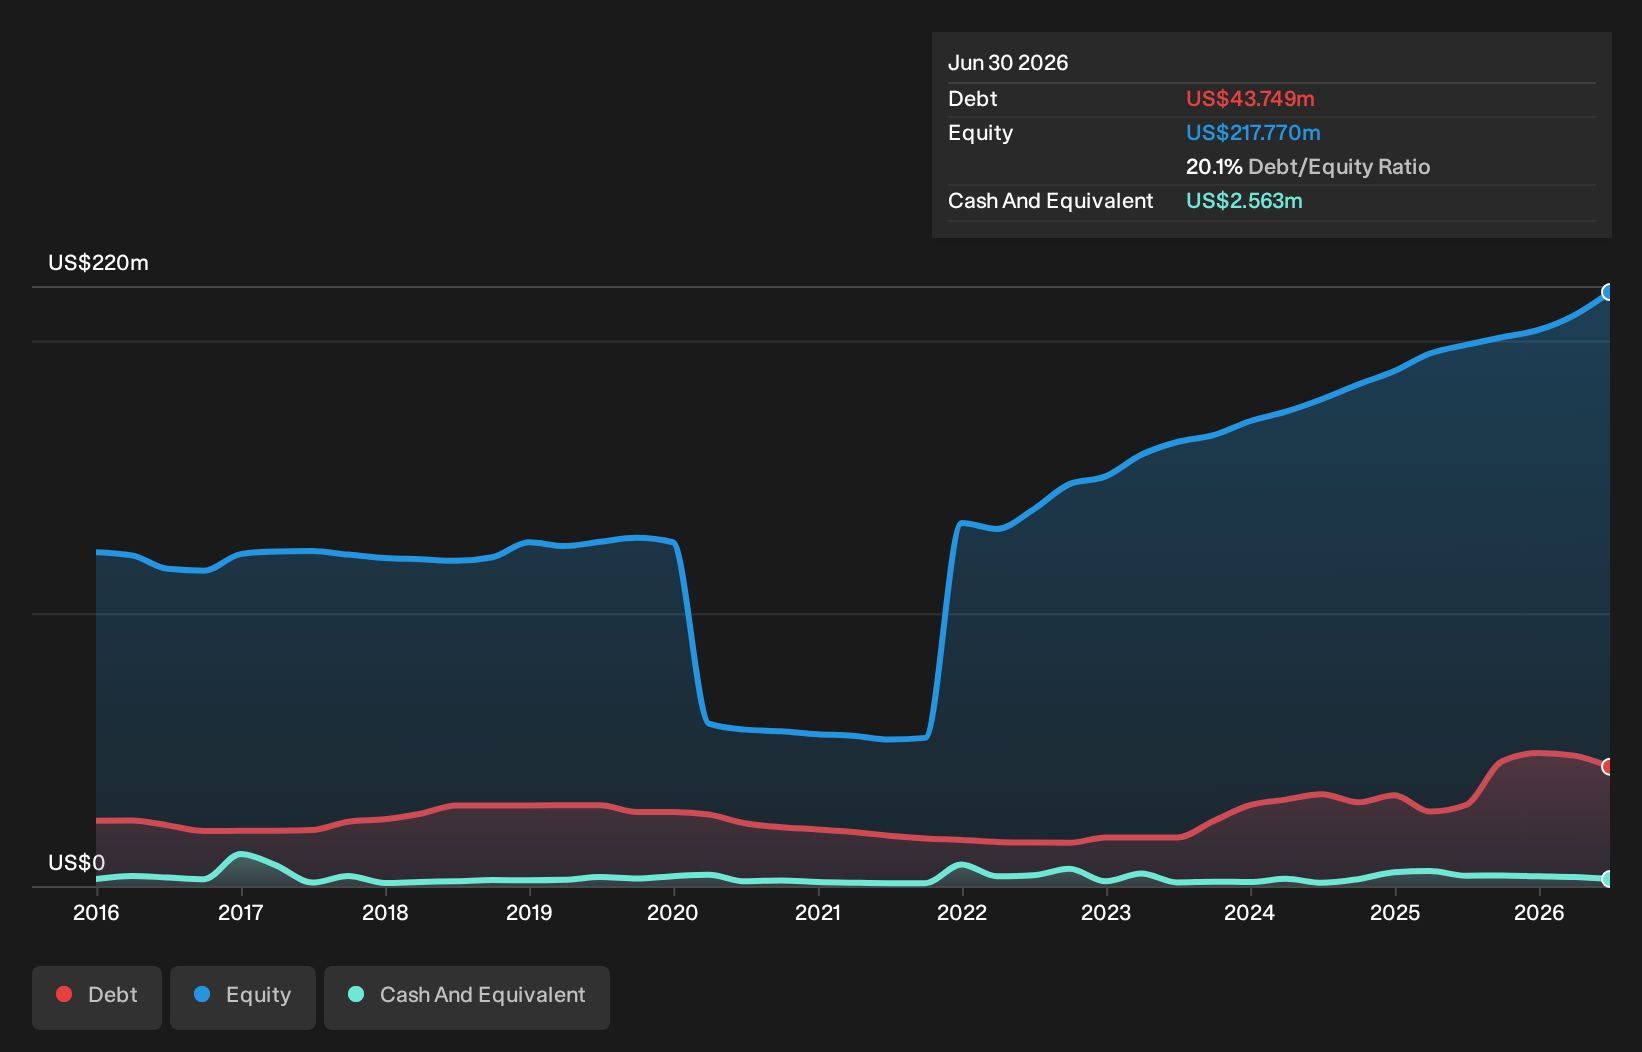
Kolibri Global Energy, an intriguing player in the energy sector, has shown robust financial health with its interest payments well covered by EBIT at 6.8 times. The company's debt to equity ratio improved significantly from 34.4% to 20.1% over five years, reflecting prudent financial management. Trading at nearly 59% below estimated fair value indicates potential undervaluation compared to peers and industry standards. Despite not being free cash flow positive recently, Kolibri's recent operational updates highlight promising production increases in their Tishomingo field wells, which could bolster future revenue streams and shareholder returns if oil prices remain favorable around US$100 per barrel.
SSR Mining (TSX:SSRM)
Simply Wall St Value Rating: ★★★★★★
Overview: SSR Mining Inc. is involved in the acquisition, exploration, and development of precious metal resource properties across the United States, Türkiye, Canada, and Argentina with a market capitalization of CA$9.19 billion.
Operations: SSR Mining generates revenue primarily from its Marigold and Cripple Creek & Victor Gold Mine operations, contributing $619.61 million and $581.15 million respectively. The Puna and Seabee segments add $570.33 million and $162.06 million to the revenue stream, highlighting the company's diversified asset base in precious metals across multiple regions.
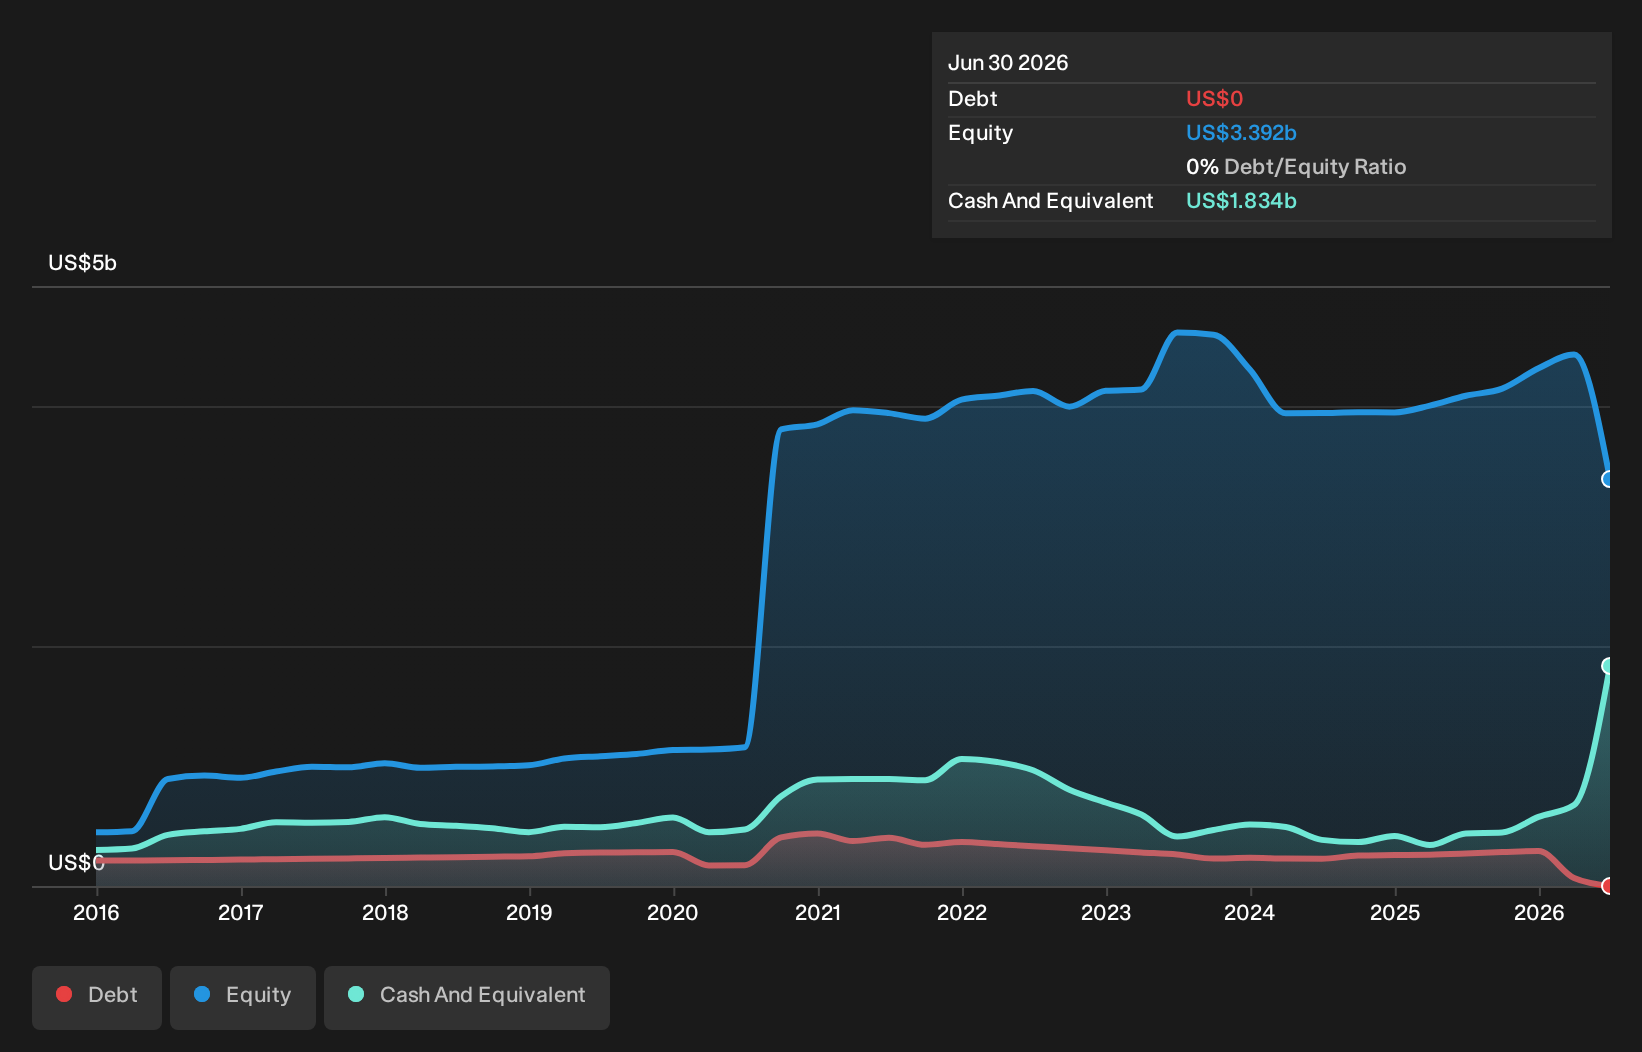
SSR Mining, a nimble player in the mining sector, has shown impressive earnings growth of 143.7% over the past year, outpacing its industry peers. The company stands out with no debt on its books now compared to a debt-to-equity ratio of 10.2% five years ago, highlighting strong financial health. Currently trading at 51.5% below estimated fair value, SSRM offers significant potential for investors seeking undervalued opportunities. Recent strategic moves include acquiring a stake in the Dobbin Project and completing share buybacks worth $337.8 million, reflecting confidence in future prospects despite production challenges earlier this year.
- Get an in-depth perspective on SSR Mining's performance by reading our health report here.
Explore historical data to track SSR Mining's performance over time in our Past section.
Alvopetro Energy (TSXV:ALV)
Simply Wall St Value Rating: ★★★★★☆
Overview: Alvopetro Energy Ltd. is involved in the acquisition, exploration, development, and production of hydrocarbons in Brazil and Canada with a market cap of CA$358.15 million.
Operations: Alvopetro Energy generates revenue primarily from its oil and gas exploration and production segment, amounting to $62.42 million.
Alvopetro Energy, a nimble player in the energy sector, has shown impressive growth with earnings up 25.7% over the past year, outpacing its industry peers. The company boasts a solid financial position with more cash than total debt and well-covered interest payments at 121 times EBIT. Recent expansions in Brazil and Canada aim to boost production capacity further; however, reliance on Brazilian assets poses potential risks from regulatory shifts. With recent sales volumes reported at 2,627 boepd in September and a consensus price target of CA$12.68 set by analysts, Alvopetro's strategic moves seem poised for future gains despite inherent challenges.

Where To Now?
- Access the full spectrum of 12 TSX Undiscovered Gems With Strong Fundamentals by clicking on this link.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com