
NetEase Cloud Music (SEHK:9899) Expands Global Artist Reach, Is It Undervalued?
NetEase Cloud Music (SEHK:9899) is back in focus after announcing a multi-year partnership with gamma., which positions the platform as a launch hub for global artists reaching listeners across China.
The gamma. partnership comes at a time when NetEase Cloud Music’s share price has been under pressure, with a year-to-date share price return of down 53.47% and a 1-year total shareholder return of down 64.00%. This is occurring even as the stock has shown a 3.48% 1-day share price gain and a 4.65% 7-day share price return that suggest early momentum may be returning around fresh catalysts.
Spot opportunities around NetEase Cloud Music's gamma. deal by scanning for other media and entertainment players showing similar catalysts in our curated list of 613 high quality undiscovered gems.The share price slide and recent bounce leave a wide gap between where NetEase Cloud Music trades and where point-in-time value estimates cluster. Which side of that spread appears closer to fair value?
Preferred P/E of 9.4x for NetEase Cloud Music: Is it justified?
On Simply Wall St's numbers, NetEase Cloud Music trades on a P/E of 9.4x, compared with a peer average of 14.5x and a Hong Kong Entertainment sector average of 9.8x. At a last close of HK$87.70, that gap points to the market assigning a lower price to each unit of current earnings than many comparable media and entertainment stocks.
The P/E ratio links the HK$87.70 share price to earnings per share and gives a quick read on how much investors are paying for current profitability. For a business built on online music and social entertainment services in the PRC, this measure speaks directly to what the market is willing to pay today for a profit stream that is already established, rather than for future revenue that is not yet profitable.
NetEase Cloud Music screens as good value on P/E against both direct peers and the broader Entertainment group. However, the fair P/E estimate sits at the same 9.4x level. That alignment suggests the multiple is close to a level the market could reasonably move toward over time, so any future re-rating may rely more on shifts in earnings quality or growth than on a simple catch-up in valuation.
Explore the SWS fair ratio for NetEase Cloud Music.Result: Price-to-earnings of 9.4x (ABOUT RIGHT)
Still, NetEase Cloud Music faces pressure from recent share price declines and relies heavily on PRC music and social entertainment demand, which could shift quickly.
Find out about the key risks to this NetEase Cloud Music narrative.
Another view on NetEase Cloud Music’s value
On earnings multiples, NetEase Cloud Music looks roughly in line with its fair ratio at 9.4x, yet our DCF model points to something different. The shares trade at HK$87.70 while the SWS DCF model suggests a future cash flow value of HK$182.03, implying the market price is well below that estimate. Which lens do you treat as your anchor?
Look into how the SWS DCF model arrives at its fair value.
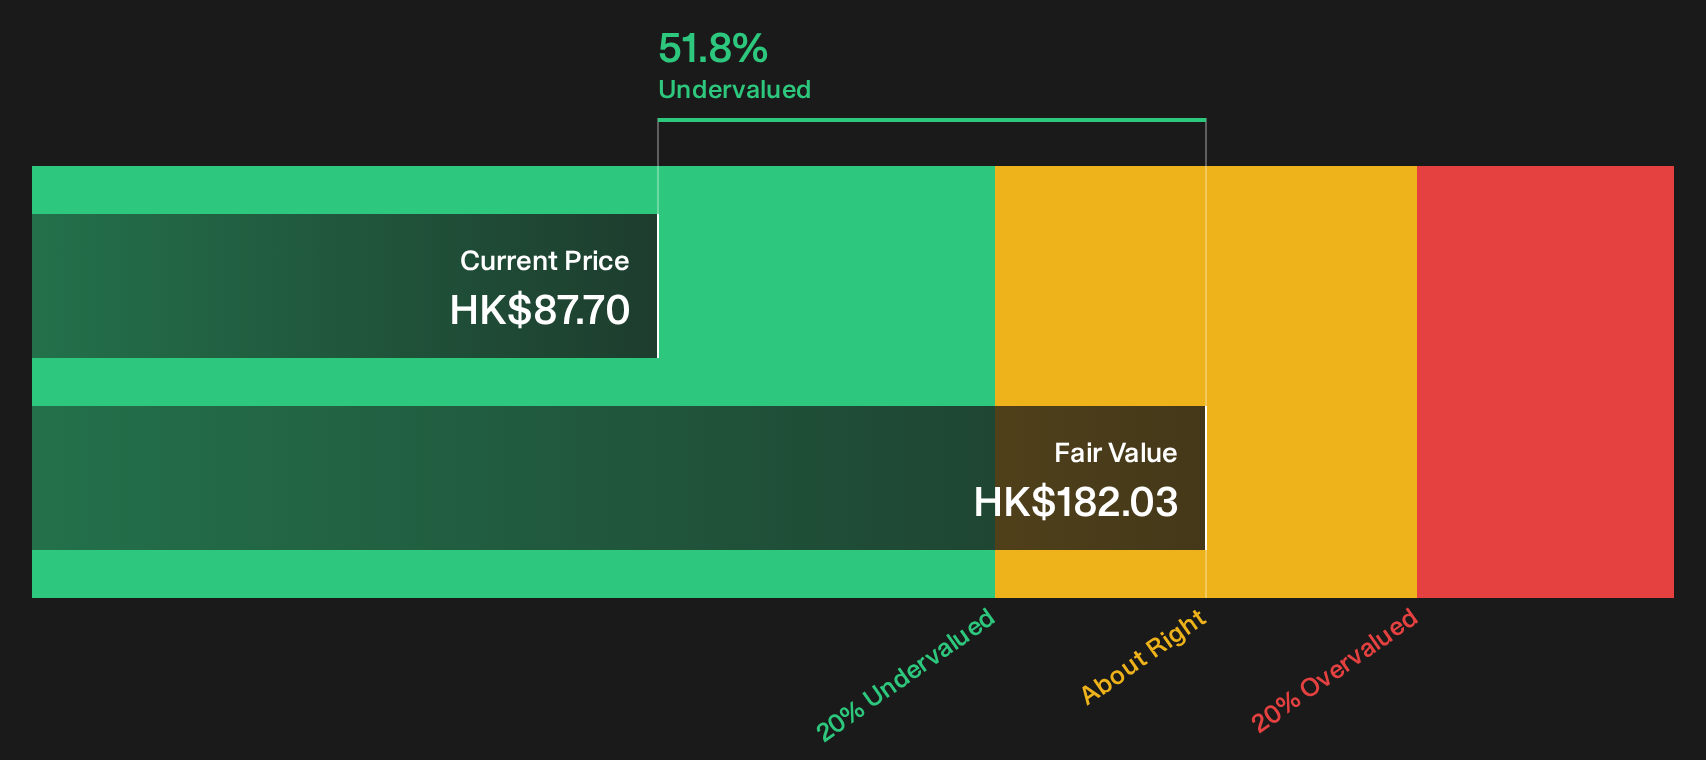
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NetEase Cloud Music for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around NetEase Cloud Music is clearly mixed, with pressure on the share price but a valuation gap and new partnership story building in the background. Act quickly, review the data on both sides of the argument, then weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond NetEase Cloud Music?
If NetEase Cloud Music has sharpened your focus on valuation and catalysts, it makes sense to widen your watchlist using targeted filters built around clear fundamentals.
- Target fresh opportunities that the crowd may have missed by running the 613 high quality undiscovered gems before they attract wider attention.
- Zero in on quality at a discount by scanning the 194 high quality undervalued stocks and compare how those candidates stack up against NetEase Cloud Music on valuation grounds.
- Reduce potential downside shocks by filtering for the 231 resilient stocks with low risk scores so you can balance higher volatility ideas with sturdier holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com