
Sanwa Holdings (TSE:5929) Looks Undervalued On DCF, Is The Market Missing Its Cash Flow?
Event driven look at Sanwa Holdings’ valuation
Fresh discounted cash flow analysis has put Sanwa Holdings (TSE:5929) in the spotlight, suggesting its calculated intrinsic value sits well above the current share price and raising questions about how the market views its cash generation.
Recent trading has Sanwa Holdings’ share price at ¥3,630, with a 7 day share price return of 4.16% and a 1 month share price return of 5.00%, even though the year to date share price return is down 11.96% and the 1 year total shareholder return is down 8.81%. At the same time, the 3 year total shareholder return of 102.09% and 5 year total shareholder return of 203.59% show that long term holders have still seen substantial gains, suggesting that short term momentum has cooled compared with the longer run trend despite the current DCF valuation gap.
Spot opportunities like Sanwa Holdings’ apparent DCF gap by scanning a curated 13 high quality undervalued stocks, which brings together companies with solid cash generation and balance sheets that investors often overlook.Sanwa Holdings has a long record in building hardware and a share price that has cooled this year. The real tension now is whether that solid business is already reflected in ¥3,630 or whether the DCF work points to more value.
Price-to-Earnings of 13.1x: Is it justified?
On simple earnings terms, Sanwa Holdings trades on a P/E of 13.1x, which screens as good value against some benchmarks but looks a little rich against others. The last close at ¥3,630 sits alongside this multiple and invites a closer look at what investors are paying for the group’s profit stream.
The P/E ratio compares the current share price with earnings per share. For a business like Sanwa Holdings, which generates construction metal products revenue across Japan, North America, Europe and Asia, it is a quick way to see how much the market pays for each unit of profit. A lower P/E can indicate investors are more cautious about growth or are not willing to pay up for the existing earnings base.
Compared with its own fair P/E estimate of 14.8x, the current 13.1x suggests the market is applying a cheaper tag than the level indicated by this fair ratio work. That represents a clear discount and implies investors are not fully aligning the price with the company’s earnings profile. At the same time, the stock is labelled expensive versus the JP Building industry average P/E of 12.5x. In other words, the market is still assigning a premium compared with the broader sector even while it prices the shares below the fair P/E level.
Explore the SWS fair ratio for Sanwa Holdings.
Result: Price-to-Earnings of 13.1x (UNDERVALUED)
Still, Sanwa Holdings faces clear risks if construction demand cools or if its international segments struggle to maintain current levels of revenue and profit contribution.
Find out about the key risks to this Sanwa Holdings narrative.
Another view on Sanwa Holdings’ value
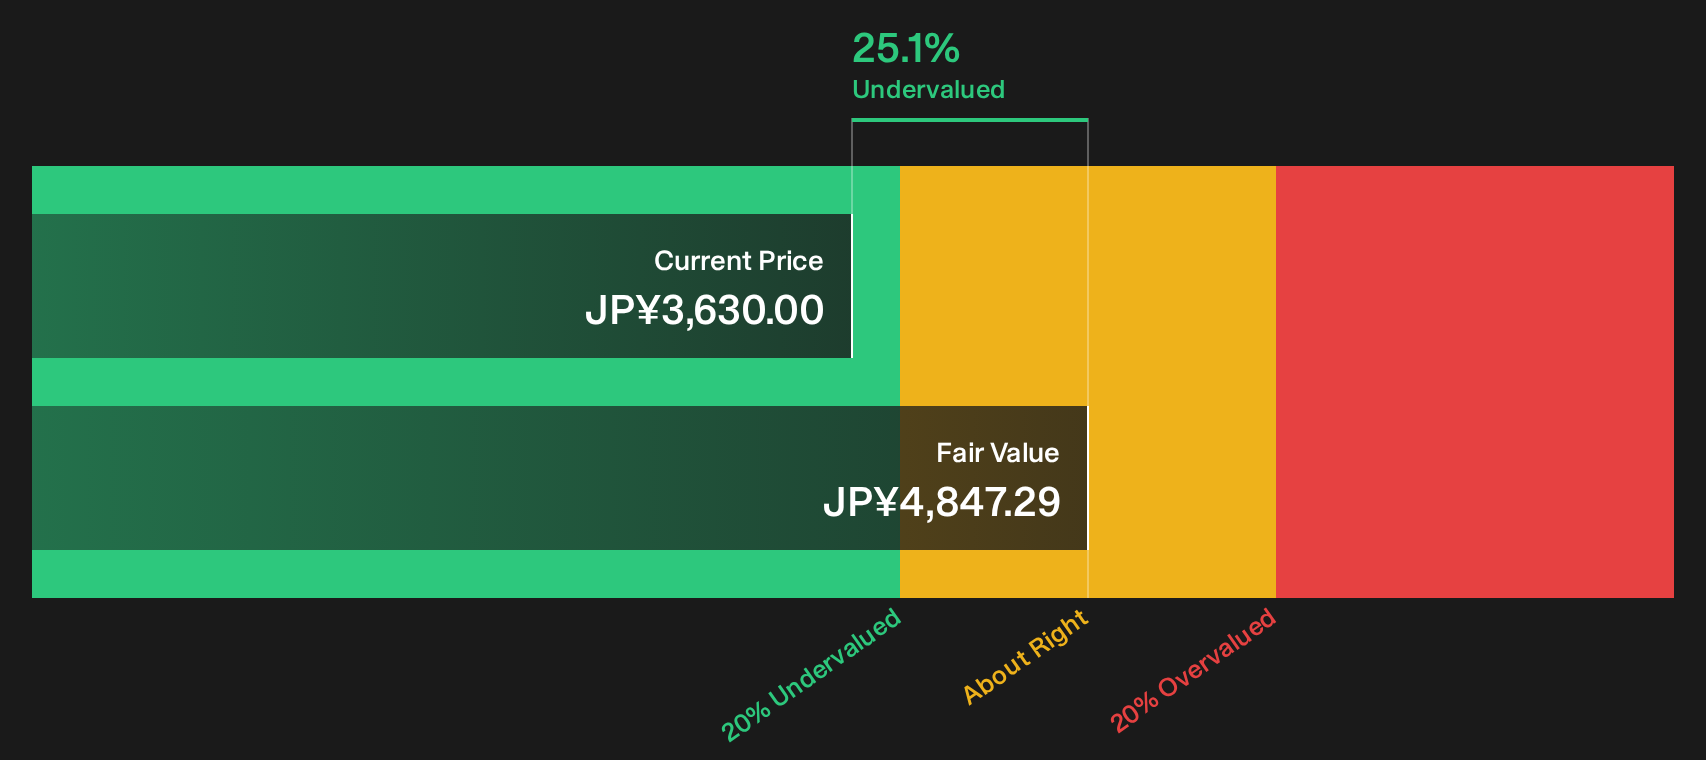
The discounted cash flow work suggests Sanwa Holdings shares at ¥3,630 trade at a 25.1% discount to an estimated future cash flow value of ¥4,847.29. That points to undervaluation on this model and raises a simple question for investors: Is the market underestimating how dependable that cash stream will be.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sanwa Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Sanwa Holdings so far. If you want to move from headline impressions to your own conviction, start by weighing both the valuation gap and the optimism embedded in its rewards profile, then take a closer look at the 3 key rewards
Looking for more Sanwa Holdings style ideas?
If Sanwa Holdings has sharpened your focus on pricing and quality, do not stop here. Broaden your watchlist now or risk missing better fits for your goals.
- Target potential value opportunities early by reviewing the 13 high quality undervalued stocks that could be trading below what their cash flows suggest.
- Prioritise resilience over drama and scan a 22 resilient stocks with low risk scores that screens for steadier balance sheets and business profiles.
- Hunt for underfollowed potential by filtering through a 73 high quality undiscovered gems where fundamentals, not headlines, drive the story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com