
How Mumbai Office Lease At Sumitomo Realty & Development (TSE:8830) Has Changed Its Investment Story
- Sumitomo Realty & Development’s Indian arm, Goisu Realty, has leased about 49,820 sq ft of premium space in its Sumitomo C65 building in Mumbai’s Bandra-Kurla Complex to Sumitomo Mitsui Banking Corporation under a five-year agreement that includes a nine-month rent-free period and rent of ₹694 per sq ft per month starting June 2027.
- The lease, agreed in October 2026, indicates that Sumitomo Realty & Development is securing sizeable commitments from blue-chip tenants in India. This reinforces occupancy visibility for its high-end Mumbai offices and clarifies cash flow terms through stepped rent increases and a defined multi-year contract.
- We will now look at how this large Mumbai lease with Sumitomo Mitsui Banking Corporation could influence Sumitomo Realty & Development’s investment narrative.
Scan how other real estate and infrastructure focused companies are positioning for similar long-term leases and balance sheet resilience by reviewing the hand picked list of solid balance sheet and fundamentals (22 results) alongside Sumitomo Realty & Development.
What Is Sumitomo Realty & Development's Investment Narrative?
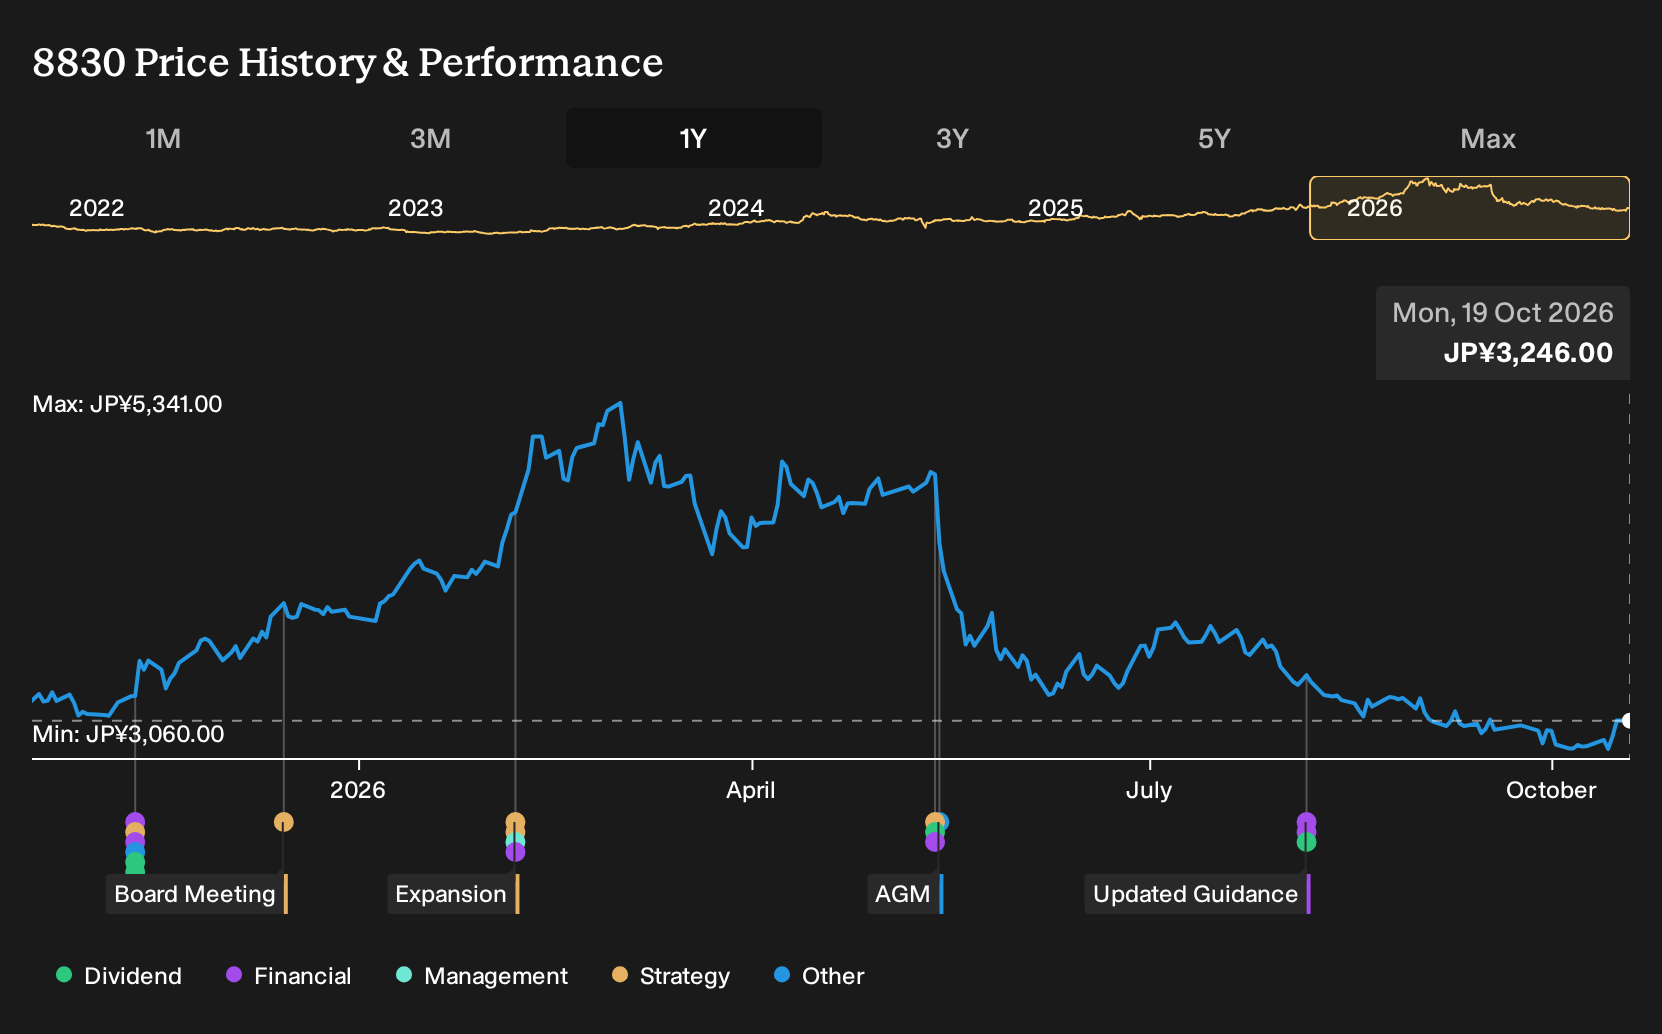
To own Sumitomo Realty & Development, you need to believe in a long game built on high quality assets, disciplined leasing and the ability to keep funding heavy development without stretching the balance sheet. Earnings growth of 17.3% over the past year and a P/E of 13.4x that sits below the broader JP market, but above the Japanese real estate peer group, point to a business already priced as a higher quality operator rather than a deep value play.
The SMBC lease in Mumbai and Sumitomo Realty & Development’s presence at the Nikkei India Japan forum both speak to a push to deepen relationships with large corporate tenants and to position for cross border demand. That kind of visibility helps on the operations side, since real estate is capital intensive and this group already has debt that is not well covered by operating cash flow. The short term story still hinges on execution, keeping occupancy and pricing healthy and proving that moderate forecast growth of around 4% can support that funding model.
Yet there is an underappreciated pressure point in this funding mix that could matter quite a lot if...
There's only one way to know the right time to buy, sell or hold Sumitomo Realty & Development. Head to Simply Wall St's company report for the latest analysis of Sumitomo Realty & Development's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sumitomo Realty & Development research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sumitomo Realty & Development. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sumitomo Realty & Development's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sumitomo Realty & Development?
Once you have a view on Sumitomo Realty & Development, it can help to compare it with other companies that share similar qualities or offer a different risk and income profile. The Simply Wall St Screener lets you scan the market quickly and focus on groups of stocks that match what you care about most.
- If you want a starting point for potential mispricing, check out 13 high quality undervalued stocks that combine solid fundamentals with a share price that screens as cheap on key metrics.
- If stability and capital preservation matter more to you than aiming for very high returns, filter for 22 resilient stocks with low risk scores that score well on balance sheet strength and business risk.
- If you are hunting for underfollowed opportunities, scan through 73 high quality undiscovered gems that pair quality fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com