
What Louisiana-Pacific Bears Spotted Before The Slide
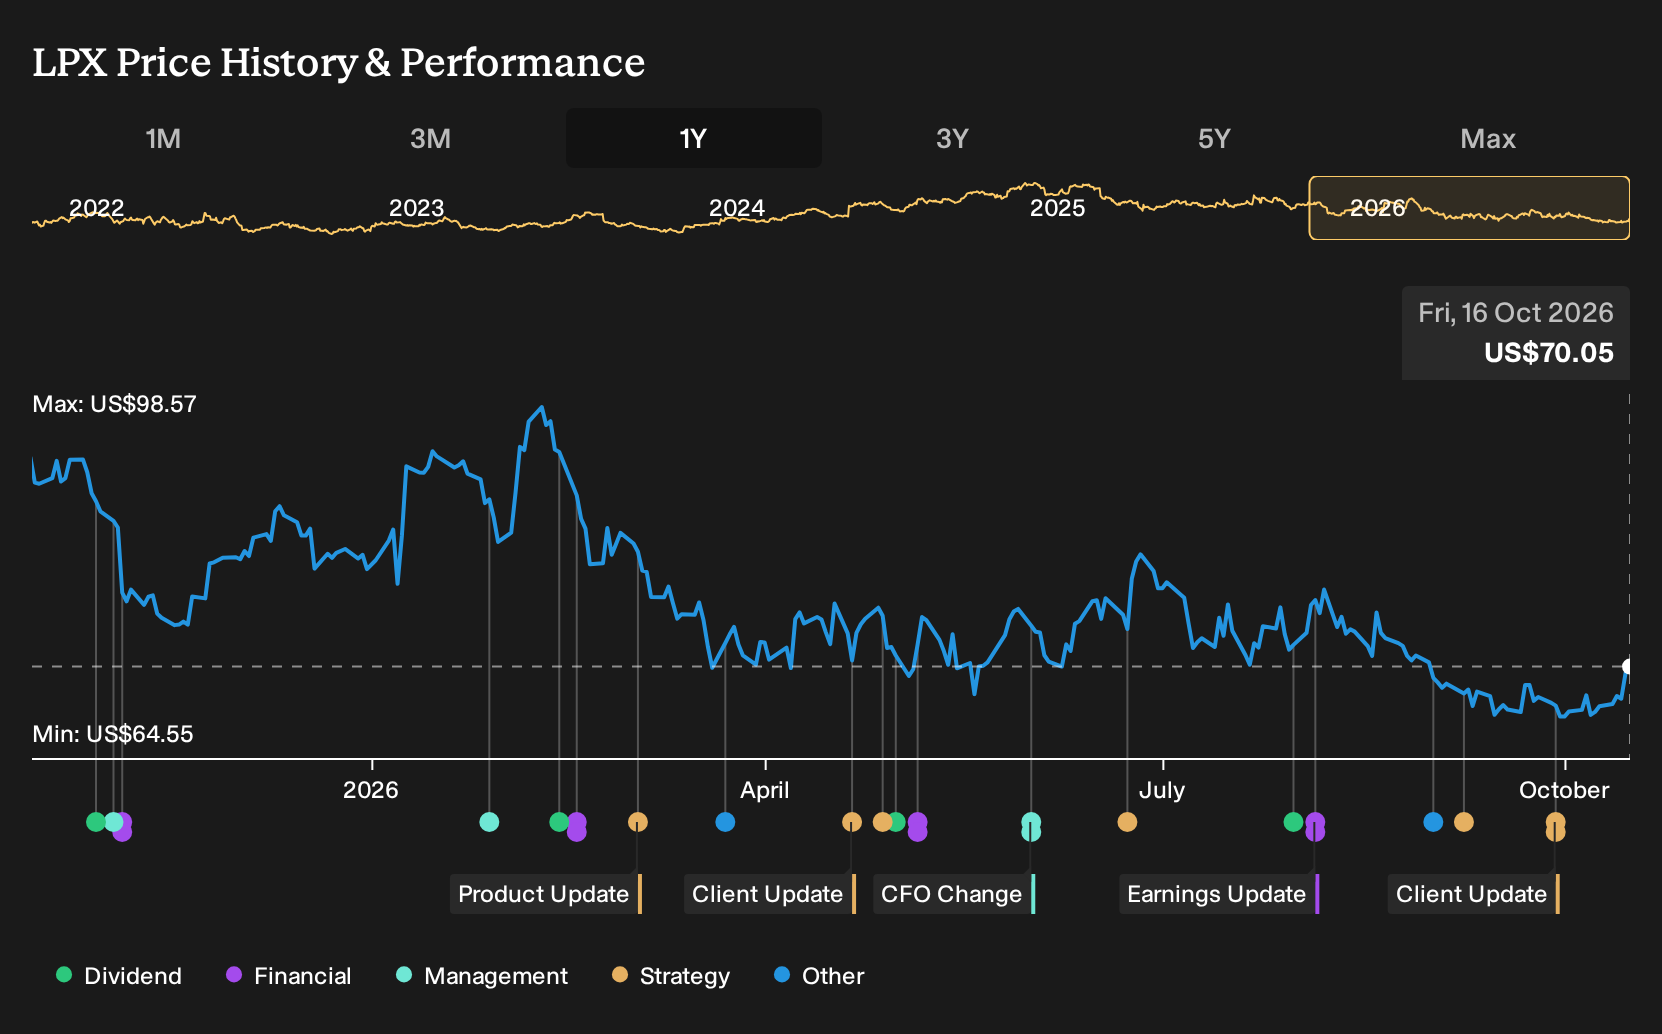
If you had hesitated in October 2025 and decided not to buy Louisiana-Pacific after reading both bullish and bearish views, the past year may look different today. For Louisiana-Pacific shareholders, the loss over the past year was 21.6%, including dividends. That backward-looking number is clear. The harder part is this: Given what was already on record about housing exposure, OSB pricing pressure, and reliance on North American demand, what exactly could you have questioned at the time?
The easy part of this move is behind Louisiana-Pacific. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Argument Investors Had To Settle On Louisiana-Pacific
The shares cost US$90.26 at the start of the period, and anyone looking at Louisiana-Pacific then was really choosing between two clear stories.
The bullish view put Fair Value at US$103, a rough guide to what that camp thought the stock was worth if sustainable siding, like SmartSide and ExpertFinish, kept winning share in remodeling and offsite construction.
The bearish case anchored on a Fair Value of US$71, built around worries that reliance on North American housing and tighter environmental rules would push up costs and make earnings more volatile.
What The Results Changed For The Louisiana-Pacific Debate
The clearest new fact for Louisiana-Pacific was operational. Management chose to curtail OSB production at Jasper, Texas after a Q2 2026 earnings miss, as softer demand and flat pricing turned that segment into an expected EBITDA loss. That move fits the cautious case that warned about OSB and North American housing reliance, while Q1 siding strength and new SmartSide distribution cuts the other way. Overall, the evidence cut both ways.
The key lesson is simple. When a thesis leans on resilient margins and pricing power, you check segment EBITDA, net margin and capacity decisions against those claims every quarter.
What You Are Really Paying For In Louisiana-Pacific Today
Louisiana-Pacific now trades at US$70.05. The selected Narrative sees Fair Value above that level and attributes the difference to how much weight you place on SmartSide siding, ExpertFinish expansion and national distribution deals versus ongoing OSB drag and softer siding guidance.
The question for you is whether the one year slide of about 21.6% reflects fading earnings power or a reset that leaves room if SmartSide share gains, pricing power and margin targets hold.
"The current valuation implies that investors are placing more weight on ongoing OSB EBITDA losses and weaker 2026 Siding guidance than on mid-20s Siding EBITDA margins, liquidity of about US$1b, and the view in this narrative that Louisiana-Pacific is undervalued."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Before The Next Story Makes Headlines
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 46% below our estimate - converts a record backlog of technology heavy projects into higher margin installation and service work.
- Company 2 - 42% below our estimate - monetizes specialized PhD expertise on AI risk, infrastructure reliability and tightening regulatory requirements.
- Company 3 - 32% below our estimate - supplies the GPUs and software stack customers rely on to build high yield AI data centers.
Those are three of them. See every one of the 25 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com