
Jamie Dimon Just Listed 5 Market Risks Hiding 'Under the Surface.' JPMorgan Is Already Feeling The Heat.
Jamie Dimon has a habit of warning investors, and he did it again on Oct. 13. As JPMorgan Chase (JPM) reported its third-quarter results, its CEO listed the risks he sees building beneath the surface. These include large government deficits, inflation that won’t cool, rising interest rates, global tensions, and stock prices that already look high. Coming from the head of America’s biggest bank, those warnings carry weight. They also came alongside a rare weak quarter. Excluding some one-time losses, JPMorgan earned $5.75 per share, below the $5.93 analysts expected. Revenue rose 8% to $50.9 billion, but expenses grew faster, at 12%.
Dimon’s Warning Is Already Showing Up at JPMorgan
Some of these risks are already hitting JPMorgan itself. Rising interest rates lower the value of the bonds a bank holds. JPMorgan took $658 million in losses on its bond investments this quarter. Falling bond values, along with other factors, also shrank its capital cushion slightly, a key safety measure that regulators watch. Dimon said trading and deal-making slowed somewhat during the quarter, and the bank pulled back on buying its own shares. To me, JPMorgan looks like a company that is quietly preparing for tougher times. It’s still earning plenty, though. Profit rose 6% from a year ago to $15.3 billion, and the bank earned a strong 17% return on its shareholders’ money.
About JP Morgan Stock
JPMorgan Chase is the largest bank in the U.S., offering everyday banking, credit cards, loans, investment banking, trading, and wealth management. CEO Jamie Dimon is one of the most influential voices on Wall Street, and his latest warnings came alongside the bank’s third-quarter results. Headquartered in New York City, the company's roots date back to 1799.
Over the past year, JPMorgan Chase shares have been up 12%, outperforming the Financial Select Sector ETF’s (XLF) gain of approximately 7%. The stock traded sideways since June, when it was $296 on June 1. Since then, the stock gained traction, reaching a 52-week high of $366. This was supported by the strong second-quarter earnings, higher net interest income, and improved investment-banking activity. However, the rally faces some headwinds after JPMorgan’s third-quarter earnings missed analyst expectations amid weaker fixed-income trading.
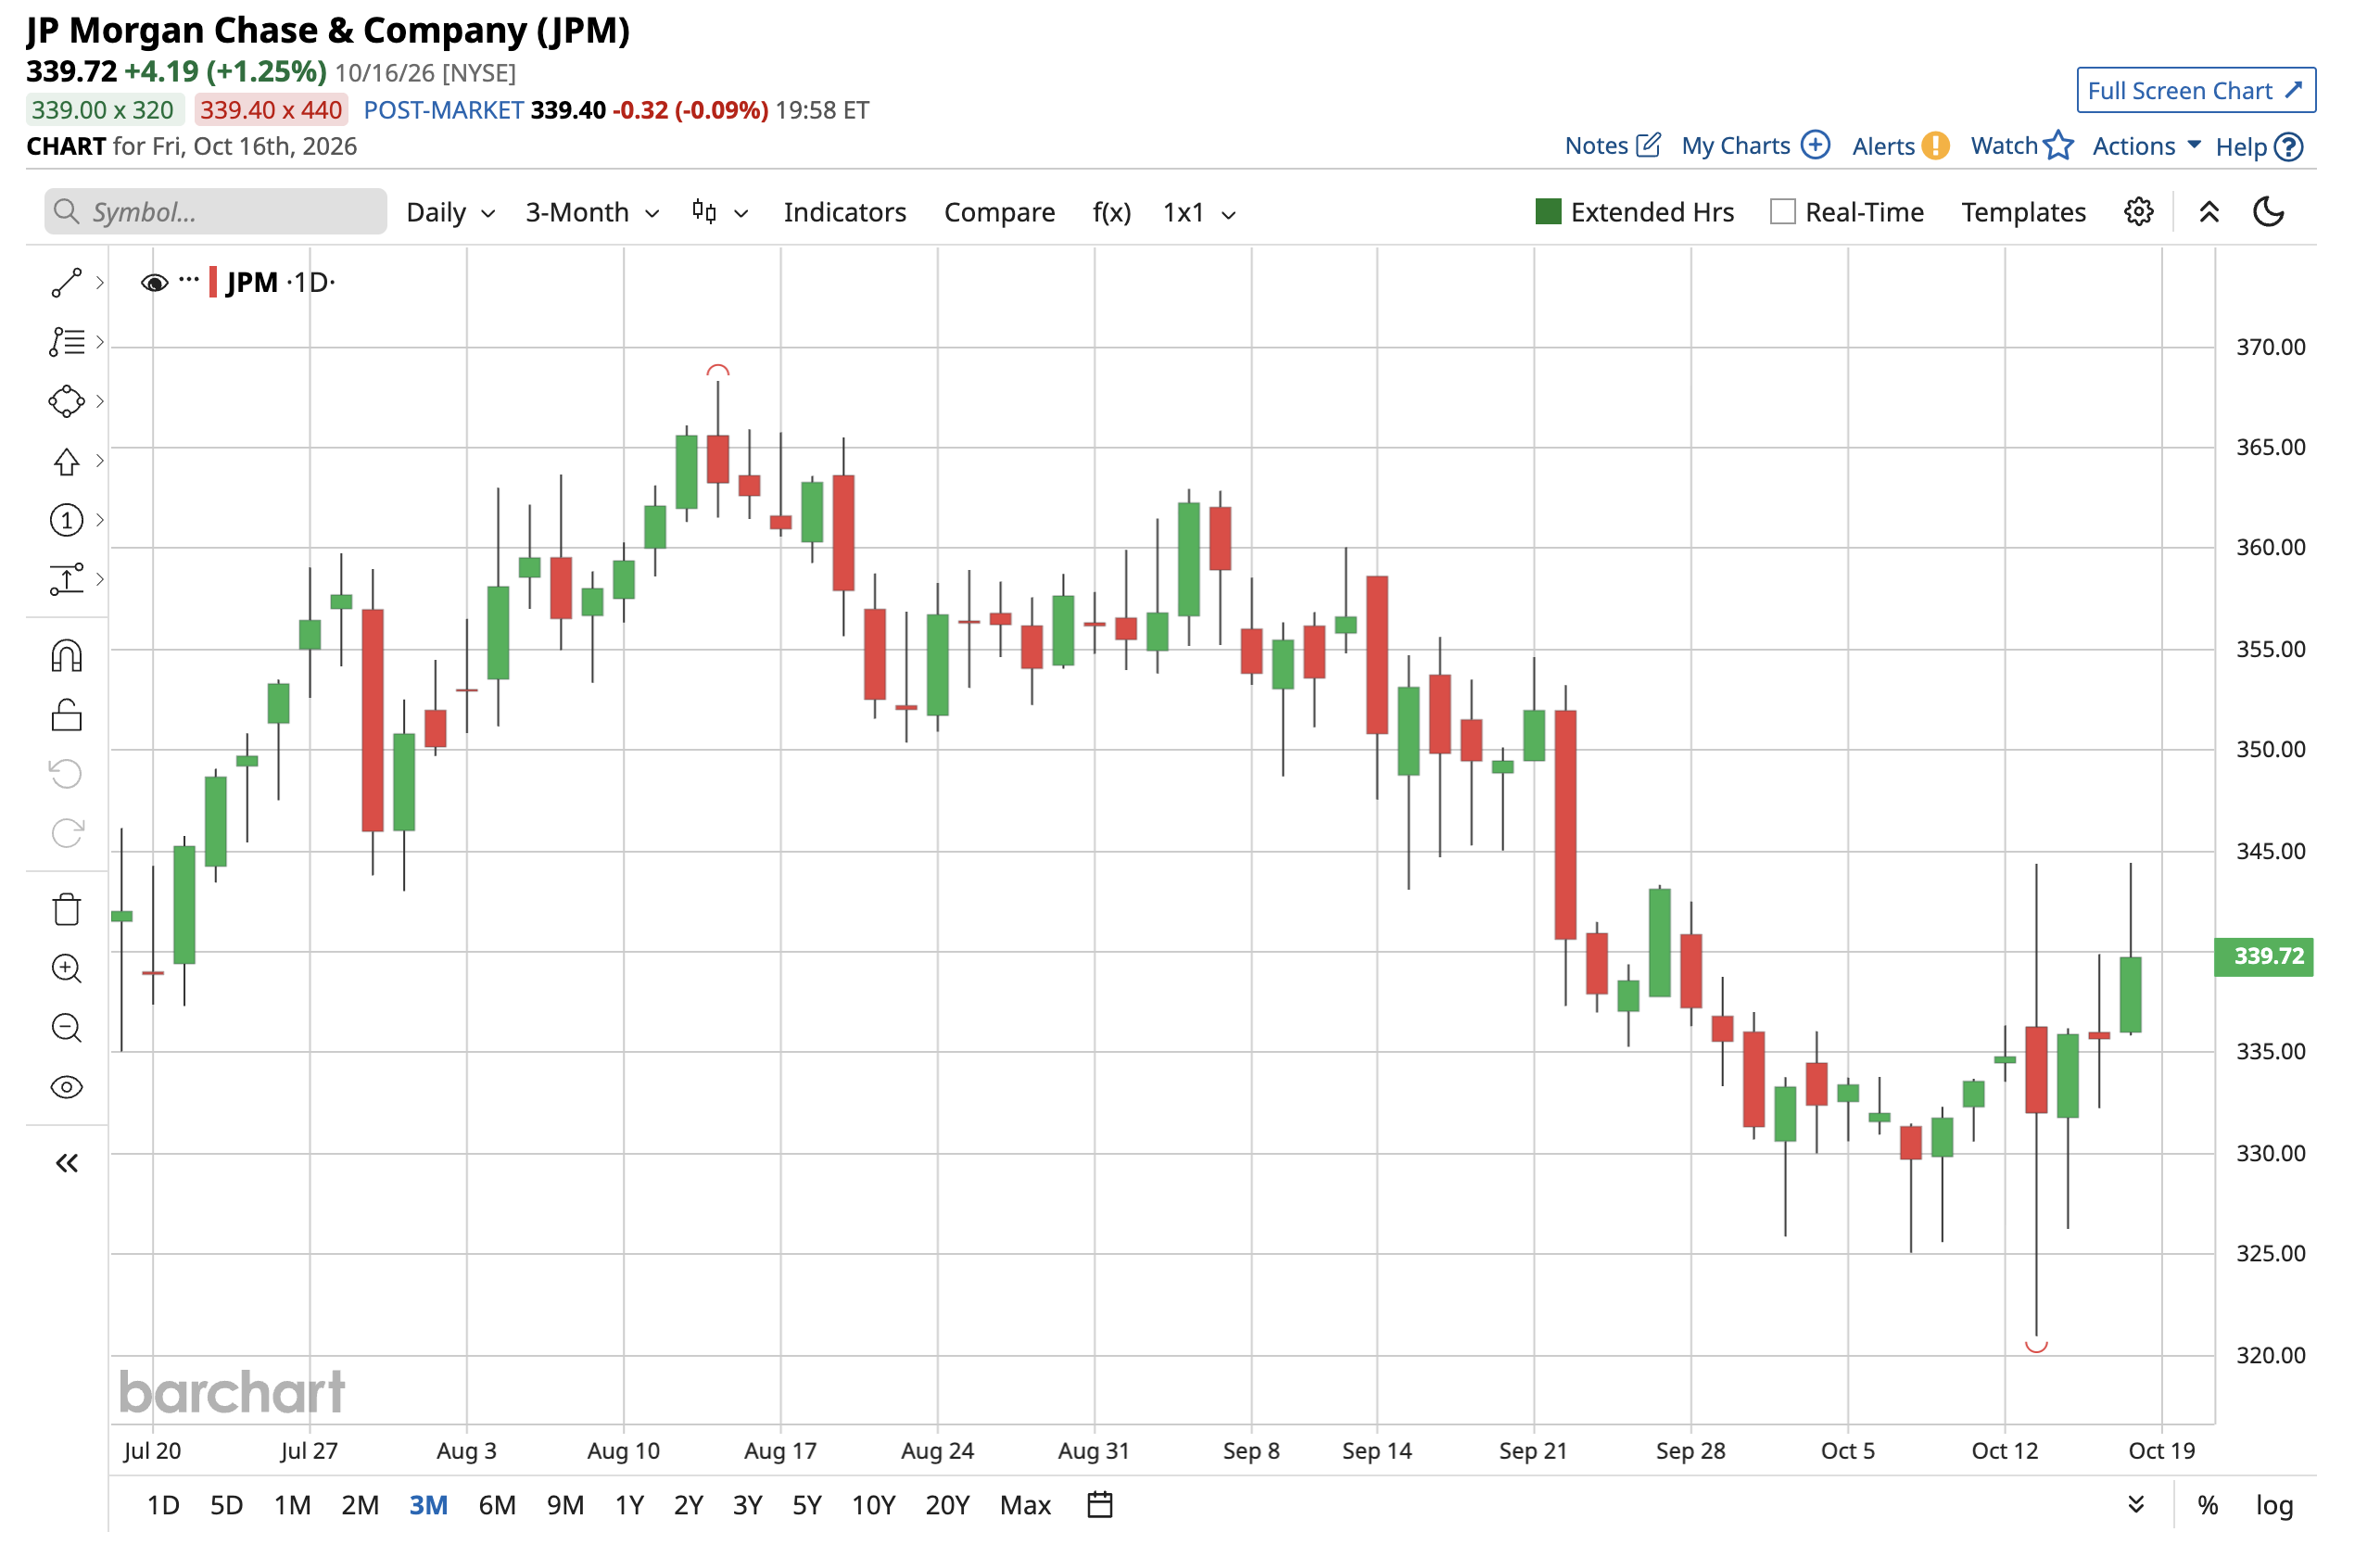
In my opinion, JPMorgan’s valuation looks stretched. The forward P/E of 14.02x is about 14% higher than its five-year average, while the forward price-to-sales ratio of 4.23x is about 18% higher. Investors have generally paid up for JPMorgan because it’s widely seen as the best-run big bank. But the reason I say it looks stretched is its EPS outlook. Analysts expect earnings to grow 22% this year, then slow down to just 4% to 7% in the next three. If Dimon is right and markets cool, JPMorgan's trading and deal-making could slow further, which is risky for a stock already trading at a premium. Overall, I’d say new buyers may want to wait for a better price before adding the stock to their portfolio.
JPMorgan Projects $107 Billion in 2027 Net Interest Income
JPMorgan's third-quarter results reflected strength across its major businesses, even as expenses rose and credit costs remained elevated. Revenue increased 8% from a year earlier to $50.9 billion, supported by higher deposit balances, stronger markets activity, and rising asset-management fees. Net income for the quarter was $15.3 billion, reflecting strong profitability across the franchise.
For the rest of 2026, management gave a constructive outlook. For the fourth quarter, the bank guided NII excluding markets to about $25.5 billion, and total NII of about $28 billion. Expenses for the fourth quarter are expected to be about $27.5 billion. For 2027, management said NII excluding markets could reach about $107 billion. CFO Jeremy Barnum said the $107 billion is based on a series of assumptions that are obviously highly uncertain. Moreover, Dimon warned that the 2027 forecast was more uncertain than usual because of global developments.
What Do Analysts Expect for JPM Stock?
On a positive front, Freedom Broker upgraded JPM to Buy from Hold with a price target of $370, up from $365. The firm believes the bank's fundamentals remain largely unchanged after its Q3 results. However, the recent decline in JPMorgan’s share price has made the stock more attractive, offering greater potential for gains. In contrast to Freedom Broker, Citi lowered the firm’s price on JPM from $360 to $350 and kept a Neutral rating. The firm upgraded its forecasts after the bank’s earnings report.
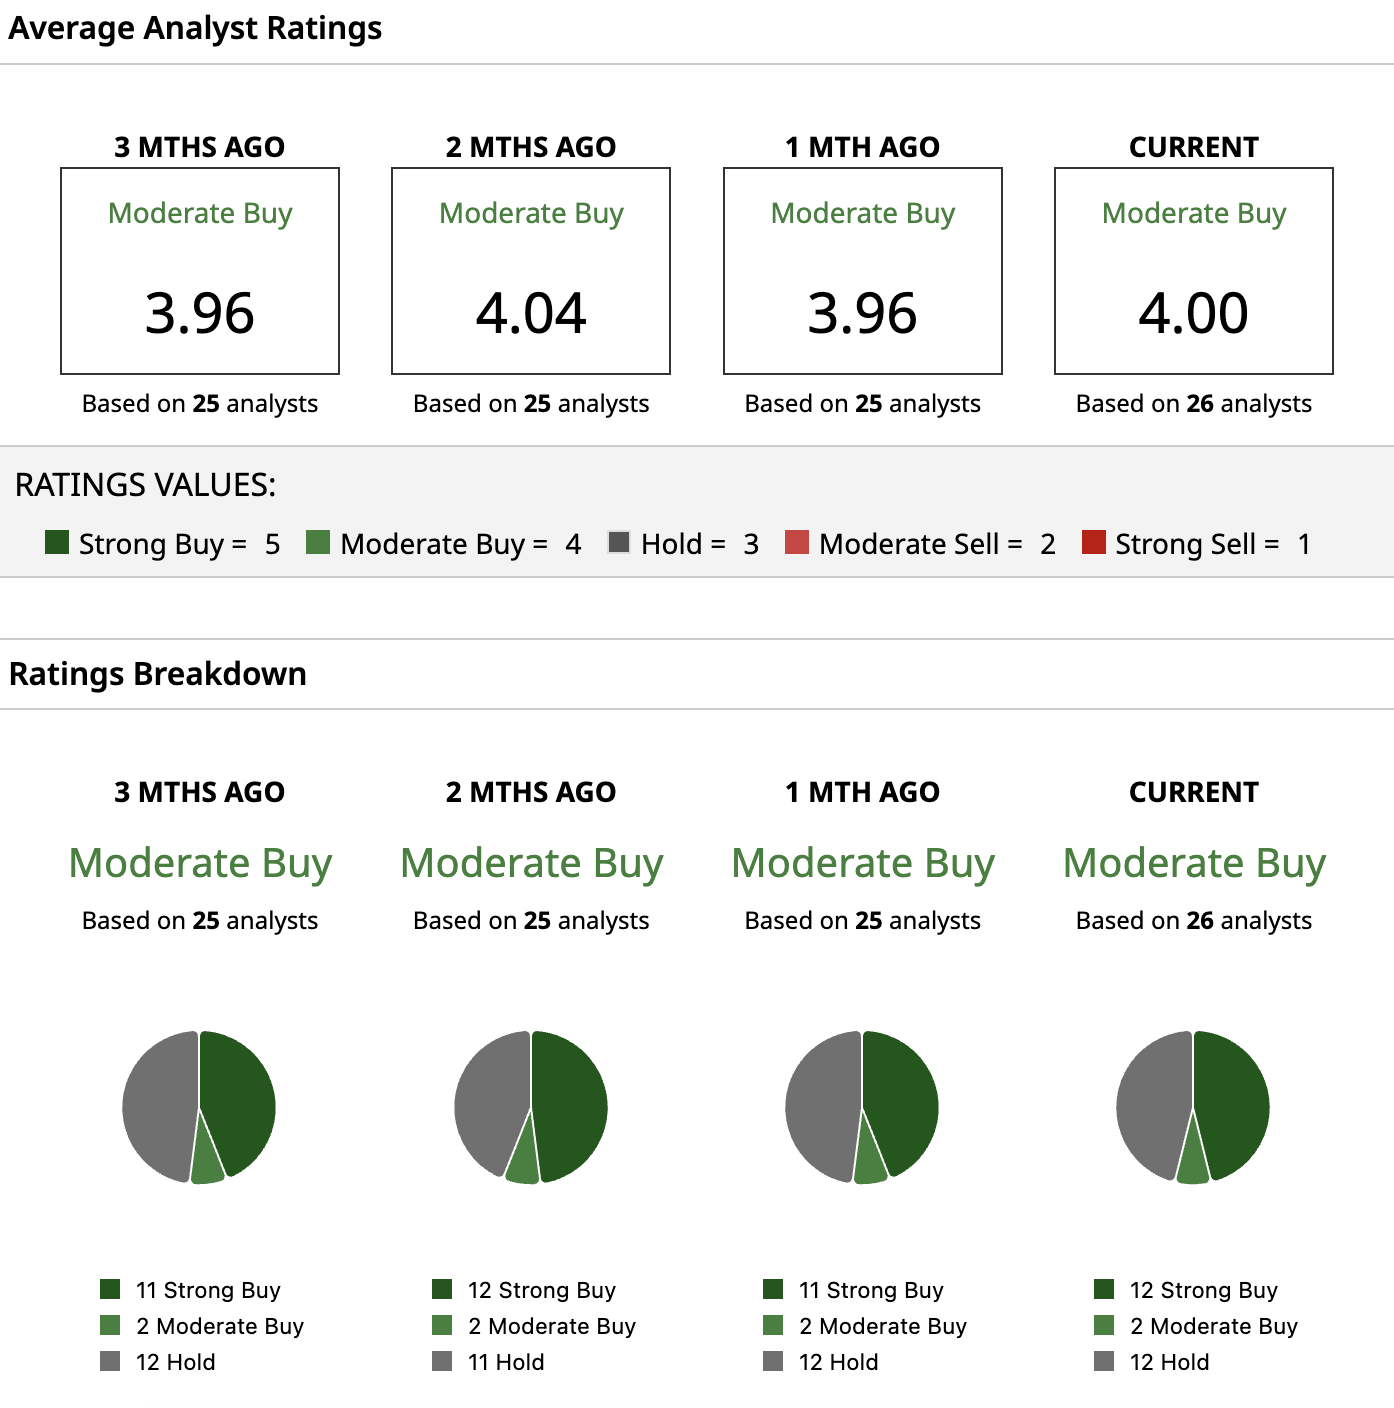
Based on 26 Wall Street analysts covering JPM stock, the stock holds a consensus “Moderate Buy” rating. Out of those, 11 have a Strong Buy rating, two have a “Moderate Buy” rating, and 13 have a “Hold” rating. The stock has a mean price target of $367, reflecting a modest gain of 9%.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.