
Flowserve (FLS) Pullback Puts Its Undervalued Narrative Back In Focus
Flowserve (FLS) is back on investors’ radar after fresh trading data showed the shares at $70.52, with returns mixed over the past month and past three months and a strong one-year total return.
Recent trading has been choppy for Flowserve, with the share price slipping around 4.6% over the past month but still showing positive 3 month momentum, while the 1 year total shareholder return of about 39% points to strong underlying support.
Scan beyond Flowserve and line up other industrials showing a similar mix of recent volatility and longer term momentum with the hand picked 33 high quality undervalued stocks list.
Flowserve now trades about 24% below the average analyst target and around 32% under one fair value estimate after a soft month. Is that caution sensible, or has the pullback gone too far?
Most Popular Narrative: 21% Undervalued
The most followed valuation storyline pegs Flowserve at a fair value of $89.00, which sits well above the recent $70.52 close. That gap depends on how convincingly the business can convert its current contract pipeline and efficiency work into higher profitability over time.
Ongoing work under the Flowserve Business System, including 80/20 portfolio actions, footprint realignment and commercial discipline, is aimed at pushing adjusted operating margin from the roughly 16% expected in 2026 toward the stated 20% target for 2030. This would directly support earnings and free cash flow.
See why 35 investors see Flowserve as 21% undervalued.
Result: Fair Value of $89.00 (UNDERVALUED)
Still, the Flowserve story can crack if Middle East disruptions drag on, or if the Trillium valves deal fails to deliver the expected margin lift.
Find out about the key risks to this Flowserve narrative.
Another View: What Flowserve’s P/E Is Really Saying
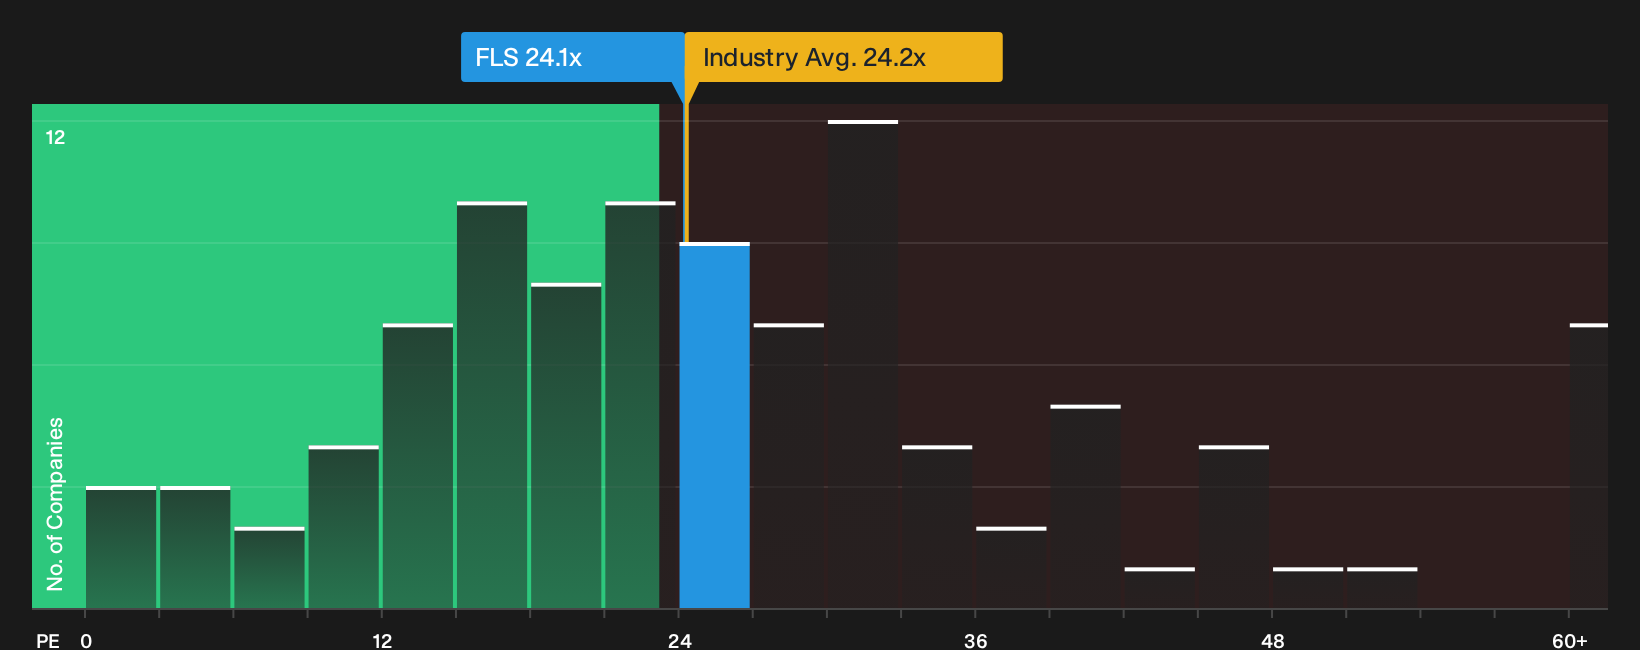
There is a catch. While the SWS fair value narrative points to upside for Flowserve, the market is already paying about 24.1x earnings compared with a 23.8x peer average and a 24.2x broader US Machinery group.
The fair ratio sits higher at 31.8x, which suggests investors are not fully pricing in the level that regression analysis points to as a potential anchor over time. If sentiment cools before fundamentals line up with that fair ratio, how comfortable are you holding a stock that already trades at a premium to its sector averages?
To see how that multiple trade off stacks up alongside other options in the market, take a look at our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Views on Flowserve in this article may feel mixed. This is exactly why it helps to move fast, review the underlying numbers yourself and weigh both the potential upside and the issues that could derail it by checking the 4 key rewards and 2 important warning signs.
Looking for more Flowserve style investment ideas?
If Flowserve has sharpened your focus, use this momentum and line up a few fresh candidates with different strengths before the next move passes you by.
- Target reliable cash generators by scanning companies with strong payouts and stability through the 8 dividend fortresses.
- Hunt for quality at a discount by running the 20 high quality undiscovered gems and seeing which businesses the market is paying less attention to.
- Protect your downside first by filtering for resilient balance sheets using the list of solid balance sheet and fundamentals (25 results) before you commit new capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com