
Kratos Defense & Security Solutions (KTOS) Could Be 59% Undervalued Following Defense Program Progress
Kratos Defense & Security Solutions (KTOS) has had a busy October, breaking ground on new Indiana facilities, advancing turbojet programs, flying a collaborative combat drone in Europe, and showcasing 5G-ready satellite ground software.
Despite the busy October newsflow, Kratos Defense & Security Solutions’ recent share price momentum has been weak, with the stock down about 15% over 30 days and roughly 49% year to date. However, the 3-year total shareholder return of 135% and 5-year total shareholder return of 81% show a very different longer-term experience for investors.
Scan defense and aerospace peers aiming for similar step-change projects by reviewing the hand-picked 92 robotics and automation stocks that could be riding the same mission-critical spending themes as Kratos Defense & Security Solutions.
The slide in Kratos Defense & Security Solutions while projects and contracts keep rolling raises a simple tension. Are investors reassessing the business fundamentals, or has sentiment just swung too far? This is what the valuation section now tests.
Most Popular Narrative: 59% Undervalued
On the most followed view, Kratos Defense & Security Solutions screens as undervalued, with a fair value estimate of about $99.57 against a last close of $40.42. That gap relates to how far hypersonics, propulsion and unmanned programs can scale.
Kratos Defense & Security Solutions is building a larger hypersonic franchise, with hypersonic revenue around US$200m in 2025 and forecasts of roughly US$400m in 2026 and at least US$700m in 2027, supported by several hundred million dollars of recent funding, new programs such as Kraken and Nemesis, 120 solid rocket motors on order, and a multi year MACH TB budget profile of about US$7b, which could materially lift future revenue and earnings power.
See why 160 investors see Kratos Defense & Security Solutions as 59% undervalued.
Result: Fair Value of $99.57 (UNDERVALUED)
Still, the Kratos Defense & Security Solutions story leans heavily on timely hypersonic and Valkyrie production ramp ups, while foreign exchange and working capital strains could cut against that bullish script.
Find out about the key risks to this Kratos Defense & Security Solutions narrative.
Another View: Kratos Defense & Security Solutions Looks Expensive On Sales
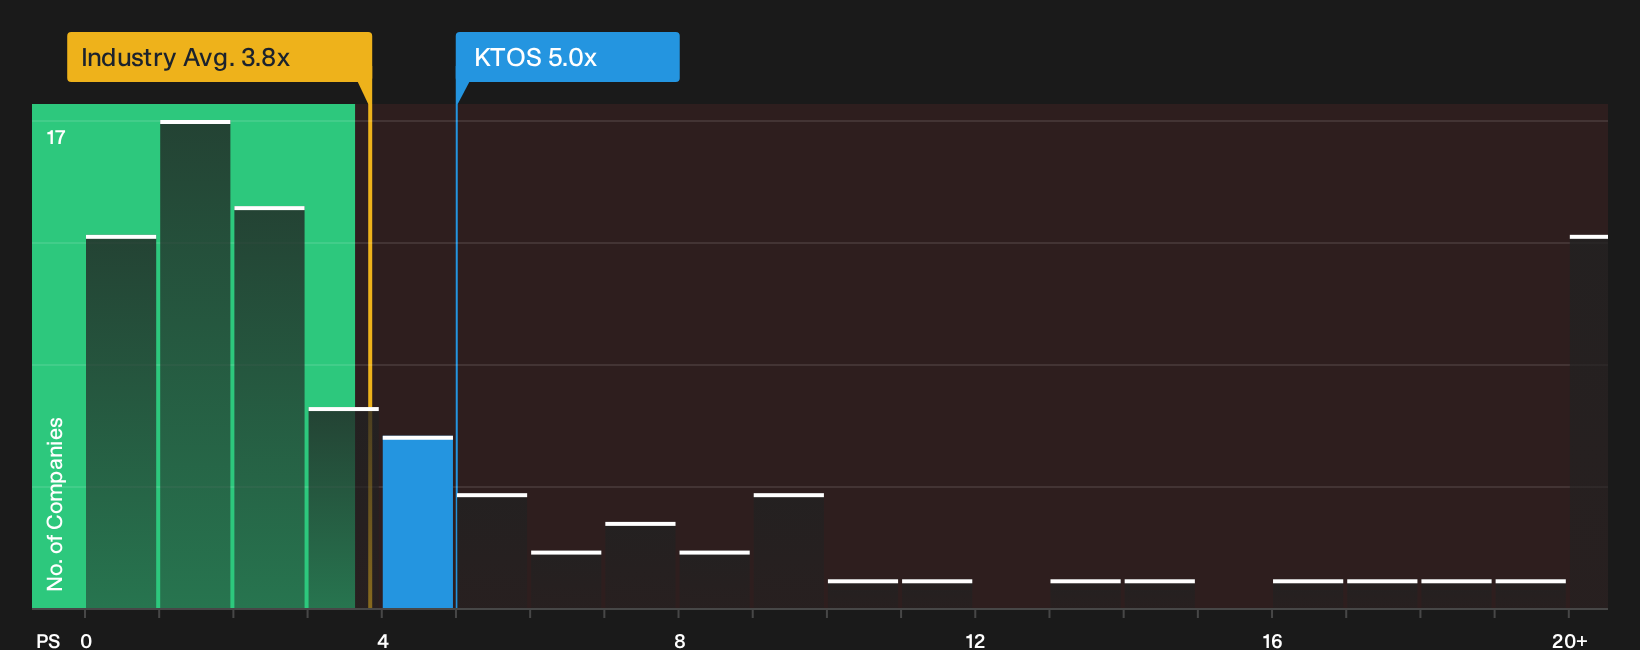
There is a catch. On a simple P/S yardstick, Kratos Defense & Security Solutions trades at about 5x, compared with a 3.8x average for US Aerospace & Defense peers and a 3x fair ratio that the market could move toward, which points to valuation risk if sentiment cools again.
To see what the numbers say about this price in more detail, review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Kratos Defense & Security Solutions is split, and that is exactly when doing your own homework matters most. Move quickly and weigh both sides by reviewing the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Kratos Defense & Security Solutions?
If you only stop with Kratos Defense & Security Solutions, you could miss other opportunities where quality, value and income potential line up more cleanly.
- Target stability first by scanning a 32 resilient stocks with low risk scores that filters for resilience when markets turn choppy.
- Hunt for value by reviewing a 33 high quality undervalued stocks that highlights companies combining quality metrics with prices that lag their fundamentals.
- Build your income stream by focusing on a 8 dividend fortresses packed with high-yield payers that still keep an eye on balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com