
Viper Energy (VNOM) Rides Royalty Momentum, Is It Still A Bargain?
Viper Energy (VNOM) sits in a different spot from typical drillers. The business collects royalty income from Permian Basin operators, so investor attention stays fixed on oil prices and how active those producers remain.
Recent trading has been constructive for Viper Energy, with the share price at US$45.02 and a 1-month share price return of 6.51% adding to a 16.09% year-to-date share price gain. The 1-year total shareholder return of 29.77% points to momentum that investors are still pricing into its royalty model as expectations around Permian activity and future cash generation evolve.
Scan royalty driven energy plays that are riding similar momentum to Viper Energy with our hand picked 20 high quality undiscovered gems list.
After a 29.77% 1 year total return and a move to US$45.02, the real tension around Viper Energy now sits in one place: Is meaningful upside still in front of the stock, or has most of it already been realised before the valuation work even begins?
Most Popular Narrative: 20% Undervalued
On the latest narrative work, Viper Energy screens on a fair value of $56 against a last close of $45.02. This puts the discussion firmly on what investors are really buying inside that mineral estate rather than on short term trading moves.
Viper is not merely a stream of today's royalty checks. It is ownership of a large Permian mineral estate through which thousands of existing wells already produce, thousands more are being developed or contemplated, and future operators can continue turning buried geology into royalty income largely with somebody else's capital.
Find out how 26 investors see Viper Energy as 20% undervalued.
Result: Fair Value of $56 (UNDERVALUED)
Still, a sharp pullback in Permian drilling activity, or any governance misstep in dealings with Diamondback, could quickly challenge the current Viper Energy narrative.
Find out about the key risks to this Viper Energy narrative.
Another View: What Multiples Say About Viper Energy
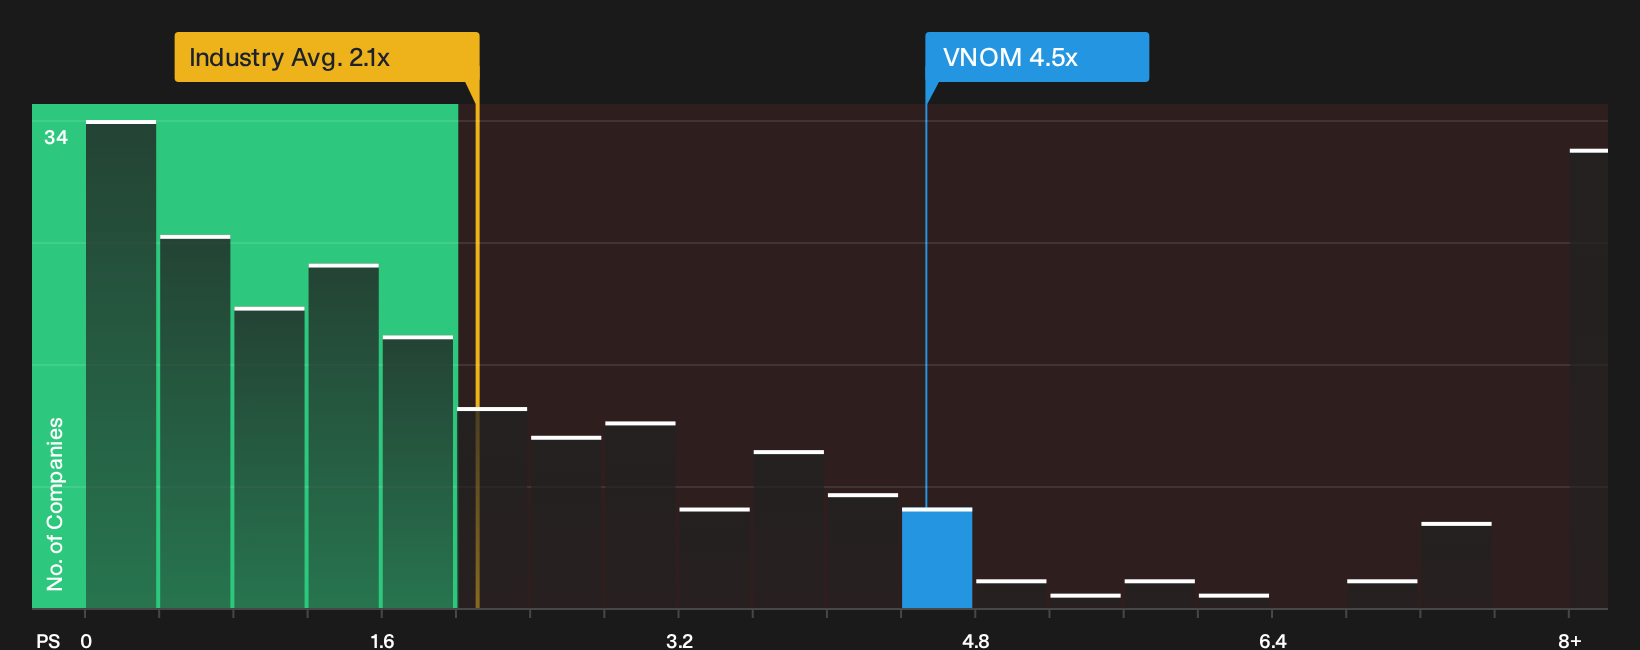
The SWS DCF work and John Eric's mineral estate framework both suggest upside for Viper Energy, yet the current market snapshot tells a different story. VNOM trades on a P/S ratio of 4.5x compared with 2.1x for the wider US Oil and Gas group and 2.3x for peers, while the fair ratio is estimated at 6.5x.
That mix of a premium versus the industry and a discount versus the fair ratio points to valuation risk if sentiment cools, but it also indicates potential room for the multiple to move closer to the fair ratio if the royalty story stays intact. Which side of that trade off do you put more weight on as an investor?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Viper Energy is split enough to keep the debate active, and that is exactly when fresh data matters most. Take a close look at both sides of the story and weigh them against your own risk tolerance by reviewing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Viper Energy?
If you stop with Viper Energy, you risk missing out on other opportunities that fit your style just as well, or even better.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (25 results) that pair financial strength with room for future execution.
- Hunt for mispriced quality by checking the 33 high quality undervalued stocks that filters for strong fundamentals at potentially appealing valuations.
- Dial up peace of mind by reviewing the 32 resilient stocks with low risk scores designed to highlight companies with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com