
1 eVTOL Stock That Could Turn $5,000 Into $50,000 -- and the 1 Risk That Could Wipe It Out
Key Points
Joby Aviation is arguably the “best in breed” play on the eVTOL market.
But its cash burn, debt, and dilution make it a risky stock to hold in a recession.
Electric vertical take-off and landing (eVTOL) aircraft could eventually replace helicopters for short-range flights because they're quieter, greener, and easier to land in crowded urban areas. According to Fortune Business Insights, the nascent eVTOL market could grow at a 36.8% CAGR from 2026 to 2034, making it a great time to invest in early movers.
One of the leading early movers is Joby Aviation (NYSE: JOBY). Joby's S4 eVTOL carries a single pilot and four passengers, travels up to 150 miles on a single charge, and reaches a maximum speed of 200 miles per hour. It can travel faster and stay airborne longer than many other eVTOLs -- including Archer Aviation's (NYSE: ACHR) Midnight -- because it uses single tilt-rotor propellers for lifting and cruising rather than using separate, heavier propellers.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
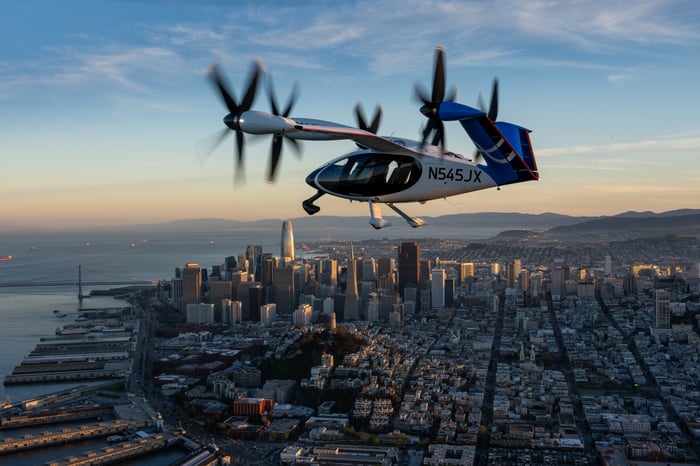
Image source: Joby Aviation.
The Federal Aviation Administration (FAA) hasn't approved Joby's first commercial flights in the U.S. yet, but it's closer to completing the FAA's multi-stage certification process than Archer. If Joby achieves that certification and becomes a vertically integrated "transportation as a service" provider that manufactures, owns, and operates its own air taxi fleet, analysts expect its revenue to soar from $53 million in 2025 to $432 million in 2028.
Therefore, Joby could turn a $5,000 investment into $50,000 over the next decade if it successfully scales its business. However, one major risk could also wipe it out.
A recession could crush Joby's stock
When interest rates were low, it was easy for Joby to take on more debt to expand its business. But as interest rates rise, it will become harder for Joby to take out loans at favorable rates. Over the past year, Joby has burned about $100-$200 million in cash per quarter. Its liquidity rose, but only because it raised cash through two stock offerings and a convertible debt offering.
Period |
Q2 2025 |
Q3 2025 |
Q4 2025 |
Q1 2026 |
Q2 2026 |
|---|---|---|---|---|---|
FCF Outflow |
($118.7 million) |
($153.2 million) |
($167.0 million) |
($222.4 million) |
($201.8 million) |
Total Liquidity |
$991 million |
$978 million |
$1.41 billion |
$2.47 billion |
$2.30 billion |
Data source: Joby Aviation. FCF = free cash flow.
That strategy caused its share count to rise 13% over the past 12 months. Its total liabilities increased 156% year over year to $985 million at the end of the second quarter. Therefore, a recession could severely throttle its cash flow and reduce its liquidity. It could also easily cut Joby's stock in half, since it's already valued at ten times its 2028 sales.
Moreover, a recession could drive Joby's major partners -- including Toyota for manufacturing, Delta for airport-to-home flights, and Uber for broader air-taxi flights -- to rein in their spending. Reduced consumer discretionary and corporate spending would also impact the initial demand for pricey air taxi flights. Simply put, this isn't a stock you want to hold when the market crashes.
Leo Sun has no position in any of the stocks mentioned. The Motley Fool recommends Delta Air Lines and Uber Technologies. The Motley Fool has a disclosure policy.