
Ferrovial (BME:FER) Shares Moved, What Is Behind The Fresh Attention?
Ferrovial (BME:FER) just led a consortium that won the I-285 East Express Lanes project in Greater Atlanta, an $8.9b public private partnership that gives the company a long-term role in US toll infrastructure.
The I-285 win comes at an interesting moment for Ferrovial. The share price has pulled back, with a 30-day share price return of -7.4% and a 90-day share price return of -20.7%, even though the 3-year total shareholder return of 70.72% and 5-year total shareholder return of 83.02% point to a much stronger longer-run picture. This suggests that recent weakness may reflect shifting risk perceptions around infrastructure projects rather than a clear break from the longer-term story.
Scan other infrastructure-heavy plays moving on long-term contracts and toll roads using the hand-picked 42 power grid technology and infrastructure stocks, which sits in a similar corridor of capital-intensive projects.
Ferrovial now trades below both analyst targets and an internal fair value estimate after a sharp pullback. Does that gap reflect genuine project risk, or a market that is over-discounting caution?
Most Popular Narrative: 27% Undervalued
Ferrovial's most followed valuation narrative points to a fair value of €60.30 against a last close of €44.20, which frames the current pullback as a wide gap between market pricing and that central estimate built on a €9,859.0m revenue base and €592.0m of earnings.
The asset-light model and continual recycling of capital into early-stage projects is currently enhancing return metrics, but if macro or industry trends shift (for example, higher interest rates, tighter funding, elevated competition or delays), new projects may not match the returns of recently divested mature assets, resulting in lower future ROIC and possible downward pressure on net profit growth.
See why 8 investors see Ferrovial as 27% undervalued.
Result: Fair Value of €60.30 (UNDERVALUED)
Still, the I-24 project overhang and questions around green transition execution risk could easily reverse the Ferrovial undervaluation story if sentiment turns more cautious.
Find out about the key risks to this Ferrovial narrative.
Another View On Ferrovial’s Valuation
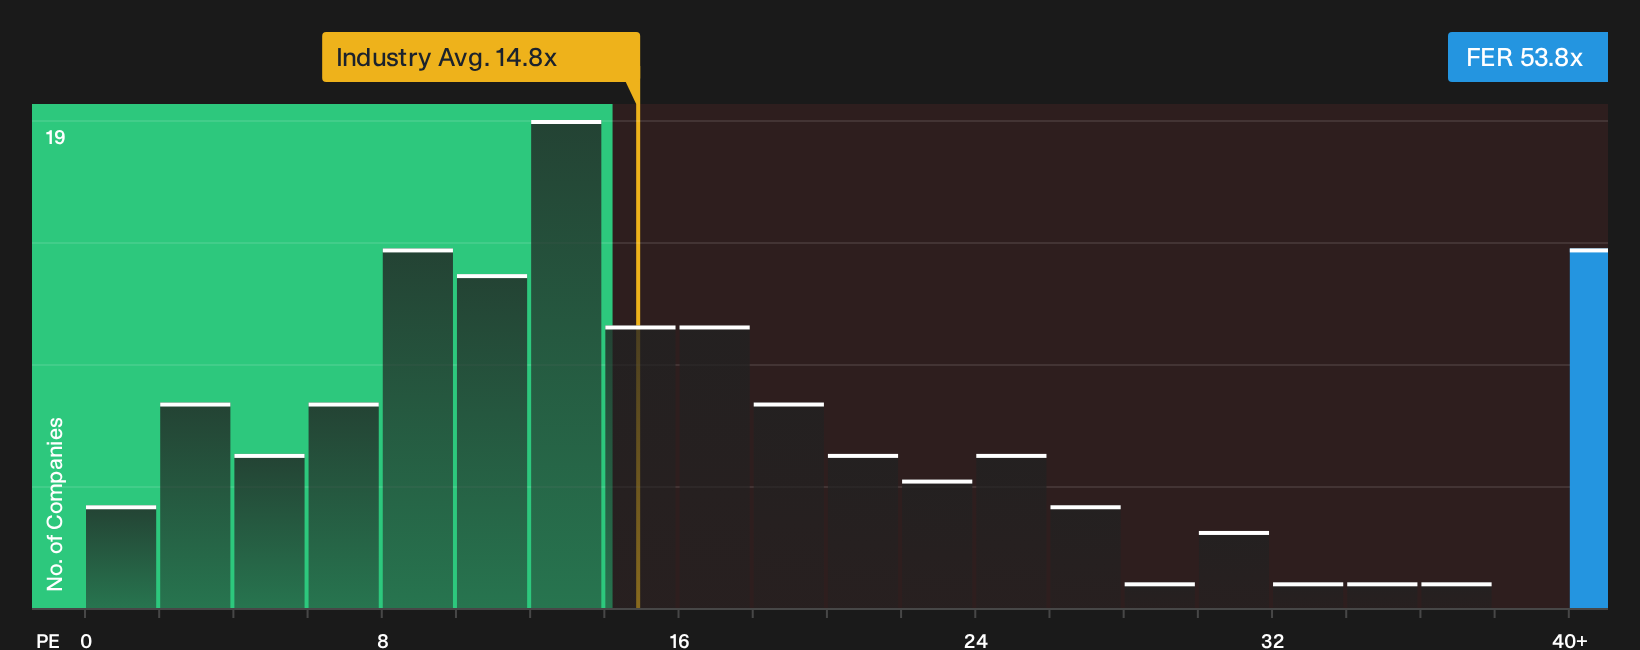
That €60.30 fair value is built on forecasts, but the market is also signaling something through simple price ratios. Ferrovial trades on a P/E of 53.8x, which is far richer than both the European Construction sector at 14.8x and a fair ratio of 27.7x suggested by regression work. That kind of gap can mean investors are paying up for the story right now, so the key question is whether you agree the business justifies nearly double the fair ratio over time.
To see how the numbers stack up against this richer pricing, and what it might mean for valuation risk, check out the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Ferrovial's value and risk can feel confusing, so move fast, review the data, and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Ferrovial?
If Ferrovial has sharpened your focus on long-term projects and pricing gaps, broaden your watchlist and pressure test your thesis with other targeted opportunities.
- Spot potential mispricings fast by scanning a curated pool of higher quality opportunities through the 195 high quality undervalued stocks.
- Strengthen your downside protection by searching for companies with cleaner finances using the list of solid balance sheet and fundamentals (203 results).
- Hunt for overlooked potential by checking the 613 high quality undiscovered gems before others start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com