
United Airlines (UAL) Stock May Be Fairly Valued Despite Rising Cost Concerns
United Airlines Holdings has delivered a powerful multi year share price run. However, the recent pullback and shifting cost backdrop leave a clear question for investors about whether today’s US$96.10 price is adequately supported by the cash the airline can generate.
- Over the past 3 years the stock has gained 171.6%, which puts a lot of weight on whether the cash flows behind that move can carry it further.
- Rising fuel, labor and fleet investment costs, alongside expectations for strong revenue, can reshape how much free cash the airline keeps from every dollar it brings in and how predictable that cash looks over time.
- What if you looked at United Airlines Holdings through its earnings instead? See why United Airlines Holdings's 8.9x P/E tells a different valuation story.
The stock’s next move may depend on whether United Airlines Holdings’ current share price lines up with what its cash flows imply as an intrinsic value.
If you want to test the same cash flow question that hangs over United Airlines Holdings against a wider set of potential ideas, run the numbers across 33 high quality undervalued stocks.
Is United Airlines Holdings Fairly Priced on Cash Flow?
The Discounted Cash Flow model estimates what United Airlines Holdings could be worth based on the cash it may generate for shareholders over time. Latest twelve month free cash flow sits at about $2.35b, and the projections used in this DCF assume that cash generation broadly grows rather than shrinks through the next decade, but at relatively moderate rates.
The outcome of that cash flow path puts the estimated intrinsic value broadly in line with the current $96.10 share price, which suggests the market is already crediting United Airlines Holdings with a steady, ongoing ability to produce cash. The upcoming Q3 2026 earnings report, with rising fuel and labor costs and a focus on margin stability, helps explain why investors are not pushing the stock far away from what the DCF implies. To see the full set of inputs and how they roll up to the valuation, check the detailed model behind this estimate. Find out what United Airlines Holdings could be worth using our Discounted Cash Flow (DCF) estimate.
The United Airlines Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for United Airlines Holdings pick up where the cash flow puzzle leaves off and explain what would need to change in growth, profitability and earnings for the stock to appear meaningfully higher or lower than today's price. Each narrative links its valuation view to a specific path for United Airlines Holdings' revenue trends, margin profile and key risks, giving you something concrete to revisit as fresh results and new data points arrive on the Community page.
One of the top community narratives on United Airlines Holdings: 37% undervalued
"The main thing that has to go right is that United Airlines Holdings turns its premium, technology and fleet investments into margin expansion…"
Discover why this Narrative puts United Airlines Holdings at 37% undervalued.
One more United Airlines Holdings signal that could change the story
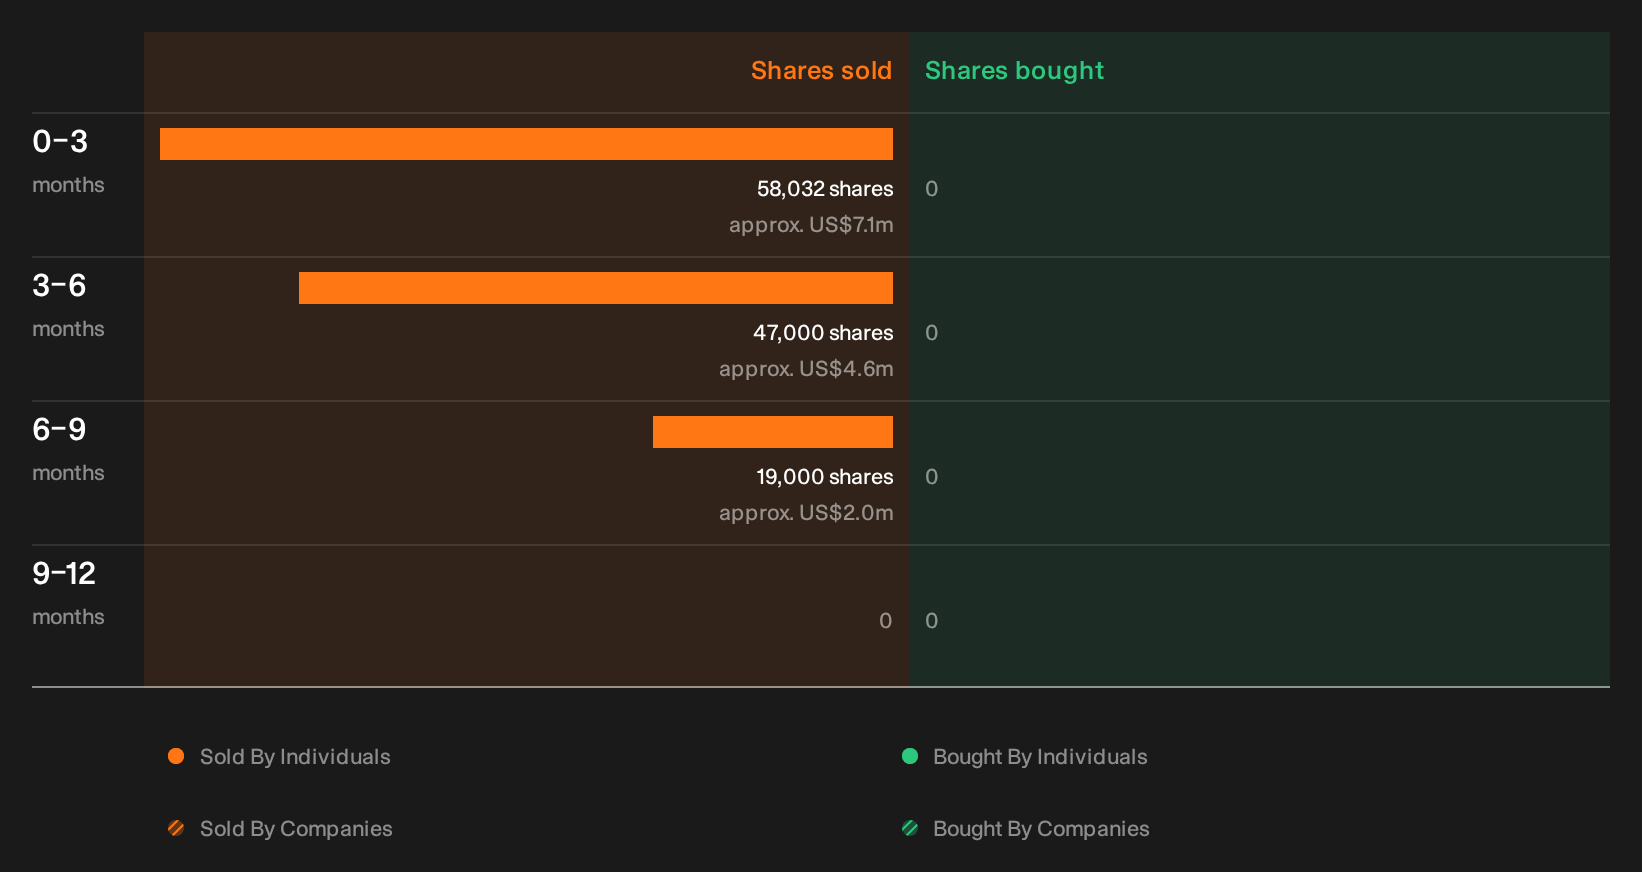
Cash flow and valuation paint one picture for United Airlines Holdings, but recent insider share sales flagged by our checks raise a separate question about behavior inside the boardroom that deserves a closer look. See the recent insider selling flagged for United Airlines Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com