
China Resources Mixc Lifestyle Services (SEHK:1209) Leans On Fee Income, Is It Still Undervalued?
China Resources Mixc Lifestyle Services (SEHK:1209) is back in focus after recent commentary highlighted its asset light property services model, recurring fee income and cash flow expectations in the context of softer development activity at parent China Resources Land.
The recent 1-day share price return of 2.32% and 1-month share price gain of 5.70% put China Resources Mixc Lifestyle Services at HK$39.68. This suggests momentum is stabilising after a year-to-date share price decline of 7.85% and a 3-year total shareholder return of 62.10%, which still shapes sentiment around the current premium P/E valuation and cash flow story.
Spot opportunities with a similar asset light, cash flow focused profile by scanning our hand picked list of solid balance sheet and fundamentals (203 results) as a comparison set to China Resources Mixc Lifestyle Services.After a sharp three year run and a recent bounce, China Resources Mixc Lifestyle Services trades on a premium P/E that leans heavily on its fee based model and cash flow story. Does that still leave enough upside for the risk taken?
Preferred Price-to-Earnings of 18.5x: Is it justified?
China Resources Mixc Lifestyle Services trades on a P/E of 18.5x, which is a rich tag compared with much of the Hong Kong real estate space, yet still sits below closer peers and its own cash flow estimate of HK$51.38 from the SWS DCF model.
The P/E ratio compares the current share price to earnings per share and, for a service heavy property manager like China Resources Mixc Lifestyle Services, it often reflects how much investors are willing to pay for fee based earnings and cash conversion rather than development profits.
Here, the market appears to be pricing in ongoing earnings growth and high returns on equity. Earnings are forecast to expand at 10.4% per year and the current Return on Equity sits at 27%. The stock also trades at an estimated 22.8% discount to the SWS DCF fair value of HK$51.38 based on projected cash flows.
The tension is clear when you compare this 18.5x P/E to two different yardsticks: the Hong Kong real estate industry average of 8.9x and the estimated fair P/E of 13.7x. Both suggest the market is assigning a materially richer multiple than broad sector levels and a level the P/E could revert toward if enthusiasm for the cash flow story cools.
Explore the SWS fair ratio for China Resources Mixc Lifestyle Services.
Result: Price-to-Earnings of 18.5x (OVERVALUED)
Still, the story around China Resources Mixc Lifestyle Services could be challenged if sector-wide real estate sentiment weakens further or if expectations for fee-based growth moderate.
Find out about the key risks to this China Resources Mixc Lifestyle Services narrative.
Another View: SWS DCF Says HK$51.38 Fair Value
While the P/E suggests China Resources Mixc Lifestyle Services trades rich against the Hong Kong real estate sector, the SWS DCF model points the other way. On that cash flow view, a fair value of HK$51.38 implies the current HK$39.68 level is undervalued. Which signal do you trust more when earnings quality and sector mood pull in different directions?
Look into how the SWS DCF model arrives at its fair value.
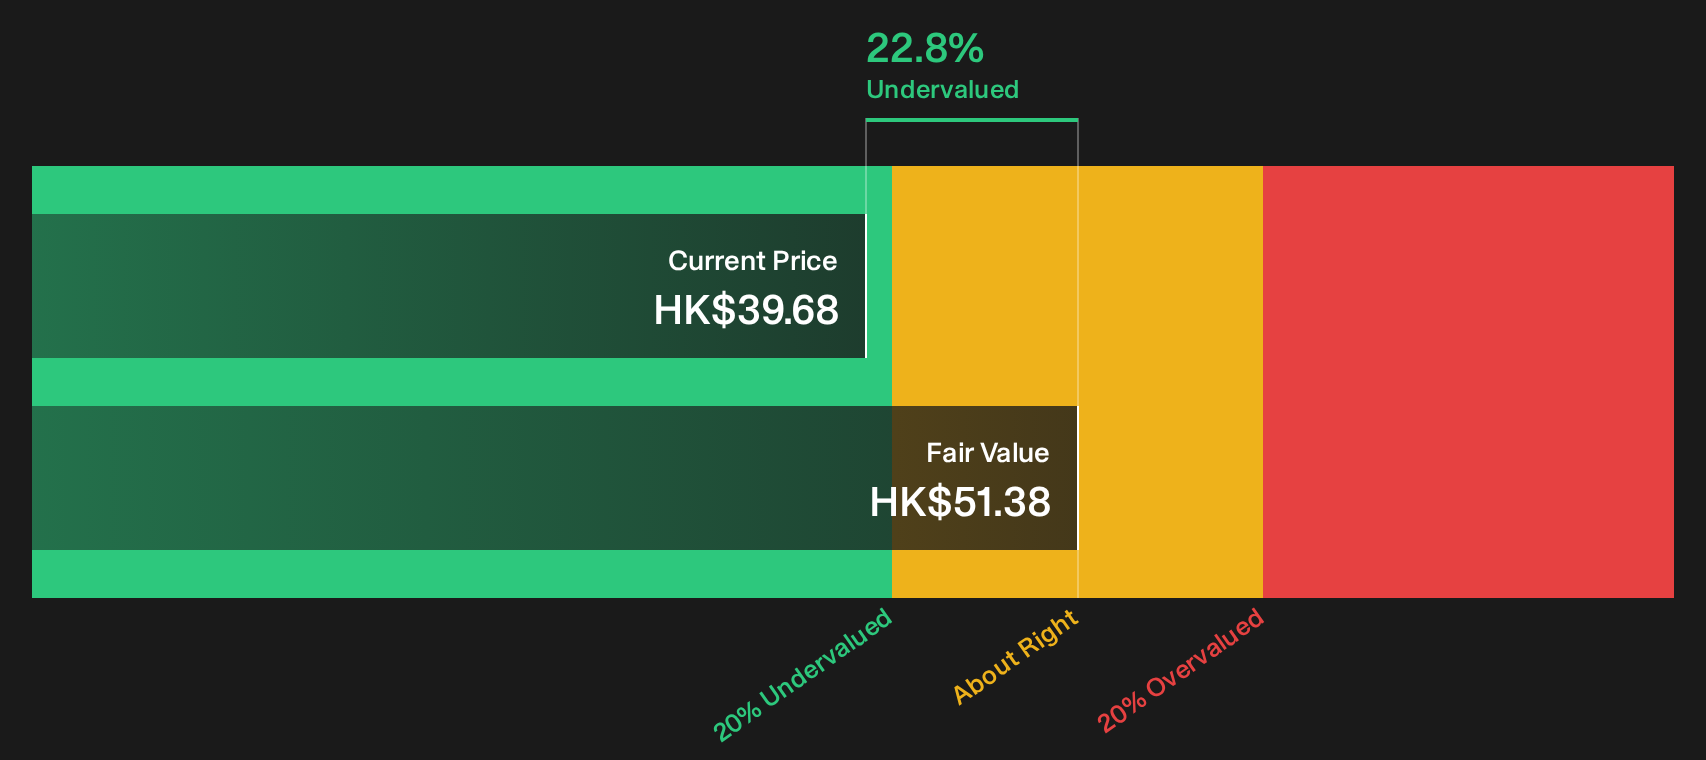
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Resources Mixc Lifestyle Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on China Resources Mixc Lifestyle Services are clear, which is exactly why it helps to inspect the numbers yourself and move quickly while sentiment is divided. To weigh the upside versus the red flags in a structured way, start with a look at the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond China Resources Mixc Lifestyle Services?
Do not stop your research with one property services stock when a broader watchlist could reveal stronger balance sheets, steadier cash flows and different return profiles.
- Supercharge your hunt for potential value by scanning a curated pool of companies through the 196 high quality undervalued stocks.
- Guard your capital and focus on durability by using the 231 resilient stocks with low risk scores to surface businesses with more resilient risk profiles.
- Spot potential future leaders early by filtering for underfollowed quality through the 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com