
Is Create Restaurants Holdings (TSE:3387) Fully Valued On New Guidance And Dividend News?
Create Restaurants Holdings (TSE:3387) put income and guidance in focus on 14 October 2026, pairing new earnings targets for the year to February 2027 with an interim dividend decision following a recent stock split.
At a share price of ¥784.0, create restaurants holdings has seen a 5.52% one-day share price return around the guidance and dividend news. The 1-year total shareholder return of 3.39% compares with a much stronger 3-year total shareholder return of 61.76%, suggesting long-term momentum has been solid even as more recent moves have been modest.
Scan other restaurant and consumer stocks reacting to earnings guidance and dividend decisions by using a curated list of 73 high quality undiscovered gems that may be flying under most investors' radar.
After the guidance and dividend update, the question around create restaurants holdings is simple: Has the recent share move already priced in the good news, or is meaningful upside still on the table as valuation comes into focus?
Price-to-Earnings of 84.6x: Is it justified?
On simple valuation math, create restaurants holdings carries a rich label, with a P/E of 84.6x at a last close of ¥784, which is far above both its own fair ratio estimate and hospitality peers.
The P/E multiple compares the current share price to earnings per share and gives you a quick sense of how much investors are paying for each unit of profit. For a food service operator like create restaurants holdings, which runs restaurant brands, bakery chains, and contract facilities, this metric often reflects expectations around profit resilience and future earnings growth rather than just the latest year of results.
Here, the market is paying a large premium. The P/E of 84.6x is higher than the estimated fair P/E of 26.9x. This implies investors are currently assigning a much heavier price tag to each yen of earnings than the fair ratio suggests the business might command. Against the JP Hospitality industry average of 21.9x, the gap is also wide, so the stock trades at a significantly richer valuation than sector peers that are exposed to similar end markets.
Explore the SWS fair ratio for create restaurants holdings.
Result: Price-to-earnings of 84.6x (OVERVALUED)
Still, Create Restaurants Holdings faces clear risks, including shifts in consumer dining habits and any squeeze on profitability that makes an 84.6x P/E harder to defend.
Find out about the key risks to this create restaurants holdings narrative.
Another view on create restaurants holdings valuation
The P/E discussion paints create restaurants holdings as expensive, yet the SWS DCF model tells a softer story. On that framework, the shares at ¥784 sit above an estimated future cash flow value of ¥675.37, which still flags overvaluation but with a smaller premium. Which signal should be treated as more important when market mood shifts?
Look into how the SWS DCF model arrives at its fair value.
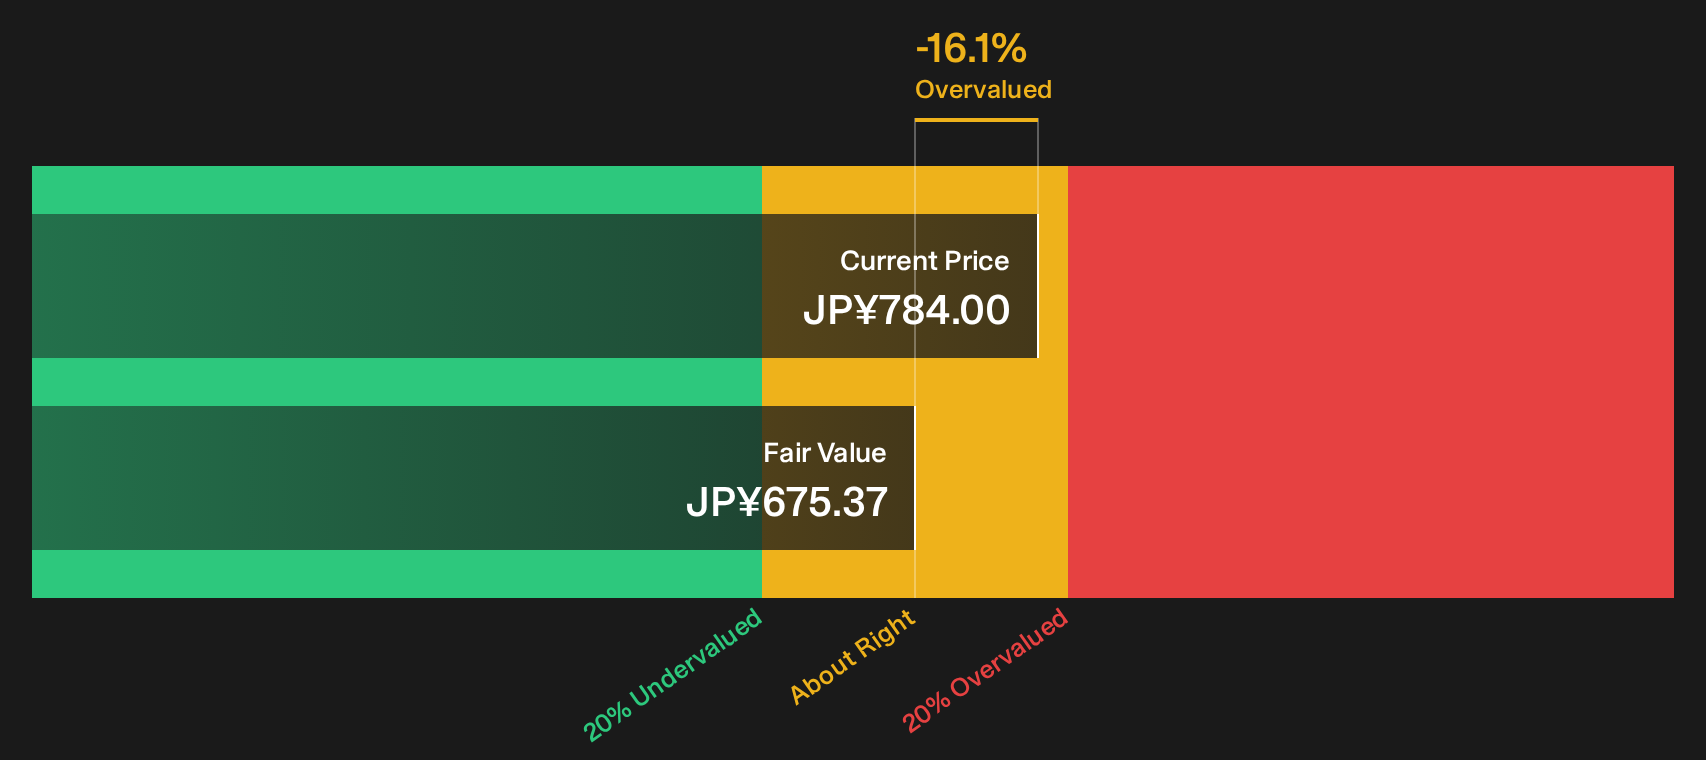
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out create restaurants holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the rich valuation on create restaurants holdings leaves you unsure, that hesitation is useful. Act while the data is fresh and weigh the optimism against the risks by checking the 1 key reward
Looking for more investment ideas beyond create restaurants holdings?
Do not stop with a single restaurant stock when a broader watchlist could surface better fits for your goals.
- Target potential turnaround stories by scanning carefully selected smaller companies using the 1 elite penny stocks with strong financials to find low share prices paired with meaningful business fundamentals.
- Strengthen your watchlist with businesses that pair quality metrics and attractive pricing by reviewing the 13 high quality undervalued stocks and seeing which ones meet your standards.
- Reduce portfolio stress by focusing on financial resilience with a 22 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier track records.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com