
Is Odfjell Drilling (OB:ODL) Cheap On Equinor’s Deepsea Atlantic Contract Extension?
Odfjell Drilling (OB:ODL) moved back into focus after Equinor exercised options for two extra wells on the Deepsea Atlantic rig, extending the firm contract into late Q4 2027 and reinforcing long-term backlog visibility.
Odfjell Drilling’s latest contract win comes after a strong run, with the share price delivering a 19.77% 90-day return and a 17.62% year-to-date share price gain. The 1-year total shareholder return of 51.52% and the very large 5-year total shareholder return indicate that momentum has been building over time as investors reassess both growth prospects and risk around the upgraded rig fleet and extended backlog.
Scan how Odfjell Drilling’s contract-backed momentum compares with other rig and energy plays by reviewing our curated list of 196 high quality undervalued stocks.
After that contract extension and a share price that has already moved hard, the real tension is simple. Do you pay up for Odfjell Drilling’s backlog today, or wait and hope for a cheaper entry later?
Most Popular Narrative: 7% Undervalued
On the latest narrative work, Odfjell Drilling screens on a fair value of NOK112.33 against a NOK104.80 close, which points to modest upside being priced into a detailed cash flow and backlog story rather than a blue-sky call.
The company has locked in high quality, long term contracts with major customers at high day rates, with total firm backlog discussed at about US$2.1b to US$2.3b and individual rigs such as Deepsea Nordkapp and Deepsea Bergen now covered into 2028 and 2031, which underpins forward revenue and provides clearer visibility on EBITDA.
See why 13 investors see Odfjell Drilling as 7% undervalued.
Result: Fair Value of NOK112.33 (UNDERVALUED)
Still, Odfjell Drilling’s story depends heavily on a few clients and on rigs staying on hire. Slower option exercises or fresh technical issues could quickly challenge this thesis.
Find out about the key risks to this Odfjell Drilling narrative.
Another View: Odfjell Drilling On Earnings Multiples
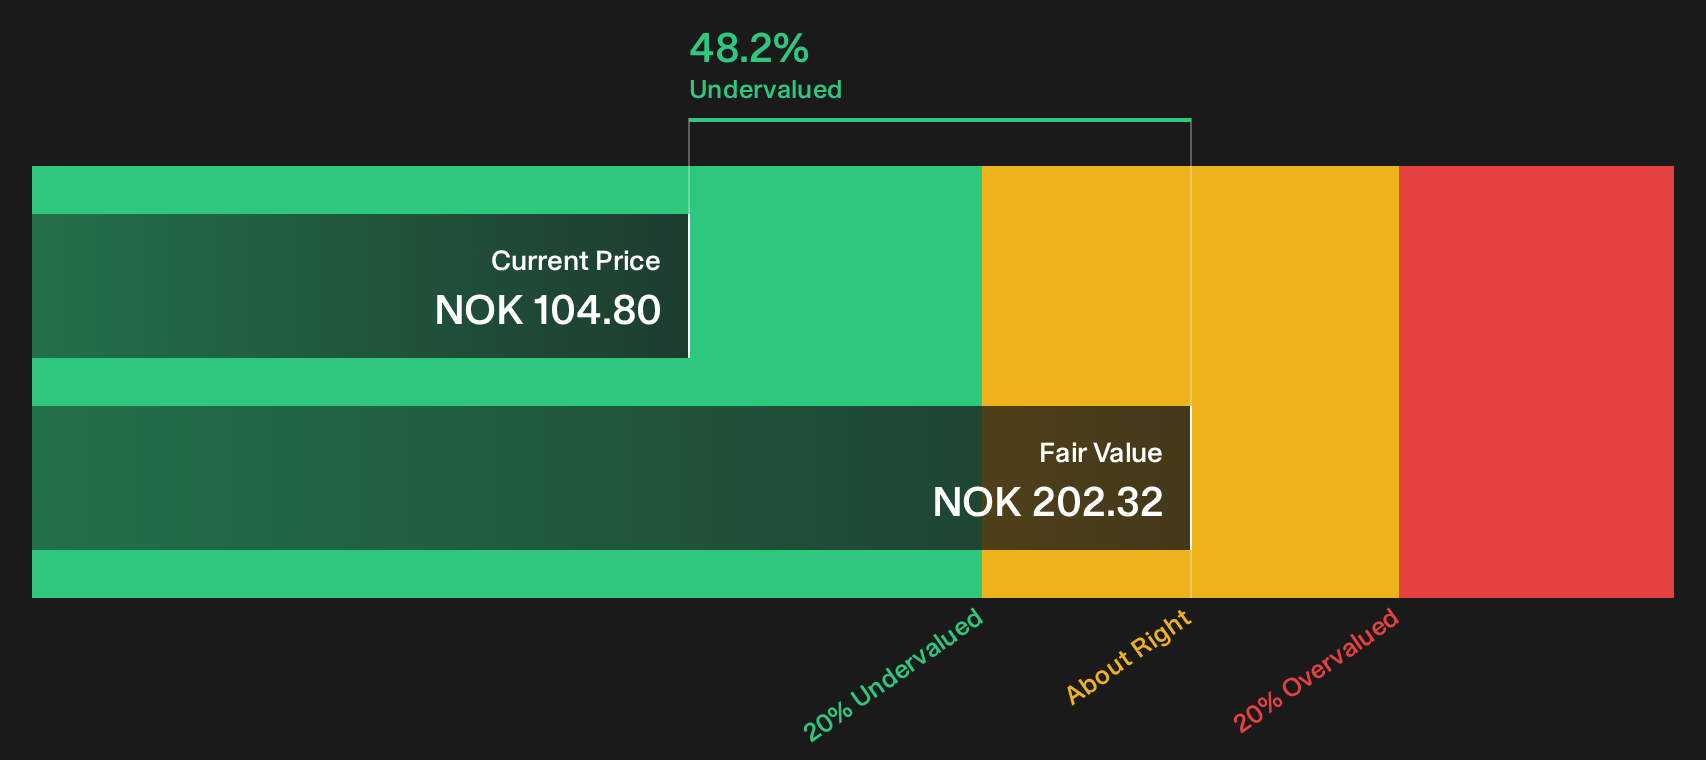
The SWS DCF model indicates that Odfjell Drilling is trading at a large discount to an estimated fair value of NOK202.32, which presents the stock as undervalued on cash flows. At the same time, the current 11.9x P/E is close to a fair ratio of 11.6x and roughly in line with a 12.5x peer average. If the multiple perspective appears almost fully reflected, how much weight should be placed on the cash flow story?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Odfjell Drilling’s value story so far. If you want to move fast and rely on your own judgment, weigh up the 3 key rewards and 2 important warning signs.
Looking for more Odfjell Drilling sized ideas?
You have seen how one contract heavy story can reshape a thesis. Do not stop here. Your next strong idea could already be on the list.
- Target dependable income streams by reviewing dividend payers that clear strict quality hurdles with the 217 dividend fortresses.
- Hunt for mispriced opportunities by scanning companies that pair quality fundamentals with attractive pricing via the 613 high quality undiscovered gems.
- Prioritise resilience first and shortlist businesses screened for lower risk profiles using the 231 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com